The euro has fallen for four straight weeks to below 1.13 against the dollar, its weakest level in nearly 18 months. The usual reading of a EUR/USD decline is that the eurozone is in trouble, but the evidence points somewhere more specific than that.
The timing matters. French 10-year yields (the return investors demand to lend to the French government for a decade) sit at their highest since around 2002, the gap between French and German yields is the widest since the 2011-2012 crisis era, and the Federal Reserve has turned hawkish. If you hold euro assets, trade currencies, travel or import goods, you are exposed to this move.
Here is how the two forces pushing the pair down fit together, and why one DBS strategist argues this is not 2012 again.
Two forces behind the slide: a hawkish Fed and a repriced France
The pair slipped from levels above 1.13 in early September 2026 to about 1.12, a fall over four weeks. Reuters described it as the steepest run in around four months, and the euro closed near 1.1207 on 5 October.
That looks like one story. It is actually two running at once: a rate story in the United States and a fiscal story in France.
- Level: below 1.13 on 2 October, near 1.1207 on 5 October
- Change: roughly 3-4% lower since early September
- Fed target range: 3.75-4.00% after a September hike
- ECB deposit rate: no precise level was available in the research
One data gap is worth flagging: no source gives an exact four-week high-low range, and no market-implied hike probabilities were available. The direction is clear even if the precise magnitude is not.
The rate-differential driver
A rate differential is the gap between what you earn on dollar assets and on euro assets. Philip Wee, a strategist at DBS, argues that expectations of Fed tightening are outweighing expectations of ECB tightening.
Philip Wee, DBS: Markets are pricing more upside risk to US rates than to euro-area rates, while French fiscal troubles are drawing more attention than US ones.
The Fed’s hawkish shift came in mid-September. Softer recent US data has tempered hike expectations, though it has not removed them.
The Fed-ECB rate gap is the specific spread that international investors weigh when choosing between dollar and euro assets, and it has become the dominant input for EUR/USD this year.
The French fiscal driver
The second force is France. Worries about the deficit path have pushed Paris into the spotlight, and France remains under an EU excessive deficit procedure.
Wee says higher US Treasury yields spilled into euro-area bonds and exposed French problems faster than American ones. What this tells you is that a currency falling on a rate gap signals investors preferring dollar returns, not necessarily a verdict on the health of the euro area.
It also tells you which driver could turn quickly. US rate expectations can reverse within weeks; French fiscal repair is likely to linger.
When big ASX news breaks, our subscribers know first
How rate gaps and sovereign spreads move a currency
On your screen, two things happen together: the euro falls and the gap between French and German bond yields widens. Understanding why one pushes the other gives you a framework for reading any rates-driven currency move.
A yield is the annual return on a bond, expressed as a percentage of its price. A sovereign spread is the difference between the yields of two governments’ bonds, and the OAT-Bund spread compares France’s 10-year bond (the OAT) with Germany’s (the Bund). A wide spread is effectively a price tag on French risk.
Because a bond’s coupon is fixed, a falling price automatically lifts the yield, which is why understanding how bond yields move lets you read a spread widening as a price signal on French risk rather than as noise.
| Indicator | Level | What it signals |
|---|---|---|
| French 10-year OAT | About 4.90-4.99% | Higher compensation demanded for French risk |
| German 10-year Bund | About 3.43-3.53% | Benchmark safe asset |
| OAT-Bund spread | About 146 bp at the latest close | Sharp repricing of French risk |
| 12-month average spread | Not available in the research | The normal baseline the spread has left behind |
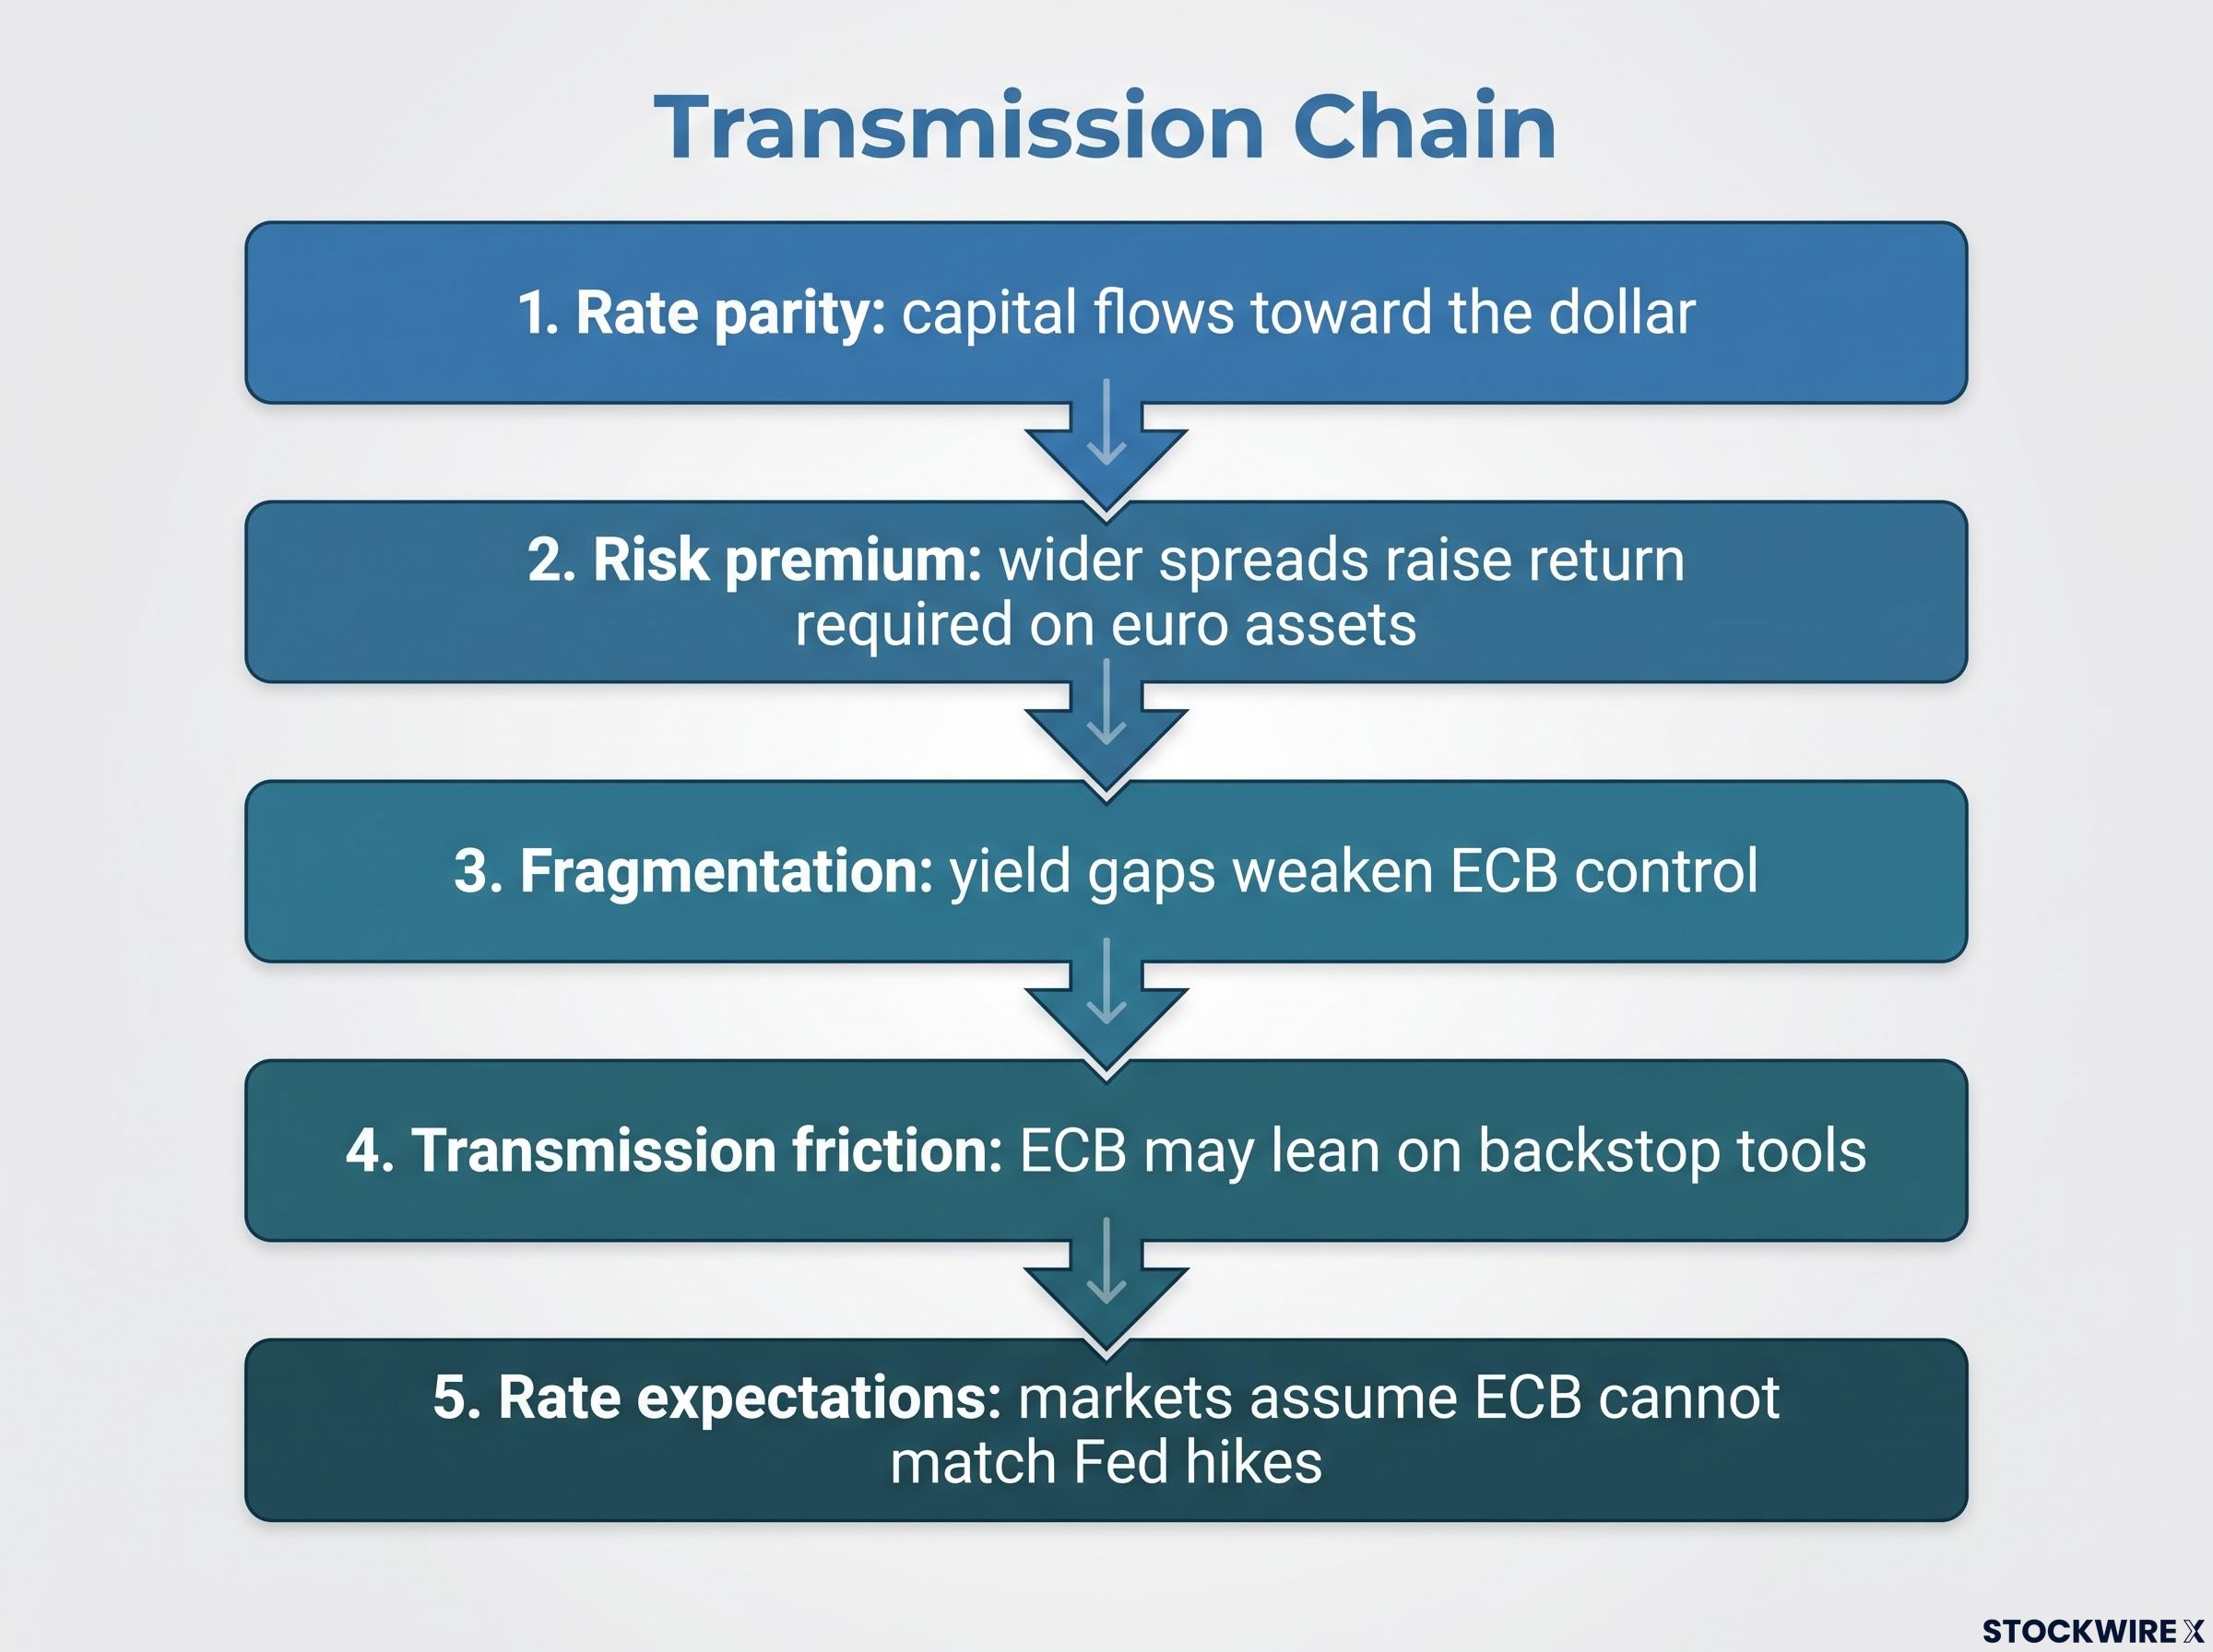
The transmission chain runs in five steps:
- Rate parity: capital flows toward the currency offering the better return, here the dollar.
- Risk premium: wider spreads raise the return required on euro assets and deter foreign buyers.
- Fragmentation: big gaps between member countries’ yields weaken the ECB’s control over borrowing costs across the bloc.
- Transmission friction: the ECB may have to lean on backstop tools rather than normalise rates, and that uncertainty weighs on the euro.
- Rate expectations: markets assume the ECB cannot match Fed hikes without destabilising high-debt members.
The last step closes a feedback loop. Spreads widen on fiscal fears, the rate gap entrenches, and the euro stays under pressure.
Reading the OAT-Bund spread
French yields rose while German yields fell, as safe-haven buying pulled Bund yields down and amplified the spread.
Reported figures vary by source and timing. Reuters and ActionForex cited 132.86 bp on 1 October as the widest since the 2012 crisis, while Reuters via Kelo cited about 150 bp, the highest since 2011. The direction is consistent, and the stress may spill into crosses such as EUR/CHF.
Why this is not a repeat of 2012: the TPI and other safeguards
The resemblance is real. Spread levels not seen since the 2011-2012 crisis era invite the comparison, so the worry is not irrational.
Then the differences stack up. In 2012, Greek fiscal disclosures set off a loss of confidence across peripheral Europe, according to Wee. Today the stress is centred on France, a large, highly rated core economy with deeper domestic funding.
| Factor | 2012 | 2026 |
|---|---|---|
| Trigger | Greek fiscal disclosures | French fiscal trajectory and Fed repricing |
| Scope | Contagion across peripheral Europe | Narrower, France-specific stress |
| Backstop | OMT announced, largely untested | OMT plus the TPI |
| Bank buffers | Weaker | Stronger, with the ESM and banking union |
Governance has also tightened, with imbalance monitoring and Recovery and Resilience Plans in place. German yields falling on safe-haven flows points to a France-specific story rather than a bloc-wide flight.
What the TPI is and how it is triggered
The Transmission Protection Instrument (TPI) was announced by the ECB Governing Council on 21 July 2022, after the Italian spread episode. It lets the Eurosystem buy public-sector securities with maturities of one to ten years in a country facing unwarranted, disorderly market stress.
Activation is discretionary, and a country must meet four cumulative criteria:
- Compliance with the EU fiscal framework, with no excessive deficit procedure.
- No severe macroeconomic imbalances.
- Fiscal sustainability.
- Sound macroeconomic policies, including adherence to Recovery and Resilience Plan commitments.
The TPI has reportedly never been activated, though that should be treated as unconfirmed. Its existence changes how severe a widening can become, which is why Wee reads this as a currency-pressure episode rather than the start of a wider sovereign debt crisis.
Where the “contained” view could break
The reassuring reading has holes. Wee sees a contained repricing of a known French problem, while Reuters coverage stresses ratings, politics and the scale of the widening, and treats France as a possible euro-negative factor.
Limits of the TPI
France is under an excessive deficit procedure, which cuts against the first eligibility criterion. Eligibility tied to fiscal rules could make activation politically contentious, and the tool has never been tested on a core economy.
Intereconomics (2023): The TPI’s activation conditions are “flawed by design”, with strict criteria that may delay or prevent timely intervention.
The ECB’s Joachim Nagel has reportedly stressed that inflation remains the primary focus, though this is unverified. Leaning on anti-fragmentation tools could also limit the ECB’s freedom to hike, which would reinforce dollar support.
Political risk ahead of the 2027 French elections and rating-agency sensitivity add further uncertainty, though no new rating actions have been confirmed.
Analysts see French budget rollover risk as the most probable outcome for 2027, which could push the deficit toward 6.0% of GDP and keep the pressure on spreads.
The dollar view cuts both ways. If you are reading the euro’s direction, these are the signals to separate:
- Signals the euro stays weak: firm US data keeping the Fed hawkish, a spread that keeps widening, rating pressure on France, or no ECB response.
- Signals the euro recovers: US data weakening and an early Fed pivot, falling global bond yields, or a flight to core euro debt compressing spreads.
The euro’s path hinges on a handful of observable variables, so you can monitor them rather than lean on a single narrative.
What to watch as the EUR/USD decline tests the 2012 comparison
The slide is a rate-differential story, amplified by a France-specific spread shock and cushioned by safeguards that did not exist in 2012. Neither the crisis story nor the all-clear story fits the evidence cleanly.
Four watchpoints will decide which view proves right:
- US data and the Fed’s rate path
- The direction of the OAT-Bund spread
- French budget and rating developments
- Any ECB signal on the TPI
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. These statements are speculative and subject to change based on market developments, and past performance does not guarantee future results.