The Mexican Peso has just dropped roughly 3% over a single week. Here is the part that does not immediately add up: that happened while Banxico, Mexico’s central bank, held its benchmark rate at 6.50%, comfortably above the US Federal Reserve’s 3.75-4.00% target range.
If Mexican rates are still higher, why is the Peso falling?
The answer sits in the gap between the two, not the level of either. The spread between US and Mexican rates has narrowed to its tightest point since 2015, and for a particular kind of currency investor, that direction of travel matters more than today’s headline numbers.
That investor is running what is known as a carry trade, and the Peso has long been one of its favourite destinations. Here is how the mechanics work, and why the numbers unfolding right now are shifting the calculation.
What a carry trade is, and why the Peso became a favourite
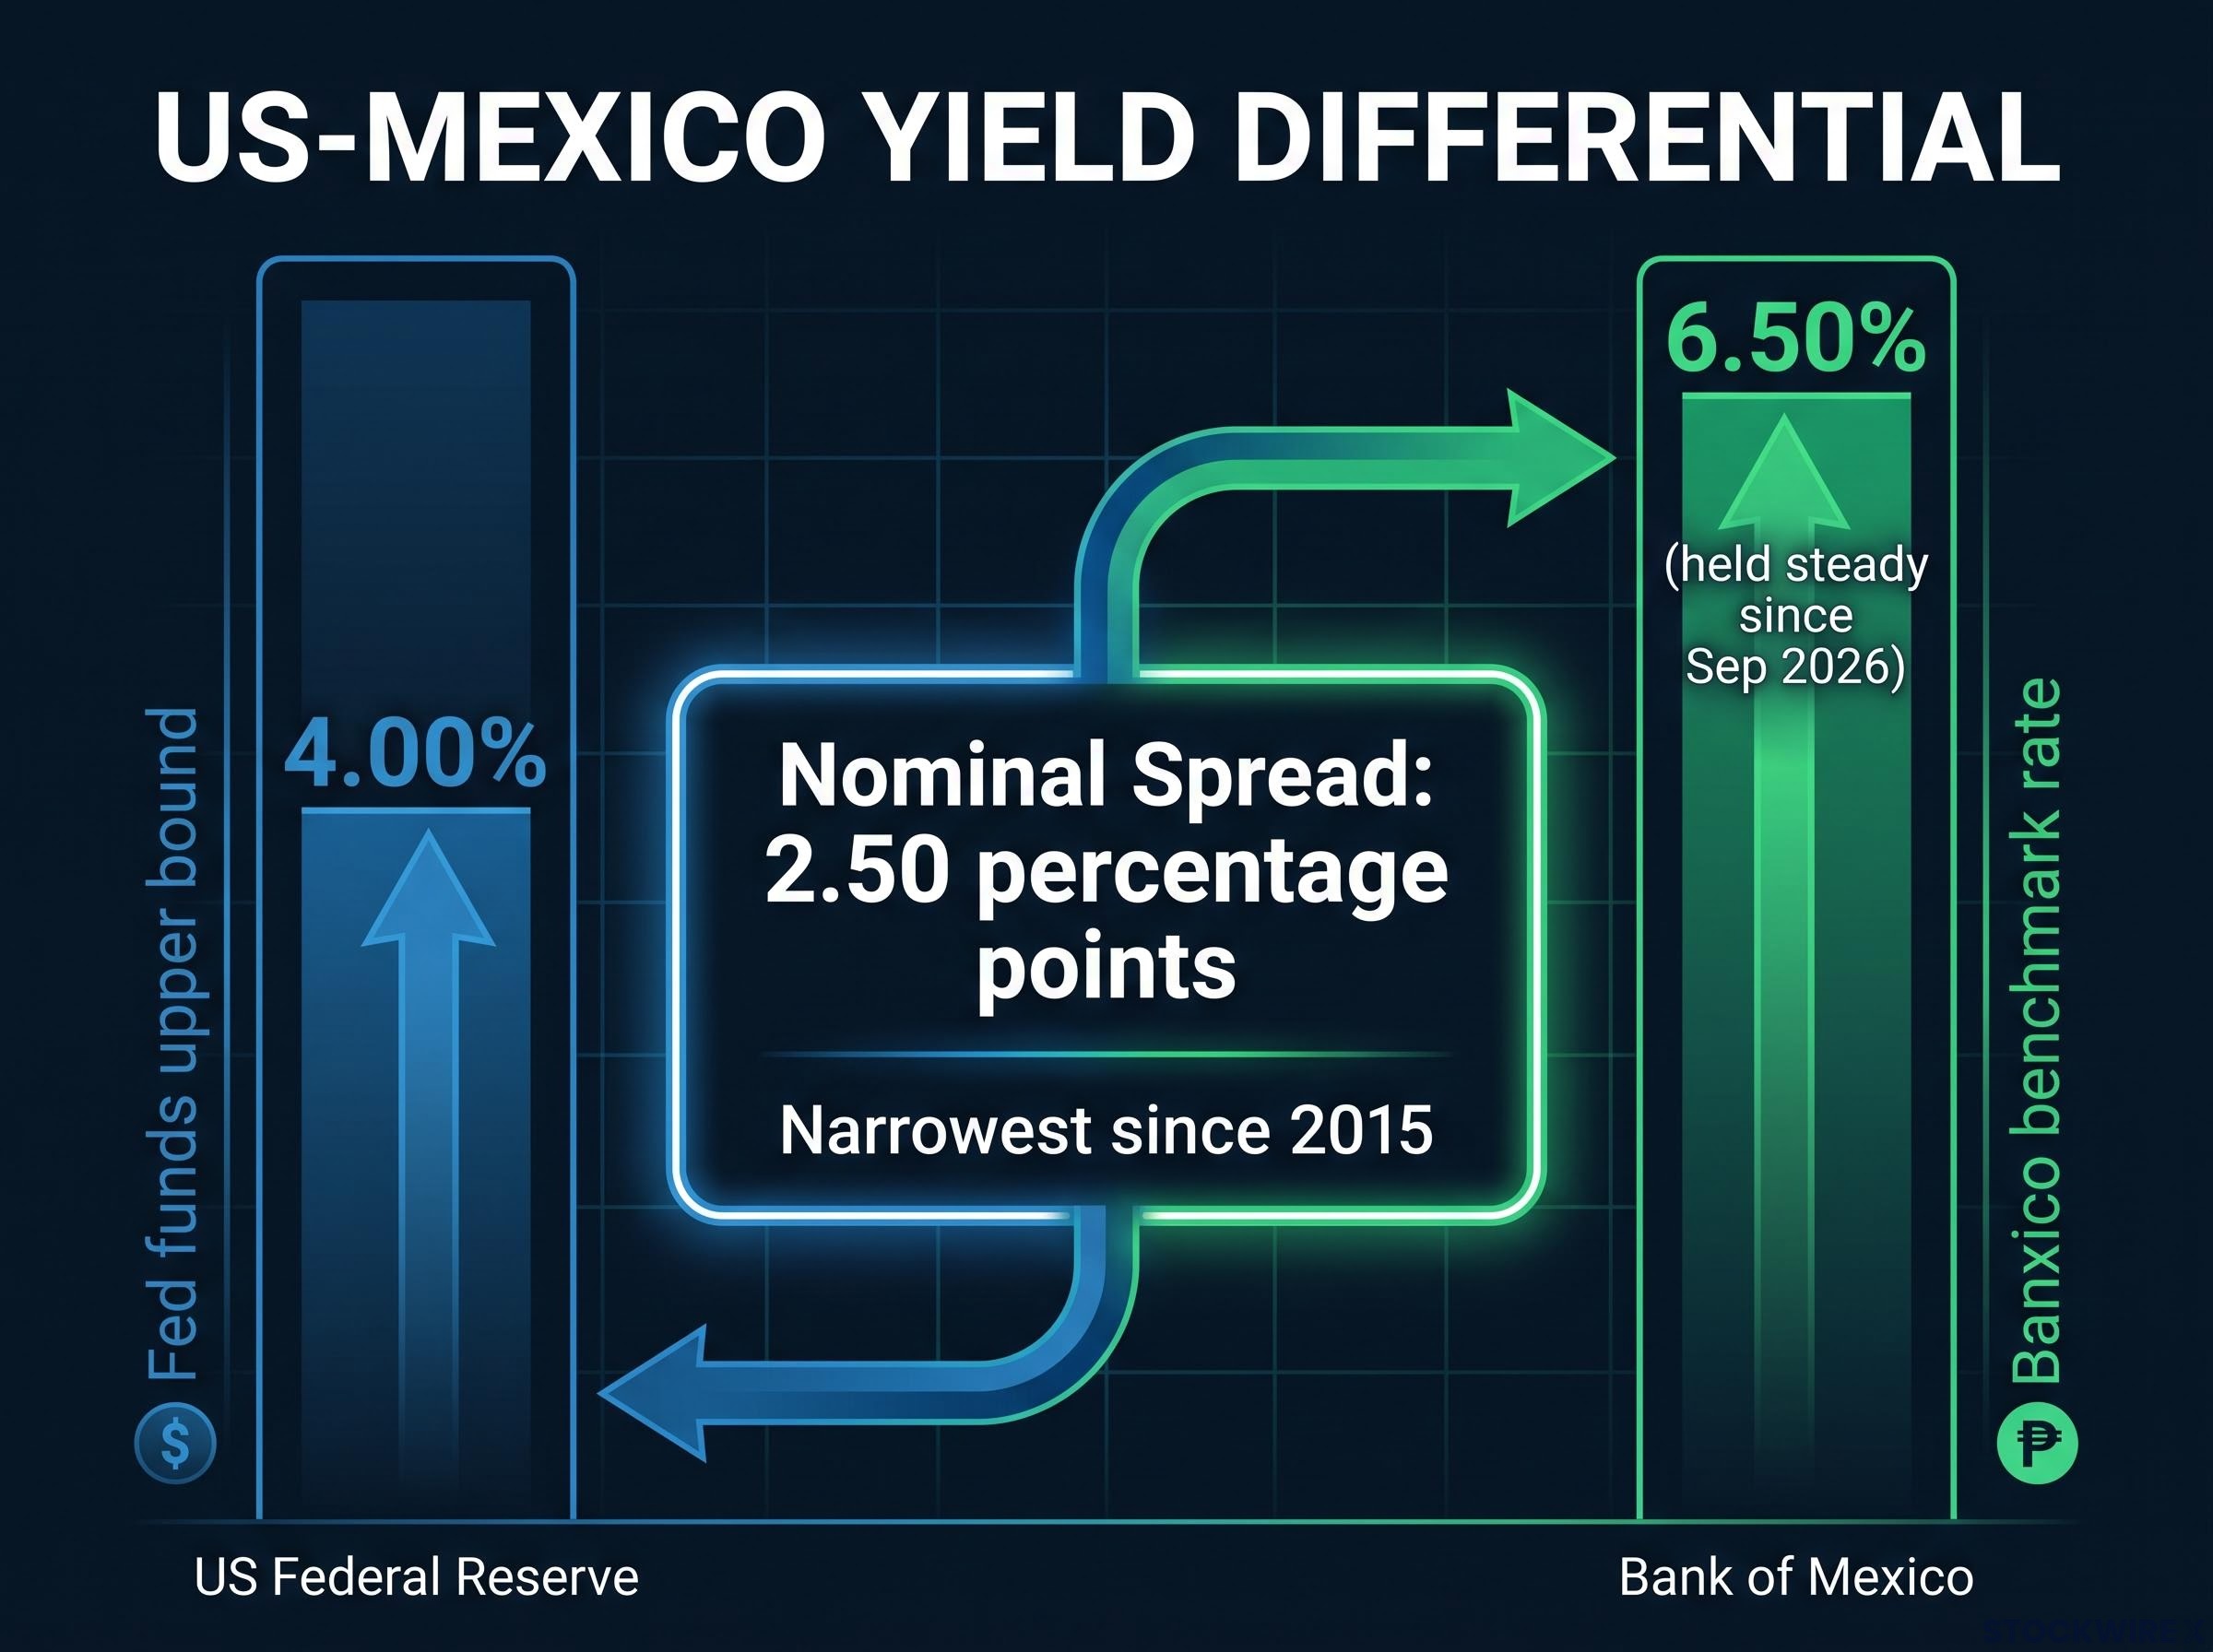
The first thing a carry trader looks at is a yield differential: the difference between what two currencies pay to hold them. Right now, that number for the US and Mexico is 2.50 percentage points, the gap between Banxico’s 6.50% and the Fed’s upper bound of 4.00%.
That single figure is the engine of the entire strategy.
A carry trade works like this. You borrow money in a currency with low interest rates, the US dollar in this case, and you invest it in a currency with higher interest rates, the Peso. You pocket the difference between what you pay to borrow and what you earn to invest. As long as the exchange rate stays stable, that spread is income.
This is not a niche or exotic manoeuvre. Carry trades are a mainstream institutional strategy, run by hedge funds and asset managers at scale, and the flows they generate move real money in and out of a currency through both spot and forward markets. When carry capital pours into the Peso, it props the currency up. When it leaves, the support goes with it.
Here is where the current numbers sit against their historical reference point.
| Measure | Current level | Historical context |
|---|---|---|
| Banxico benchmark rate | 6.50% | Held steady since Sep 2026 |
| Fed funds upper bound | 4.00% | Rising through tightening cycle |
| Nominal spread | 2.50 pp | Narrowest since 2015 |
The size of that spread is not just a number on a screen. It is the income the carry trader earns before the exchange rate moves at all, and when it shrinks, the basic arithmetic of the trade changes.
Why the Peso attracted carry capital
The Peso earned its status as a carry favourite through a specific combination of traits. It offered a meaningfully higher nominal policy rate than the dollar, which is the yield premium that carry traders chase in the first place.
It is also one of the more liquid emerging-market currencies, meaning large positions can be built and unwound without the trade moving the price against you. That liquidity, rare among emerging-market currencies, made the Peso practical at institutional scale.
Add Mexico’s proximity to the US economy and the perceived stability tied to the USMCA trade framework, and the Peso looked less risky than many of its emerging-market peers while paying more than the dollar. That is the package that drew global carry capital in.
The Peso is not a typical emerging-market currency: it absorbs global sentiment shocks independently of domestic fundamentals, and the full set of Mexican peso drivers operating across different time horizons matters for separating daily noise from genuine structural signals.
When big ASX news breaks, our subscribers know first
How the Fed’s tightening cycle is eroding the Peso’s yield advantage
The pressure on the Peso did not arrive all at once. It built through a sequence, and watching that sequence explains why the currency is weakening even with rates still in its favour.
The Fed has been raising rates. Banxico has been holding. Every time the Fed lifts its target while Mexico stays put, the gap between the two mechanically narrows, and with it the carry trader’s income.
Diverging central bank policy across the Fed, the Bank of Japan, and the Swiss National Bank has stretched the global rate map to a point where carry trades built on years of near-zero funding costs are running on a narrowing margin of safety, making the Peso’s compression part of a broader 2026 regime shift.
Then came the September US jobs report, and it reshaped the near-term picture.
US September nonfarm payrolls: 29,000 actual versus 90,000 consensus The prior reading had been 133,000. The unemployment rate rose to 4.2% from 4.1%.
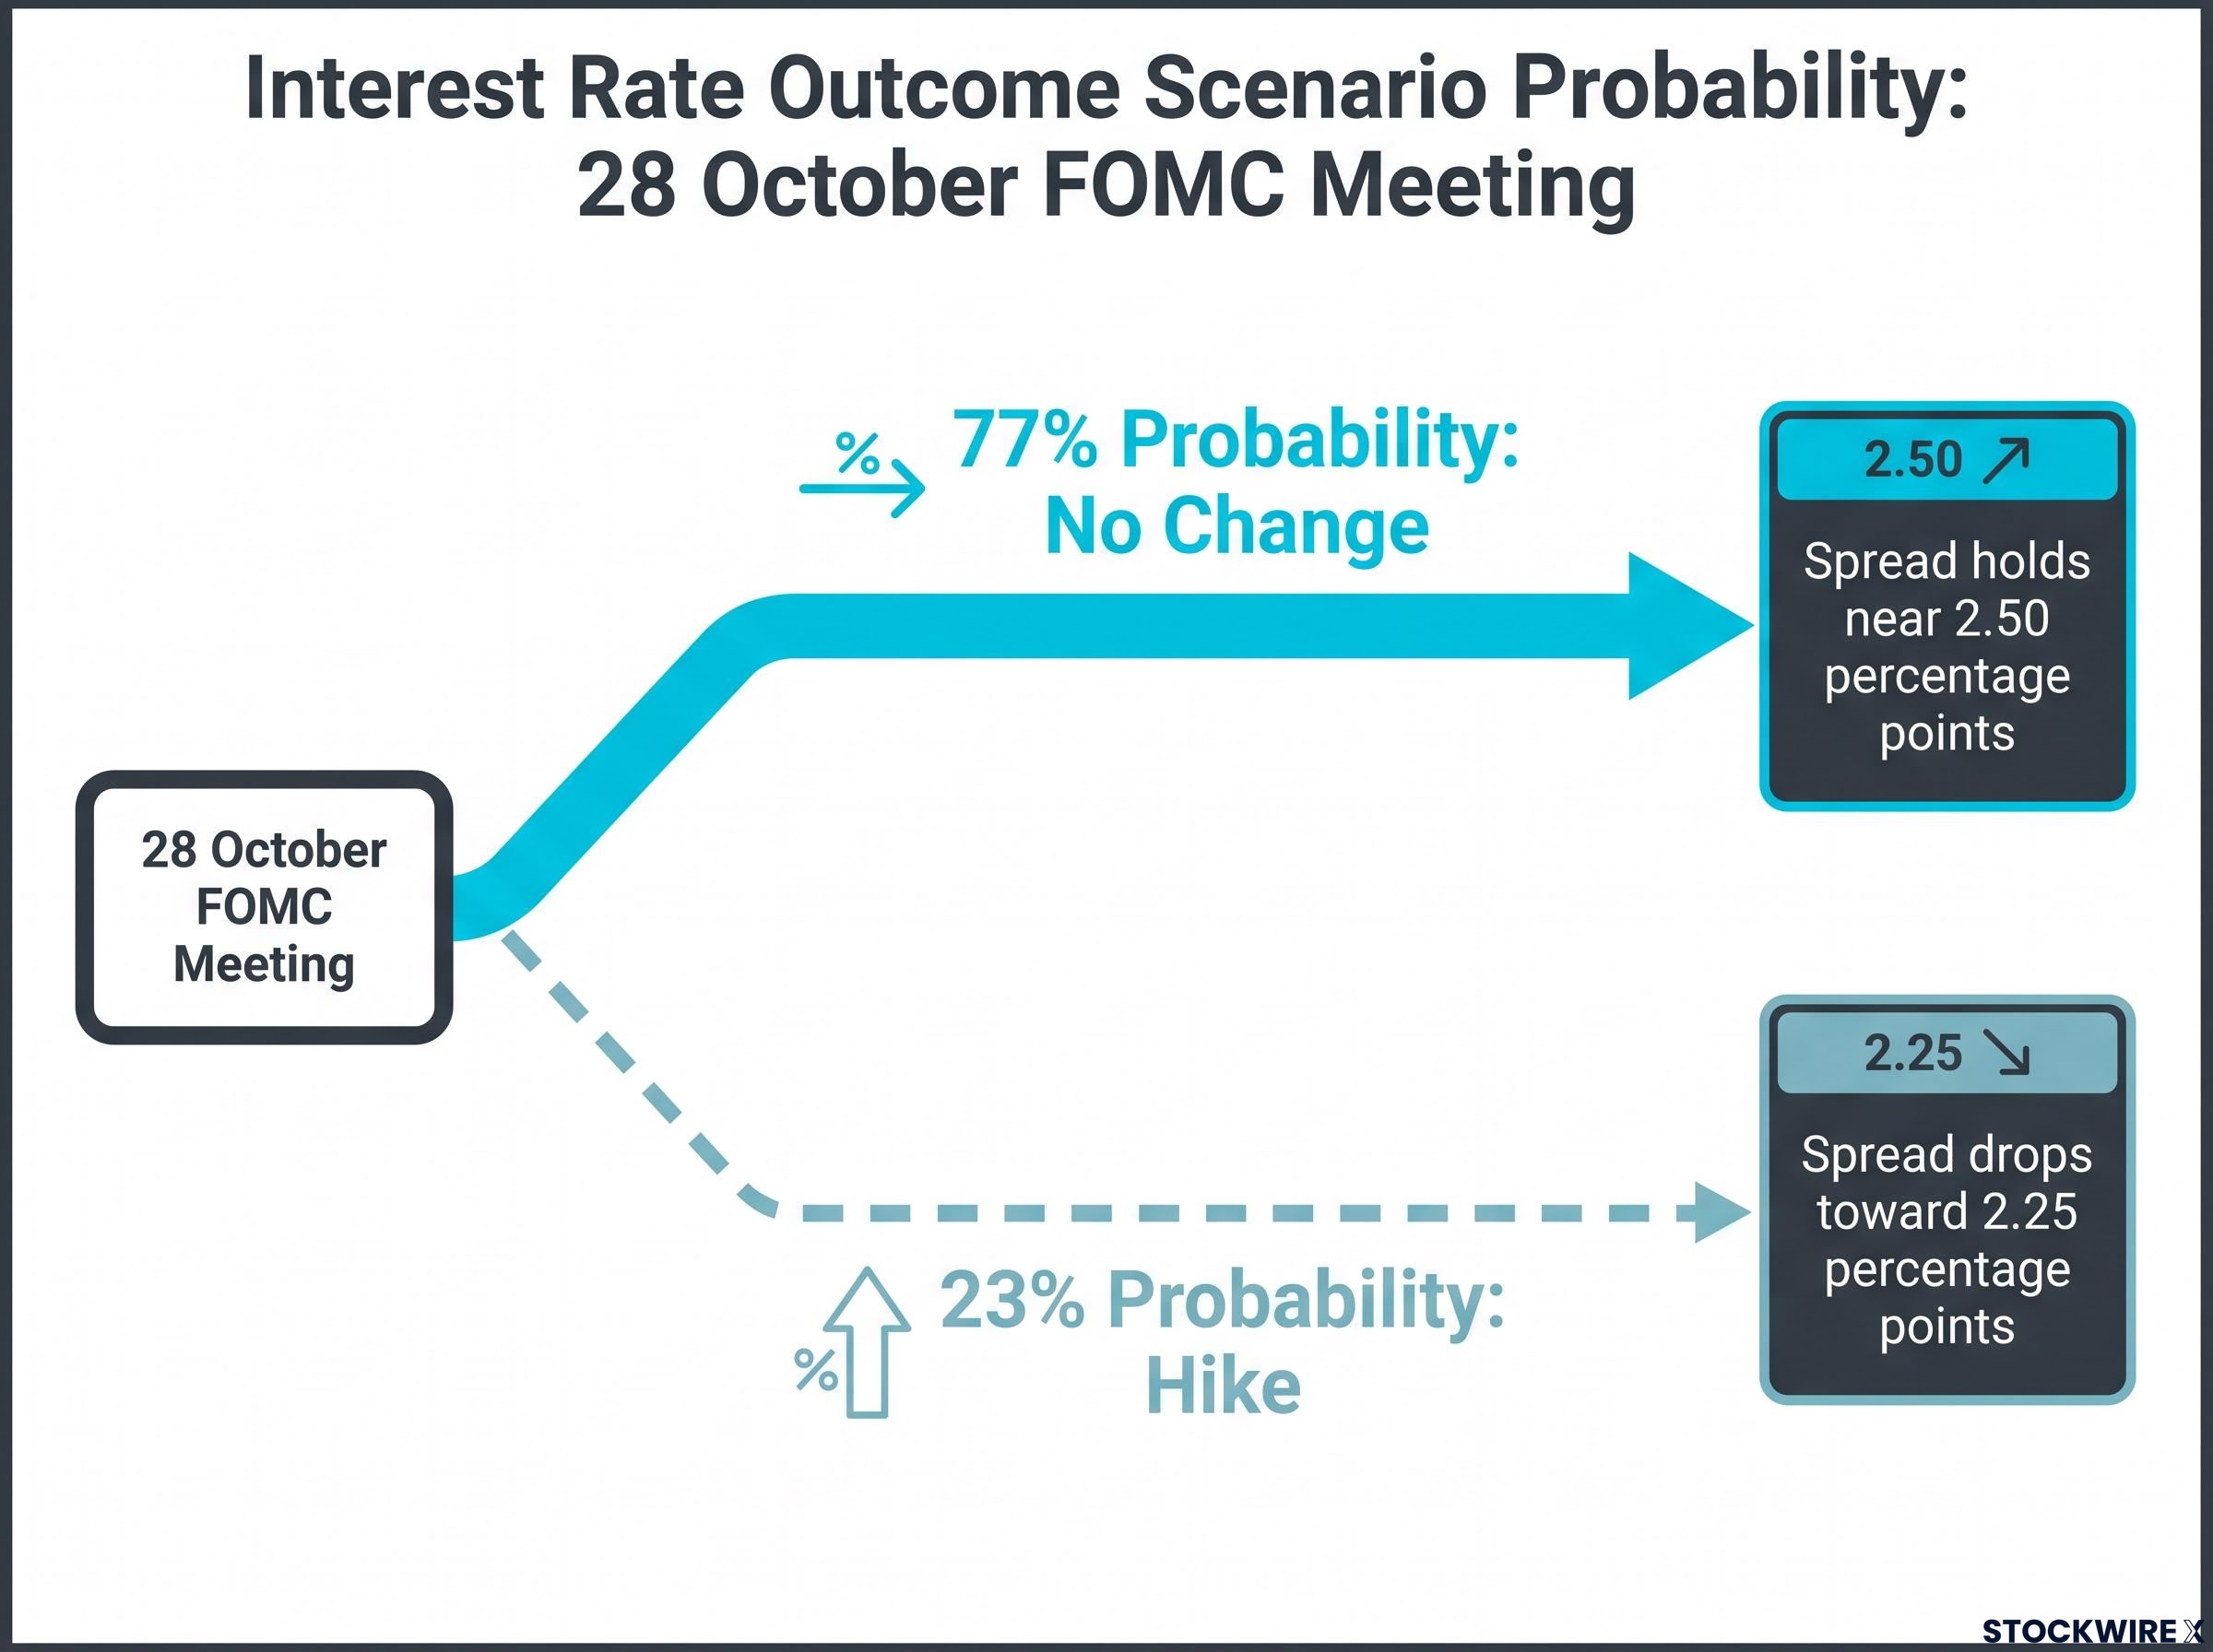
A print that weak softened the market’s expectations for another Fed hike. Dovish commentary from New York Fed President John Williams and Fed Vice Chair Philip Jefferson reinforced that shift. According to Prime Terminal data, the market-implied probability of a hike at the 28 October FOMC meeting sat at just 23%, with a 77% chance of no change.
Here is the asymmetry that matters. A weak jobs number slows the pace at which the spread compresses, but it does not reverse the trend. As long as the Fed’s rate is climbing toward Mexico’s while Banxico stays flat, the carry premium keeps eroding regardless of any single data point.
Three forces are compressing the differential right now:
- The Fed’s rate path, still biased higher over the cycle even after the soft September data
- Banxico’s expected hold at 6.50%, which fixes the Peso’s yield on one side of the equation
- The Peso’s roughly 3% weekly loss, the market already repricing the trade
What this tells you is that the Peso’s advantage is essentially locked on one side while the Fed keeps its options open on the other. That is the structural problem, and no single strong or weak data release changes it.
What the private economist surveys say about Banxico’s path
The expectation that Banxico stays on hold is not a guess. It is a durable consensus across the analyst community.
In the Citi Mexico Expectations Survey published on 23 September 2026, 25 of 36 analysis groups expected Banxico to leave its rate unchanged at 6.50% at the 24 September meeting. Most participants did not foresee any change until late 2027.
Earlier survey vintages tell the same story, with median forecasts of 6.50% for both end-2026 and end-2027. There is dispersion around that central case, with end-2026 estimates ranging from 6.25% to 6.75% and end-2027 estimates spanning 5.75% to 7.25%, but the central expectation has held steady. For the carry trader, that means the compressed differential is not a passing condition. It is the baseline for the next two years.
When carry trades unwind: what history tells carry traders
Carry trades rarely collapse without warning. They tend to unravel in a recognisable shape, and two episodes make that shape clear.
The first is the Japanese yen carry trade, which blew apart during the 2008 global financial crisis. Traders had borrowed at near-zero Japanese rates and invested in higher-yielding assets elsewhere. When risk sentiment turned, those leveraged positions reversed at speed, the yen surged, and carry traders absorbed heavy losses.
The 2024 yen carry trade unwind, the closest historical parallel to current Peso dynamics, resolved within weeks once 40-60% of speculative positioning cleared, confirming that episodic carry stress is real but systemic breakdown from a single currency’s reversal has not historically followed.
The second is the 2013 taper tantrum. The mere suggestion that the Fed might slow its bond buying was enough to narrow emerging-market yield advantages in relative terms. Capital rotated back toward dollar assets, and carry trades in the Brazilian real and Turkish lira reversed sharply.
The common thread is the trigger: a narrowing differential, or doubt about whether the yield premium still compensated for the risk. Once that doubt set in, the unwind followed a consistent order.
- Reduced inflows, as new carry capital stops arriving
- Slower or stalled currency appreciation, as the support thins
- Outright selling and FX weakness, as existing positions are closed
That sequence is the mental model to carry forward. The Peso’s recent 3% weekly loss is not an isolated shock. It looks like step one of a familiar progression.
How the current MXN setup maps onto the historical pattern
Lay the current Peso situation over that template and the fit is close. A roughly 3% weekly loss is consistent with early-stage reduced inflows and a shift in positioning, rather than a full-blown rout.
The narrowing nominal differential, combined with only modest FX appreciation expectations, is precisely the condition that preceded the 2013 reversals. As the Peso’s yield premium shrinks, it behaves less like a standout carry currency and more like a typical emerging-market name, which makes it more sensitive to broad risk-off selling across the asset class.
There is one detail that sharpens the risk. The consensus hold through 2027 means Banxico has no rate lever to pull if conditions sour, removing the very tool that has historically cushioned emerging-market currencies during Fed tightening cycles.
Beyond the carry trade: second-order effects of peso depreciation
A weaker Peso is not only a carry trader’s problem. It sets off feedback loops that reach the broader Mexican economy, and those loops are worth understanding even if you never run a currency position.
The three channels that matter most work like this:
- Inflation and Banxico’s flexibility: A weaker Peso raises the local-currency cost of imports, pushing inflation expectations higher and forcing Banxico to hold rates elevated for longer, even where domestic conditions might otherwise justify a cut.
- Nearshoring and trade competitiveness: Depreciation makes Mexican exports and labour cheaper in US-dollar terms, supporting foreign investment, but if the weakness stems from risk-off sentiment, financing costs for Mexican firms rise and offset part of that gain.
- Remittances and household income: US-dollar remittances buy more Pesos when the currency weakens, lifting household consumption, though imported inflation can quietly erode that benefit over time.
The inflation channel is the one that feeds directly back into policy. Banxico frames its stance around the short-term real ex-ante rate, which is the target interbank rate minus average 12-month inflation expectations. A weaker Peso that lifts those expectations forces Banxico to keep the nominal rate high to protect that real buffer, which limits its room to support growth.
That matters because the growth backdrop is already soft. The Citi survey of 23 September 2026 put Mexico’s 2026 GDP forecast at 1.4%, and the weak US payrolls print of 29,000 hints at softening external demand from Mexico’s largest trading partner.
Analysts cannot even agree on where the Peso lands, which underscores the uncertainty.
Conflicting Peso forecasts April Citi survey: USD/MXN at 18.3 (end-2026) and 18.9 (end-2027), implying mild depreciation. September Mexico Business News reference: 17.50 (end-2026) and 18.00 (end-2027), implying mild appreciation.
What this means for you is that the carry dynamic is self-reinforcing. Peso weakness feeds inflation, inflation ties Banxico’s hands, and tied hands keep the policy configuration locked in place. Everyone with exposure to the Mexican economy, not just FX desks, lives inside that loop.
What the narrowing gap means going forward
Pull the threads together and the Peso’s path does not come down to a single prediction. It comes down to three variables, and watching them tells you whether the carry premium keeps eroding or steadies.
- The Fed’s rate path: Watch whether the 23% October hike probability materialises. A hike drops the spread toward 2.25 percentage points; a pause holds it near 2.50.
- Banxico’s policy flexibility: Watch whether the bank can hold at 6.50% without the domestic economy, already forecast to grow just 1.4% in 2026, forcing its hand.
- Global risk sentiment: Watch broad emerging-market flows. A risk-off turn could accelerate a correlated carry unwind faster than the rate gap alone would suggest.
The consensus hold through late 2027 is a double-edged thing. It makes the carry premium predictable, which is a form of stability, but it also means there is no rate lever left if conditions deteriorate, and any further Fed hike directly compresses the spread.
Which brings the story back to its opening paradox. The Peso is under pressure not because Mexican rates are low, but because the gap that made it distinctive is shrinking. At roughly 2.50 percentage points, falling toward 2.25 with one more Fed move, the risk-adjusted case for Peso carry is materially weaker than it was when the differential was wide. The specific signal to watch is simple: if the Fed hikes and the spread narrows to 2.25, expect the pressure to intensify; if the Fed pauses and the spread holds near 2.50, the premium stabilises but does not recover.
Investors exploring how carry mechanics play out across different currency pairs will find our full explainer on the Canadian dollar carry trade useful, as it covers the specific carry-to-volatility metrics TD Securities uses to identify when a funding currency thesis begins to expire.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and financial projections are subject to market conditions and various risk factors.