Chip stocks have become cheaper even as the fundamentals behind them have strengthened, and Mizuho’s Jordan Klein is on record saying most investors are not positioned for what comes next.
Investor positioning across the semiconductor sector has pulled back sharply from its summer highs, while memory supply conditions have tightened to a degree not seen in roughly 15 years. That has opened a gap between where sentiment sits and where the underlying cycle is heading.
Klein, a TMT specialist at Mizuho, characterised that gap as a near-term entry point in a note published on 1 October 2026, following Micron’s record quarterly results.
This piece unpacks the specific logic behind that call, the memory supply data underpinning it, and the two sub-sectors where Mizuho sees the most compelling near-term additions. After reading, you will have the framework to judge whether current chip equity valuations reflect the cycle or are lagging behind it.
Why Mizuho thinks the market is pricing chip stocks like the cycle has already peaked
Here is the tension at the centre of Klein’s thesis. Positioning has retreated while fundamentals have advanced, and those two things rarely move in opposite directions for long.
Semiconductor sector positioning tells a counterintuitive story in 2026: the SOX posted its strongest first-half performance on record before pulling back more than 20% from its peak, producing a situation where the same stocks are simultaneously at year-to-date gains above 60% and in a technical bear market, which is precisely the kind of split-signal environment that generates the sentiment-versus-fundamentals gaps Klein is describing.
Klein’s core argument is that investor exposure to the sector has fallen considerably from the levels seen over the summer, even as the supply and earnings picture has improved. In his reading, that combination is exactly the setup that produces attractive entry points, because sentiment has sold down a story that the data is still building.
He pointed to the daily volatility between chip and software equities and attributed it to flows, not fundamentals. Quantitative, passive, and systematic vehicles are moving these names day to day, Klein argued, not any genuine shift in the earnings or supply outlook.
Nearly all chip equities, with the exception of Astera Labs, are inexpensive relative to their growth trajectories, according to Klein.
For you, the practical read is this: the noise in daily chip prices carries less signal than it appears to. If the swings are driven by mechanical fund flows rather than fundamentals, then filtering them out is not complacency. It is the correct way to see the cycle underneath.
What Micron’s record quarter actually signals to analysts
Klein did not treat Micron’s earnings as a transformative moment. He framed them as confirming rather than catalytic.
Those already constructive on memory and AI themes stayed constructive. Sceptics were unlikely to shift. The print hardened conviction without moving anyone’s starting position.
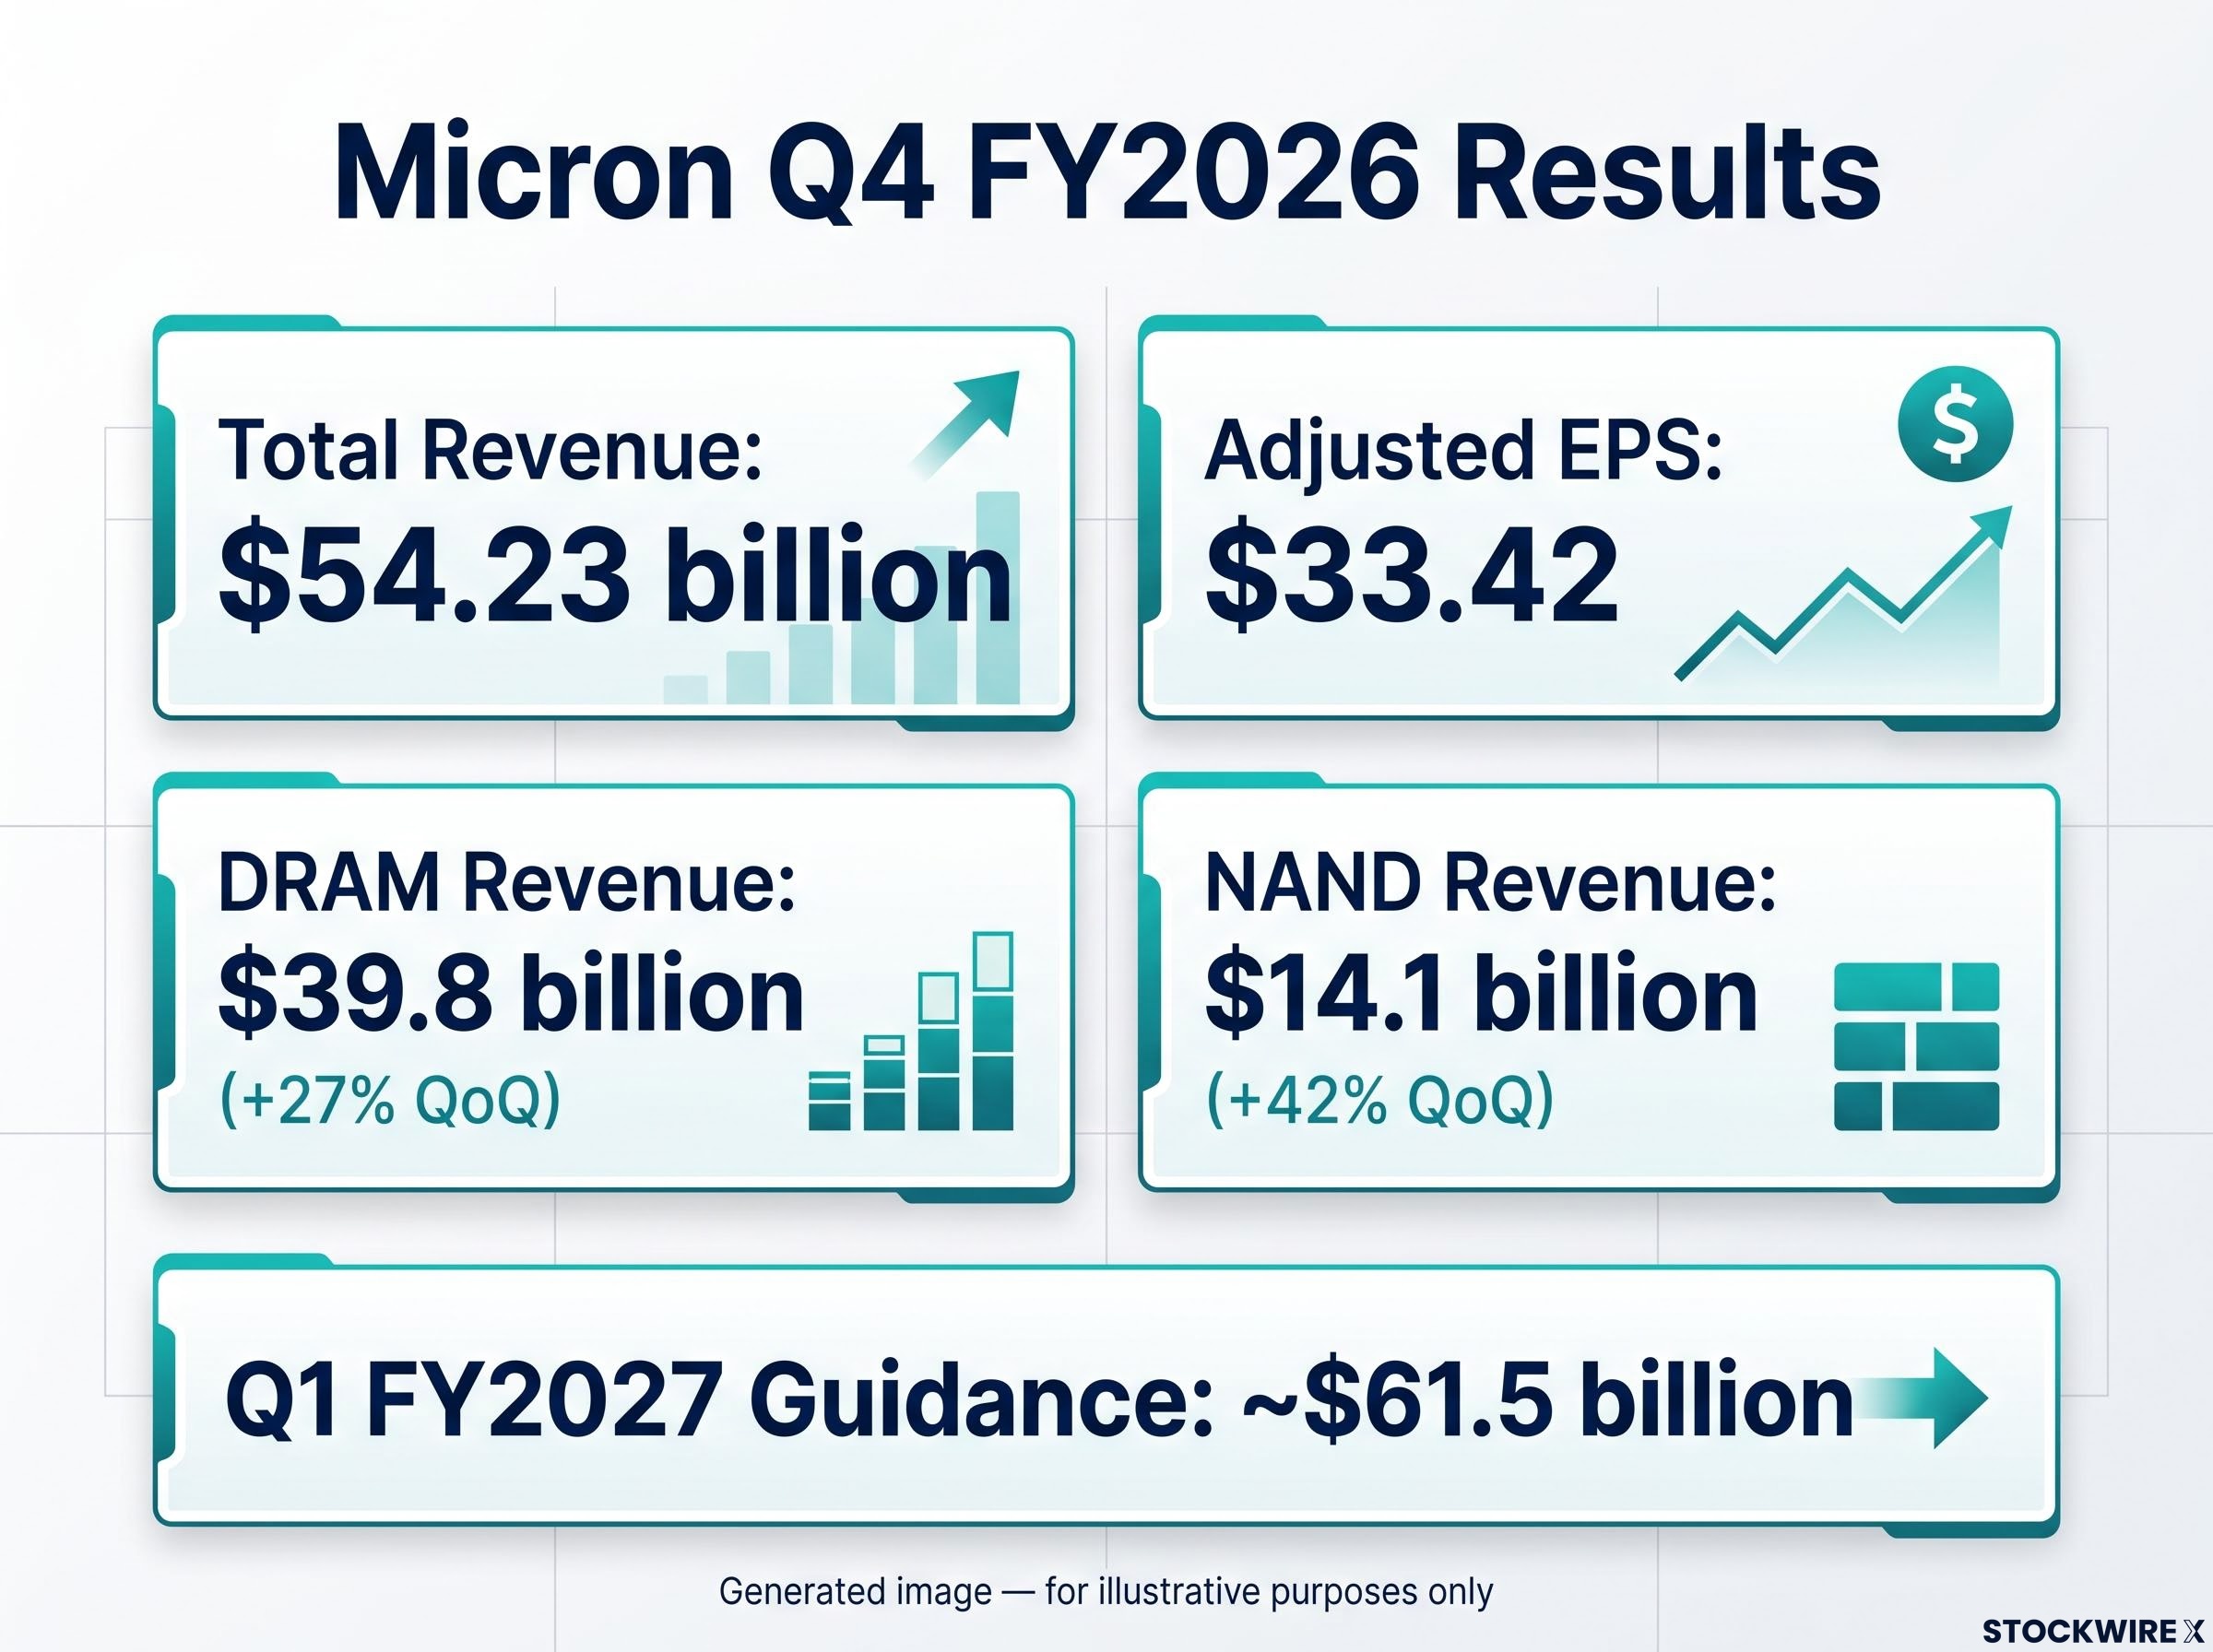
Micron reported fiscal Q4 2026 revenue of approximately $54.23 billion, above consensus of roughly $50-51 billion, with adjusted earnings of about $33.42 per share. Guidance for Q1 FY2027 came in at approximately $61.5 billion, plus or minus $1.5 billion.
The headline beat was not the point, though. Klein’s primary takeaway was the supply commentary, which is where the real thesis lives, and that sets up the next question: how tight is supply, really?
When big ASX news breaks, our subscribers know first
The memory shortage is the most severe in 15 years, and the data backs that claim
Start with the scale. Research firm NAND Research cites Goldman Sachs quantifying the 2026 memory shortfall as the most severe in roughly 15 years, with a global DRAM deficit of 4.9%, NAND at 4.2%, and high-bandwidth memory (HBM) at 5.1%. All three are described as the largest deficits since 2011.
DRAM supply constraints extend well beyond Micron’s own commentary: SK Hynix has publicly projected a global shortage lasting through 2030, with HBM inventory sitting at just 3-4 weeks industry-wide, a timeline that reinforces rather than undermines the multi-year window Klein is describing.
Those are not abstract projections. They are already showing up in the prices enterprise buyers pay.
NAND Research reports that DRAM contract prices climbed 90-95% quarter-over-quarter in Q1 2026, with a further 58-63% rise projected for Q2 2026. NAND flash contract prices were set to rise 70-75% quarter-over-quarter in Q2 2026, outpacing DRAM for the first time this cycle.
Micron’s own numbers echo the trend. DRAM revenue grew 27% quarter-over-quarter to approximately $39.8 billion in Q4 FY2026, with average selling prices up by the high teens. NAND revenue rose 42% to roughly $14.1 billion, with selling prices up around 30%.
Here is the same picture assembled in one place.
| Segment | 2026 Global Deficit | Q1 2026 Contract Price Change | Q2 2026 Contract Price Change (projected) | QoQ ASP Change (Q4 FY2026) |
|---|---|---|---|---|
| DRAM | 4.9% | +90-95% | +58-63% | High teens % |
| NAND | 4.2% | Not specified | +70-75% | ~30% |
| HBM | 5.1% | Not specified | Not specified | Not specified |
The management view extends the tightness forward. On Micron’s Q4 call, CEO Sanjay Mehrotra projected that memory demand would exceed supply in 2027 and 2028.
In 2027 and 2028, demand is expected to exceed supply, with the balance even tighter than this year, Mehrotra said.
Why can’t new capacity simply close the gap? Because the timeline does not allow it. NAND Research expects meaningful new fab volume to arrive no earlier than late 2027 or 2028, which leaves a multi-year window where bit demand growth outruns supply.
That window is reinforced by discipline on the supply side. SK Hynix, Samsung, Kioxia, and Micron all cut NAND production in the second half of 2025, with SK Hynix trimming output by roughly 10%, and Micron now expects its 2026 bit shipment growth to track the industry rather than lead it.
For you, the distinction that matters is this: a 15-year severity benchmark backed by contract price moves in the 60-95% range is not a forecast you can argue away. It is a shortage already settled in the transaction prices buyers are paying today.
Where Mizuho is telling investors to add exposure right now
This is where the macro case narrows into a decision. Klein named semiconductor equipment producers and analog chipmakers as the lowest-ownership areas in the entire sector.
Low ownership, in his framing, is an opportunity rather than a warning. In a sector where consensus positioning has already retreated, the least-owned pockets are precisely where professional money has the furthest distance to travel before it even reaches a neutral weight.
The recommended action splits by urgency. Klein advised increasing holdings in equipment-related names near-term, and taking a more selective, measured approach to analog chipmaker exposure.
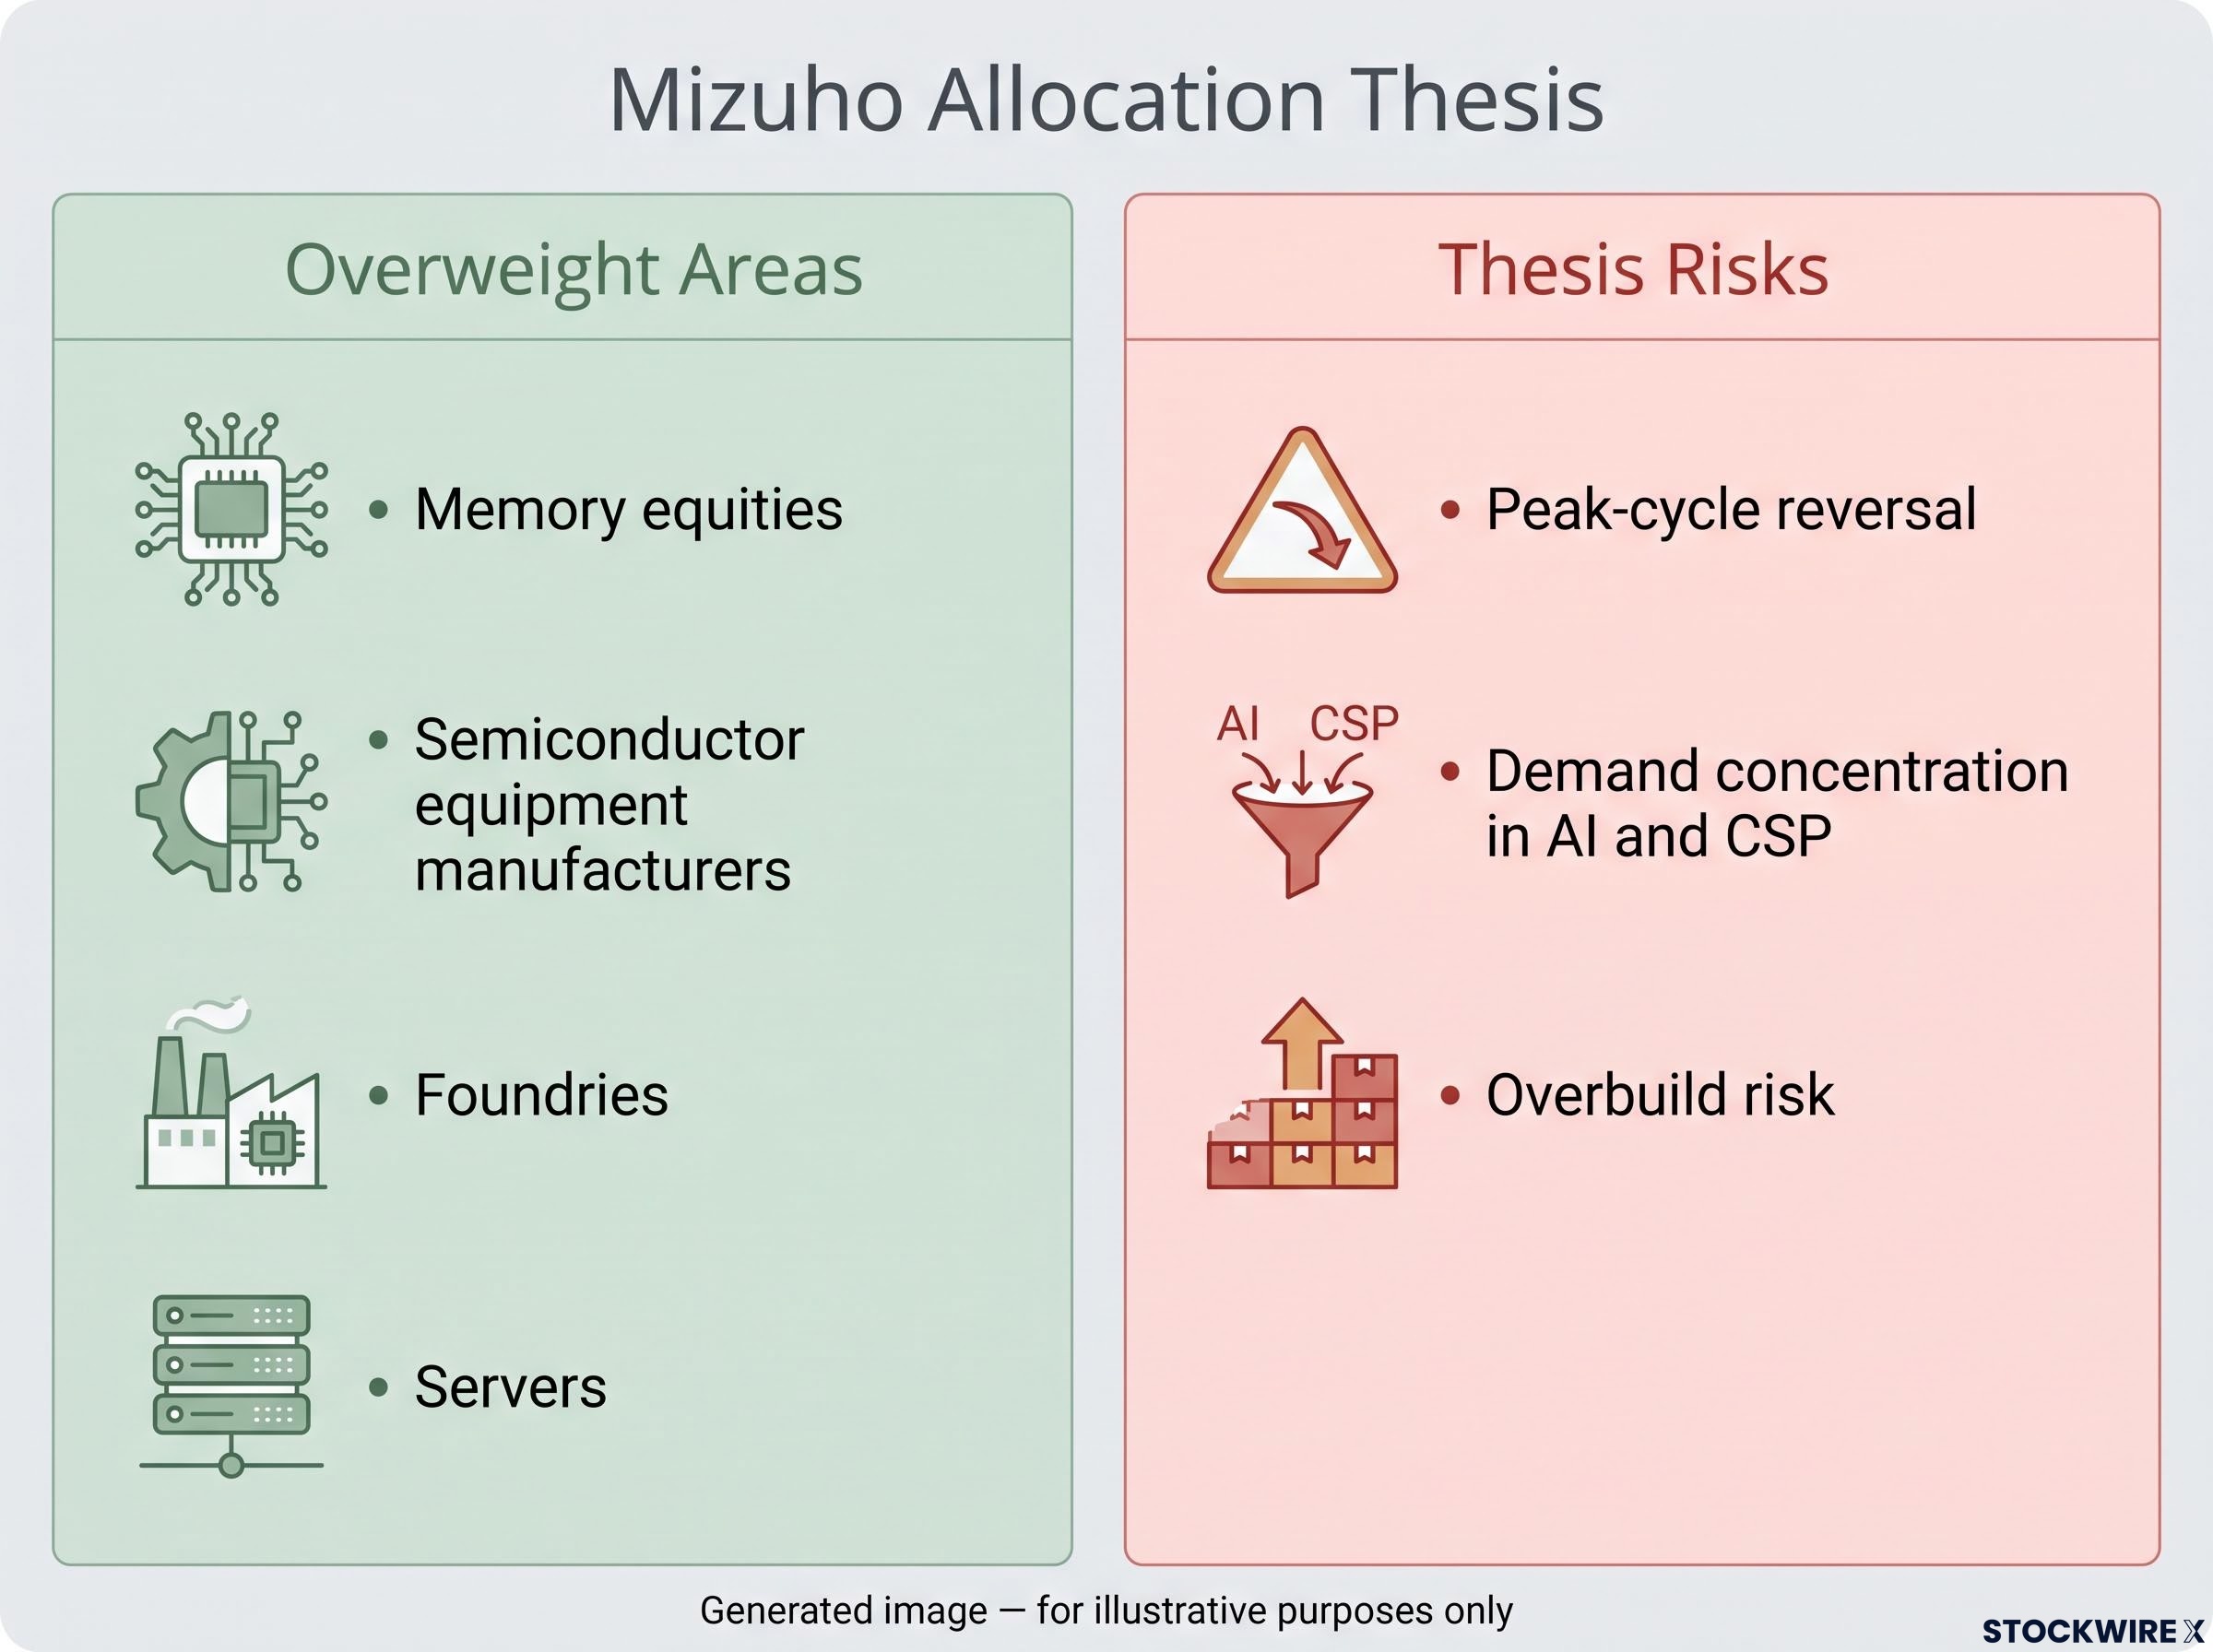
His broader overweight stretched across four areas.
- Memory equities
- Semiconductor equipment manufacturers
- Foundries
- Servers
The server leg has its own demand support. Micron management expects server shipments to grow in the high-teens percentage range in both 2026 and 2027, with free cash flow generation for memory stocks characterised as poised for significant acceleration.
The equipment and foundry thesis as a lagged play on capacity build
The equipment case rests on second-order logic. Elevated memory pricing supports strong manufacturer cash flows, and those cash flows eventually convert into capital expenditure budgets for new fabs and technology transitions.
Equipment vendors benefit later in that sequence, when cash-flush memory makers begin approving greenfield capacity. NAND Research’s view that meaningful new capacity is deferred to late 2027 or 2028 implies a multi-year runway before expansion-driven orders arrive in volume.
Equipment and memory divergence is a structural feature of every semiconductor cycle, not an anomaly: Bernstein documents that the two sub-sectors correlated at just 0.4 between 2012 and 2018, with equipment outperforming memory by as much as 49 percentage points across a single cycle window, a pattern driven entirely by the timing gap between capex commitments and memory price peaks.
That delay is what makes the current period a potential early-entry window for you. The scale implied by the DRAM, NAND, and HBM deficits could generate a substantial equipment upcycle once those expansion projects are approved, even if the precise timing remains open.
What could break the thesis, and how much weight to give each risk
A coherent bullish case is most useful when you also know the conditions under which it fails. Three named risks sit against the Mizuho view.
- Peak-cycle reversal: Some market participants fear the current price spikes and shortages mark a cyclical high point that eventually reverses as capacity is added and demand normalises.
- Demand concentration in AI and CSP: The cycle leans heavily on cloud service providers and AI workloads, so any digestion phase in enterprise capital expenditure could hit memory fundamentals harder than a broader demand base would.
- Overbuild risk: The manufacturers willing to cut supply aggressively are the same ones capable of overbuilding to chase the deficit, which is the historical trigger for memory downturns.
The demand concentration point is already visible in the data. TrendForce’s Q4 2026 forecast notes that weak consumer demand is narrowing gains in some segments even as CSP demand stays robust, which tells you how much of this cycle depends on a single buyer category.
The overbuild risk is not hypothetical either. Samsung, SK Hynix, Kioxia, and Micron all demonstrated their willingness to swing production hard in the second half of 2025, and that same capability can run in reverse.
Even the bullish camp concedes the uncertainty.
For investors wanting to stress-test Klein’s positioning call against a second major bank’s analysis, our full explainer on BofA’s chip selloff framework details the 18% SOX underperformance threshold that distinguishes recoverable trade-shock episodes from full cyclical busts, including the three named falsification conditions BofA uses to monitor regime change.
It is hard to gauge when supply and demand will regain balance, Mehrotra said.
The purpose here is not to undercut the thesis but to hand you the counter-indicators. A sustained decline in CSP capital expenditure commitments, an unexpected acceleration in fab approvals, or a reversal in contract pricing would each warrant a genuine reassessment rather than a reflexive dismissal.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and financial projections are subject to market conditions and various risk factors.
Reading the cycle as it stands today, not as it was priced three months ago
The article has built toward one central tension: the positioning data and the fundamentals are pointing in opposite directions. Klein’s call is that the fundamentals resolve the gap upward, with free cash flow acceleration for memory stocks as the mechanism linking today’s tight supply to tomorrow’s investor returns.
Your decision is not whether to accept or reject the Mizuho thesis wholesale. It is which parts of the case you find most durable, and which of the three named risks you are willing to carry.
Three forward variables will decide whether the supply outlook holds.
- CSP capital expenditure trends, since any pullback would strike the cycle’s most concentrated demand source.
- Monthly contract pricing updates from TrendForce and NAND Research, which show whether the shortage is still pricing through in real terms.
- Fab approval announcements from Samsung or SK Hynix, which would signal that the late 2027 or 2028 capacity ceiling is moving.
The nearest test arrives with Micron’s Q1 FY2027 results against the $61.5 billion guidance. Watch those three inputs over the next two quarters, and you will be positioned to judge the thesis as new data lands, rather than accepting it on authority.