Copper is trading near $14,545 per tonne, and Deutsche Bank thinks it is heading to $22,050. That is a rally of roughly 50%, and the bank expects it to land by the second quarter of 2027.
What makes this call so striking is not the size of the number. It is the reasoning behind it.
Deutsche Bank frames the current setup not as a demand boom but as a liquidity crisis. Immediately deliverable copper has fallen to what the bank calls unprecedented lows, and aggressive stockpiling by the United States and China has drained the cushion of metal that normally absorbs shocks.
That distinction matters. A demand-led rally builds slowly. A liquidity squeeze can spike violently, because there is simply no spare metal to plug a gap.
For investors holding commodity-linked equities, this is a setup that creates extreme price sensitivity. Small disruptions can produce outsized moves.
This copper price forecast rewards a closer look. The sections below break down the mechanics behind Deutsche Bank’s target, the structural supply gap that props up the floor, the industrial limits of aluminium substitution, and how to evaluate heavily exposed miners like BHP.
The liquidity crisis driving Deutsche Bank’s price target
The forecast comes from Daniel Ghali, head of metals research at Deutsche Bank. His projection is specific: copper reaching $22,050 per metric ton, roughly $10 per pound, by Q2 2027.
Set against the LME cash settlement of around $14,545 per tonne on 28 September 2026, that is an increase of approximately 50% in about six months.
The engine behind the call is not booming factory orders. It is the collapse of deliverable inventory.
London Metal Exchange (LME) warehouse stocks sat at roughly 251,350 to 251,500 tonnes on 28 September 2026. That looks like a mid-range figure historically, but Ghali’s argument is that it cannot absorb what is being thrown at it. Simultaneous stockpiling by the US and China is soaking up available metal faster than the market can replace it, squeezing supply away from every other buyer.
Copper’s all-time high above USD 14,700 per tonne, set on 8 September 2026, was itself the product of two simultaneous shocks: US Section 232 tariff front-running and a Chilean winter storm that cut roughly 1.6 million tonnes of annualised production capacity, adding a supply-side dimension to the liquidity squeeze Deutsche Bank now describes.
Strategic mineral stockpiling has become an increasingly coordinated policy instrument, with both the US and China treating physical copper reserves as a national security asset rather than a purely commercial buffer, which is precisely the dynamic compressing deliverable inventory in the current cycle.
Deutsche Bank’s framing The bank describes the current environment as a “historic metal scramble,” a race to secure physical copper against critically thin deliverable stocks, where even a modest supply shock could trigger outsized price moves.
Here is what that tells you about your own exposure. When the market runs this thin, price does not need strong demand growth to jump. It only needs a single disruption, a strike, a smelter outage, a shipping delay, to send prices sharply higher, because there is no inventory buffer to absorb it.
This is also why Deutsche Bank does not expect the pressure to release quickly. The bank projects an average copper price of $20,900 per ton in 2027 and $18,500 per ton in 2028, meaning elevated prices well beyond the initial peak.
| Reference point | Price per tonne | Period |
|---|---|---|
| LME spot (cash settlement) | ~$14,545 | 28 September 2026 |
| Deutsche Bank peak target | $22,050 | Q2 2027 |
| Projected average | $20,900 | Full-year 2027 |
| Projected average | $18,500 | Full-year 2028 |
The read here is straightforward. This is a forecast built on scarcity of metal in the warehouse, not scarcity of factories wanting it. That changes both the speed and the volatility you should expect.
When big ASX news breaks, our subscribers know first
Why the structural supply gap is widening
A liquidity squeeze explains the near-term spike. But it sits on top of a slower, deeper problem: the world is struggling to grow copper supply at all.
Two forces are pulling in opposite directions. On one side, electrification demand is rising structurally. Copper runs through power grids, transformers, wind turbines, solar inverters, electric vehicle motors, and charging infrastructure, so every step toward decarbonisation pulls in more of it.
On the other side, supply cannot respond quickly, no matter how attractive the price. New copper simply cannot be willed into existence.
The clearest illustration is lead time. According to Wood Mackenzie, CRU, and major bank commodity desks, a new large-scale copper mine can take 10 to 15 years to move from discovery to first production. That gap between an immediate need for metal and a decade-long path to supplying it is the heart of the problem.
Several bottlenecks reinforce it:
- Permitting delays, particularly in jurisdictions with stringent environmental rules or strong community opposition, which can stall or cap expansions for years.
- ESG and social licence constraints, including water usage concerns in Andean countries, that make new projects slower and costlier to approve.
- Declining ore grades at incumbent tier-one deposits in Chile, Peru, and parts of the US, which raise unit costs and slow production growth even with heavy sustaining investment.
Empty out those grades and the economics shift for the whole industry. When the richest ore is already mined, producers spend more to extract less, lifting the cost floor across every operation.
There is broad consensus here. The International Energy Agency (IEA) and Wood Mackenzie both point to a mismatch between decarbonisation pathways and the copper capacity currently committed, arguing demand growth outpaces the mine pipeline even under conservative scenarios.
The 2026 refined copper deficit provides independent confirmation of the supply constraints Deutsche Bank describes: UBS projects a shortfall of approximately 520,000 metric tonnes, more than double the 2025 figure, driven by three simultaneous supply failures including the Grasberg force majeure and China’s sulphuric acid export halt.
For your broader materials portfolio, this structural deficit is the important signal. It means the price floor is supported by long-term energy transition needs, offering a macro tailwind that persists regardless of short-term volatility. Daily noise is one thing; a multi-year supply gap is what actually moves valuation multiples in the mining sector.
The physical limits of aluminium substitution
A 50% price surge does not go unanswered. High prices invite demand destruction and material substitution, and the obvious candidate is aluminium, cheaper, lighter, and already used in plenty of electrical applications.
The question is how far substitution can actually go. Here the story shifts from economics to engineering, and engineering imposes hard limits.
Where substitution works and where it fails
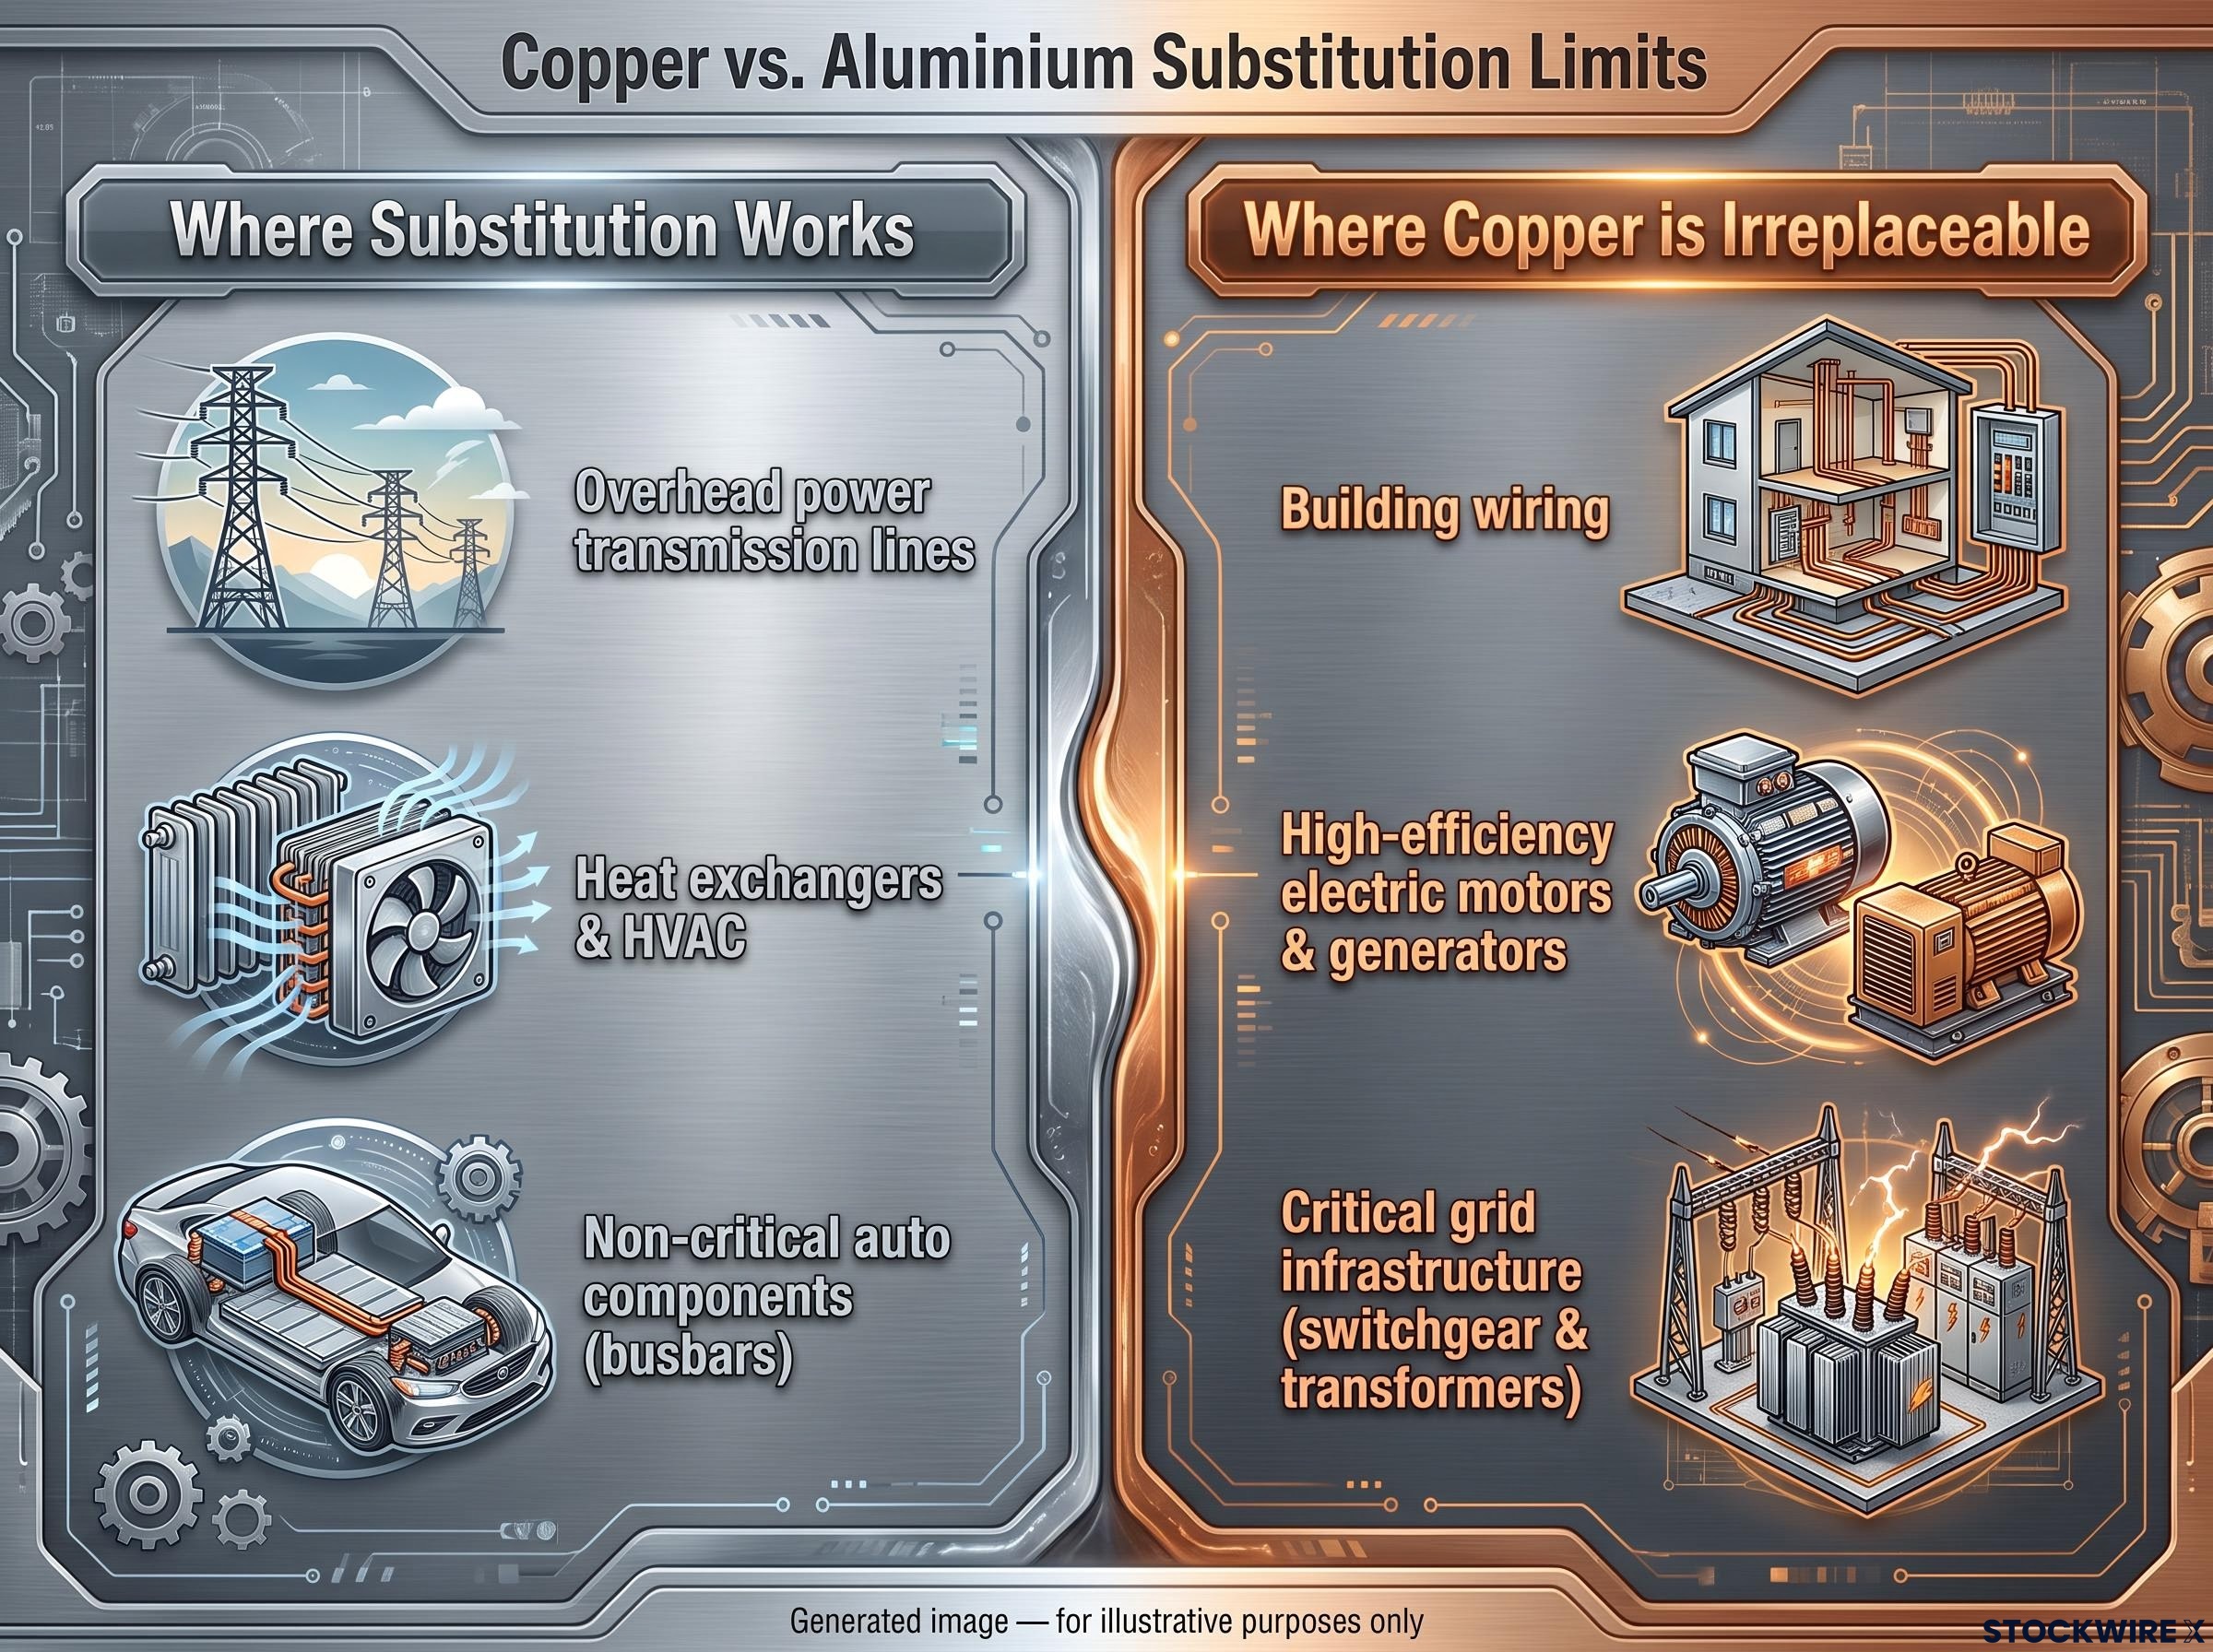
In some applications, aluminium is already the incumbent. Overhead power transmission lines widely use aluminium, typically alloyed and steel-reinforced, because its lower weight and cost outweigh its lower conductivity over long spans. Certain heat exchangers and HVAC components, such as radiators and condensers, also use aluminium, and designers can shift further toward it when copper prices climb, accepting modest efficiency trade-offs.
Some automotive components follow the same logic. For non-critical electrical parts, busbars, and housings, aluminium can be engineered to perform adequately, especially where weight savings carry value.
Then there are the applications where copper is effectively irreplaceable.
Building wiring is the clearest example. Copper’s superior conductivity, reliability, and safety profile mean many building codes still strongly favour it for internal wiring, and aluminium alternatives require thicker gauge and more exacting installation to manage fire and connection-degradation risks.
High-efficiency electric motors and generators are another. Copper windings are central to performance, and swapping in aluminium generally compromises efficiency and power density, a real problem in EV traction motors and high-performance industrial drives.
Critical grid infrastructure completes the picture. For switchgear, transformers, and high-stress conductive components, copper’s properties and long-term reliability sharply reduce any appetite to substitute.
The timing point is the one investors most often miss. Redesigning products around aluminium, changing connector design, corrosion protection, and thermal management, takes significant time and capital. Substitution is a partial relief valve, not an instant switch that can rebalance a sudden squeeze.
What this means for your copper-exposed holdings is reassuring. Copper demand is highly insulated from pure price shocks in exactly the applications that matter most for electrification, so the metal is not easily displaced by a cheaper alternative when prices spike.
Translating the copper squeeze into equity positioning via BHP
A commodity thesis is only useful if you can express it. For most investors, that means equities, and among the diversified majors, BHP has positioned itself squarely to capture a copper upcycle while cushioning some of the downside.
The revenue mix tells the story. On FY2025 figures (the financial year ended 30 June 2025), BHP generated copper revenue of US$22.5 billion, roughly 44% of total group revenue of US$51.3 billion. That is near-parity with iron ore, which brought in around US$23 billion. Copper is no longer a side business for BHP; it is half the engine.
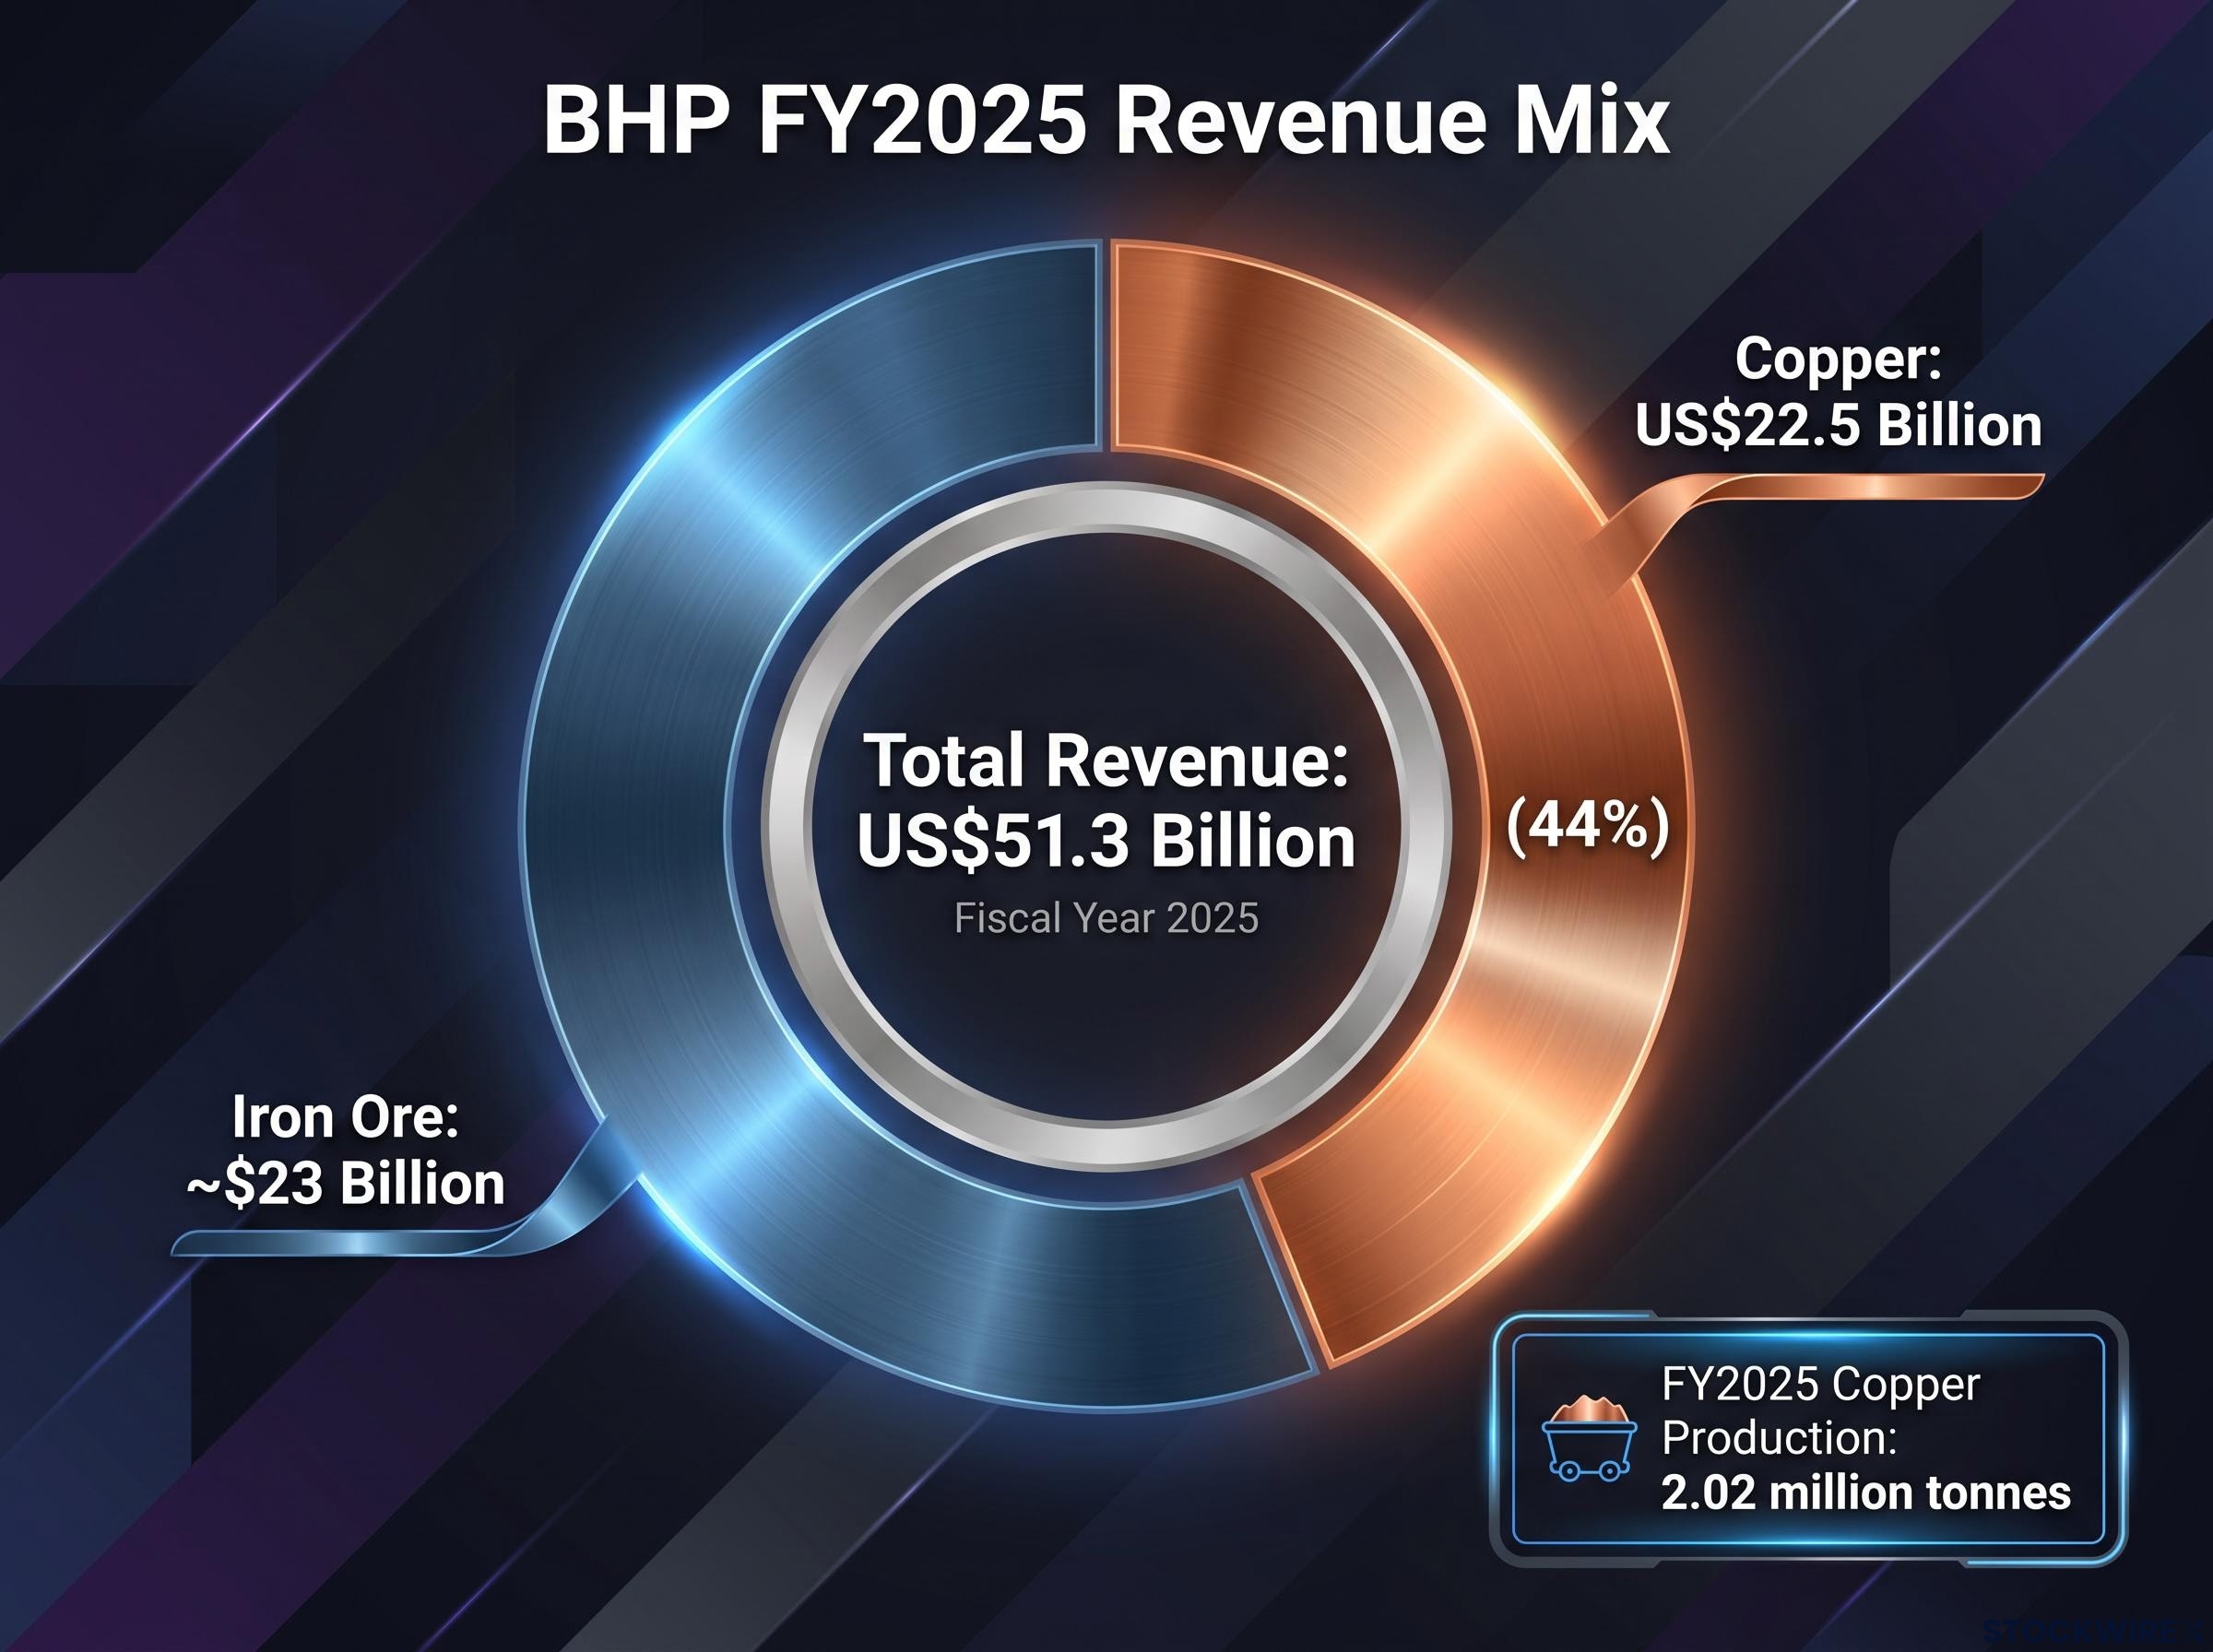
Scale amplifies the leverage. BHP recorded consolidated copper production of 2.02 million tonnes in FY2025, a company record, across operations including Escondida, Pampa Norte, Antamina, and Copper South Australia.
BHP’s 2035 production target of 2 million tonnes per annum, committed at roughly 5% annual growth, was framed by the company as a direct response to the structural deficit; at FY2025 consolidated output of 2.02 million tonnes the target implies the company is already at its long-range run-rate, raising questions about how much additional supply growth the market can actually expect from its largest diversified producer.
The earnings sensitivity is already visible. In its HY26 results (the half-year to 31 December 2025), BHP reported an average realised copper price of US$5.28 per pound, up 32% from US$3.99 a year earlier, helping lift group revenue 11% year-on-year.
Now apply Deutsche Bank’s target. A move toward $10 per pound would represent a near-doubling of that HY26 realised price, and given BHP’s production volumes, the flow-through to revenue and profit would be substantial.
What this shift toward copper tells you is that BHP offers a blend rather than a pure bet. You get meaningful copper upside with the operational diversification of iron ore and other commodities, which softens the blow if copper corrects but also means a copper rally does not lift every business line equally.
That trade-off is why peer choice matters. Different equities let you dial your copper conviction up or down:
- BHP: Diversified major with copper now near half of revenue. Balanced upside and downside protection.
- Freeport-McMoRan: Widely viewed as a purer copper play, with higher earnings sensitivity to copper prices. Favoured by many desks as a primary vehicle for a bullish copper view.
- Rio Tinto: Highly diversified, combining copper with iron ore and aluminium. A copper surge helps, but valuation reflects cyclical conditions across all three markets.
Assessing this spread is how you match the position to your own risk tolerance. If you want maximum torque to the copper price, a purer play offers it. If you want participation with a buffer, a diversified miner like BHP fits the brief. The right answer depends on how much operational downside you are willing to accept for raw upside.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
Variables to monitor before adjusting your metals exposure
Deutsche Bank’s target is aggressive, and it is not guaranteed. The same forces that make copper tight can reverse.
A prolonged slowdown in China’s property and infrastructure sectors could weaken baseline demand, while sudden tariffs or supply-chain disruptions could re-route flows and distort pricing. And high prices carry their own cure: over time they trigger demand destruction, accelerate substitution where it is feasible, and incentivise more recycling and new supply.
That is why this is a call to watch rather than to act on blindly. Three indicators are worth tracking closely: LME inventory levels, which reveal whether the physical squeeze is intensifying or easing; realised copper prices in upcoming miner earnings reports, which show how much of the thesis is already flowing into profits; and the copper-to-aluminium price ratio, which signals how hard substitution pressure is building.
Commodity supply shocks of this character, where emergency reserves fail to halt drawdowns and inventory buffers exhaust faster than the market anticipates, have already played out in oil in 2026: Saudi output fell to a 36-year low and IEA releases of roughly 280 million barrels failed to slow global inventory draws running at 8.5 million barrels per day, offering a template for how thin-margin physical markets respond when scarcity becomes acute.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors. These statements are speculative and subject to change based on market developments and company performance.