For five years, Jim Bianco was one of the bond market’s loudest skeptics, and he was right. As the President and Founder of Bianco Research repeatedly warned investors away from Treasuries, yields kept climbing. Now he has changed his mind, and that shift is worth understanding.
The context is stark. As of 28 September 2026, the 10-year Treasury yield sits at 5.23%, while the 30-year has reached 5.5%, its highest level since 2004. These are not levels most investors have seen in their adult investing lives.
What makes this moment matter is timing. Bianco’s bearish call on bonds through the 2020-2024 cycle was correct, and he is turning bullish precisely when most retail investors are still anchored to the zero-rate mental model of the last decade. After reading this, you will have a clear framework for judging whether 5.5% investment-grade yields represent genuine value for your own portfolio, or a trap dressed up as opportunity.
What shifted in Bianco’s bond thesis, and why September 2026 is the pivot
Start with the two numbers. Two years ago, the 10-year Treasury yielded roughly 3.7%. Today it yields 5.23%. The Federal Reserve spent that entire window cutting interest rates, and long-term yields went up anyway.
That gap is the whole story.
The FRED 10-year Treasury yield data confirms that the current 5.23% reading sits at levels not sustained since before the 2008 financial crisis, providing the long-run historical baseline against which Bianco’s pivot should be measured.
The Fed began cutting on 18 September 2024 from a starting level of 5.25%, and delivered 175 basis points of cuts over the cycle. During that same stretch, the 10-year yield climbed from around 3.7% to over 5%, a rise of roughly 130 basis points.
The 10-year yield rose from 3.7% to over 5% during a 175-basis-point rate-cutting cycle. According to Bianco, this marks the first time in over 50 years that a prolonged cutting cycle has produced higher long-term yields.
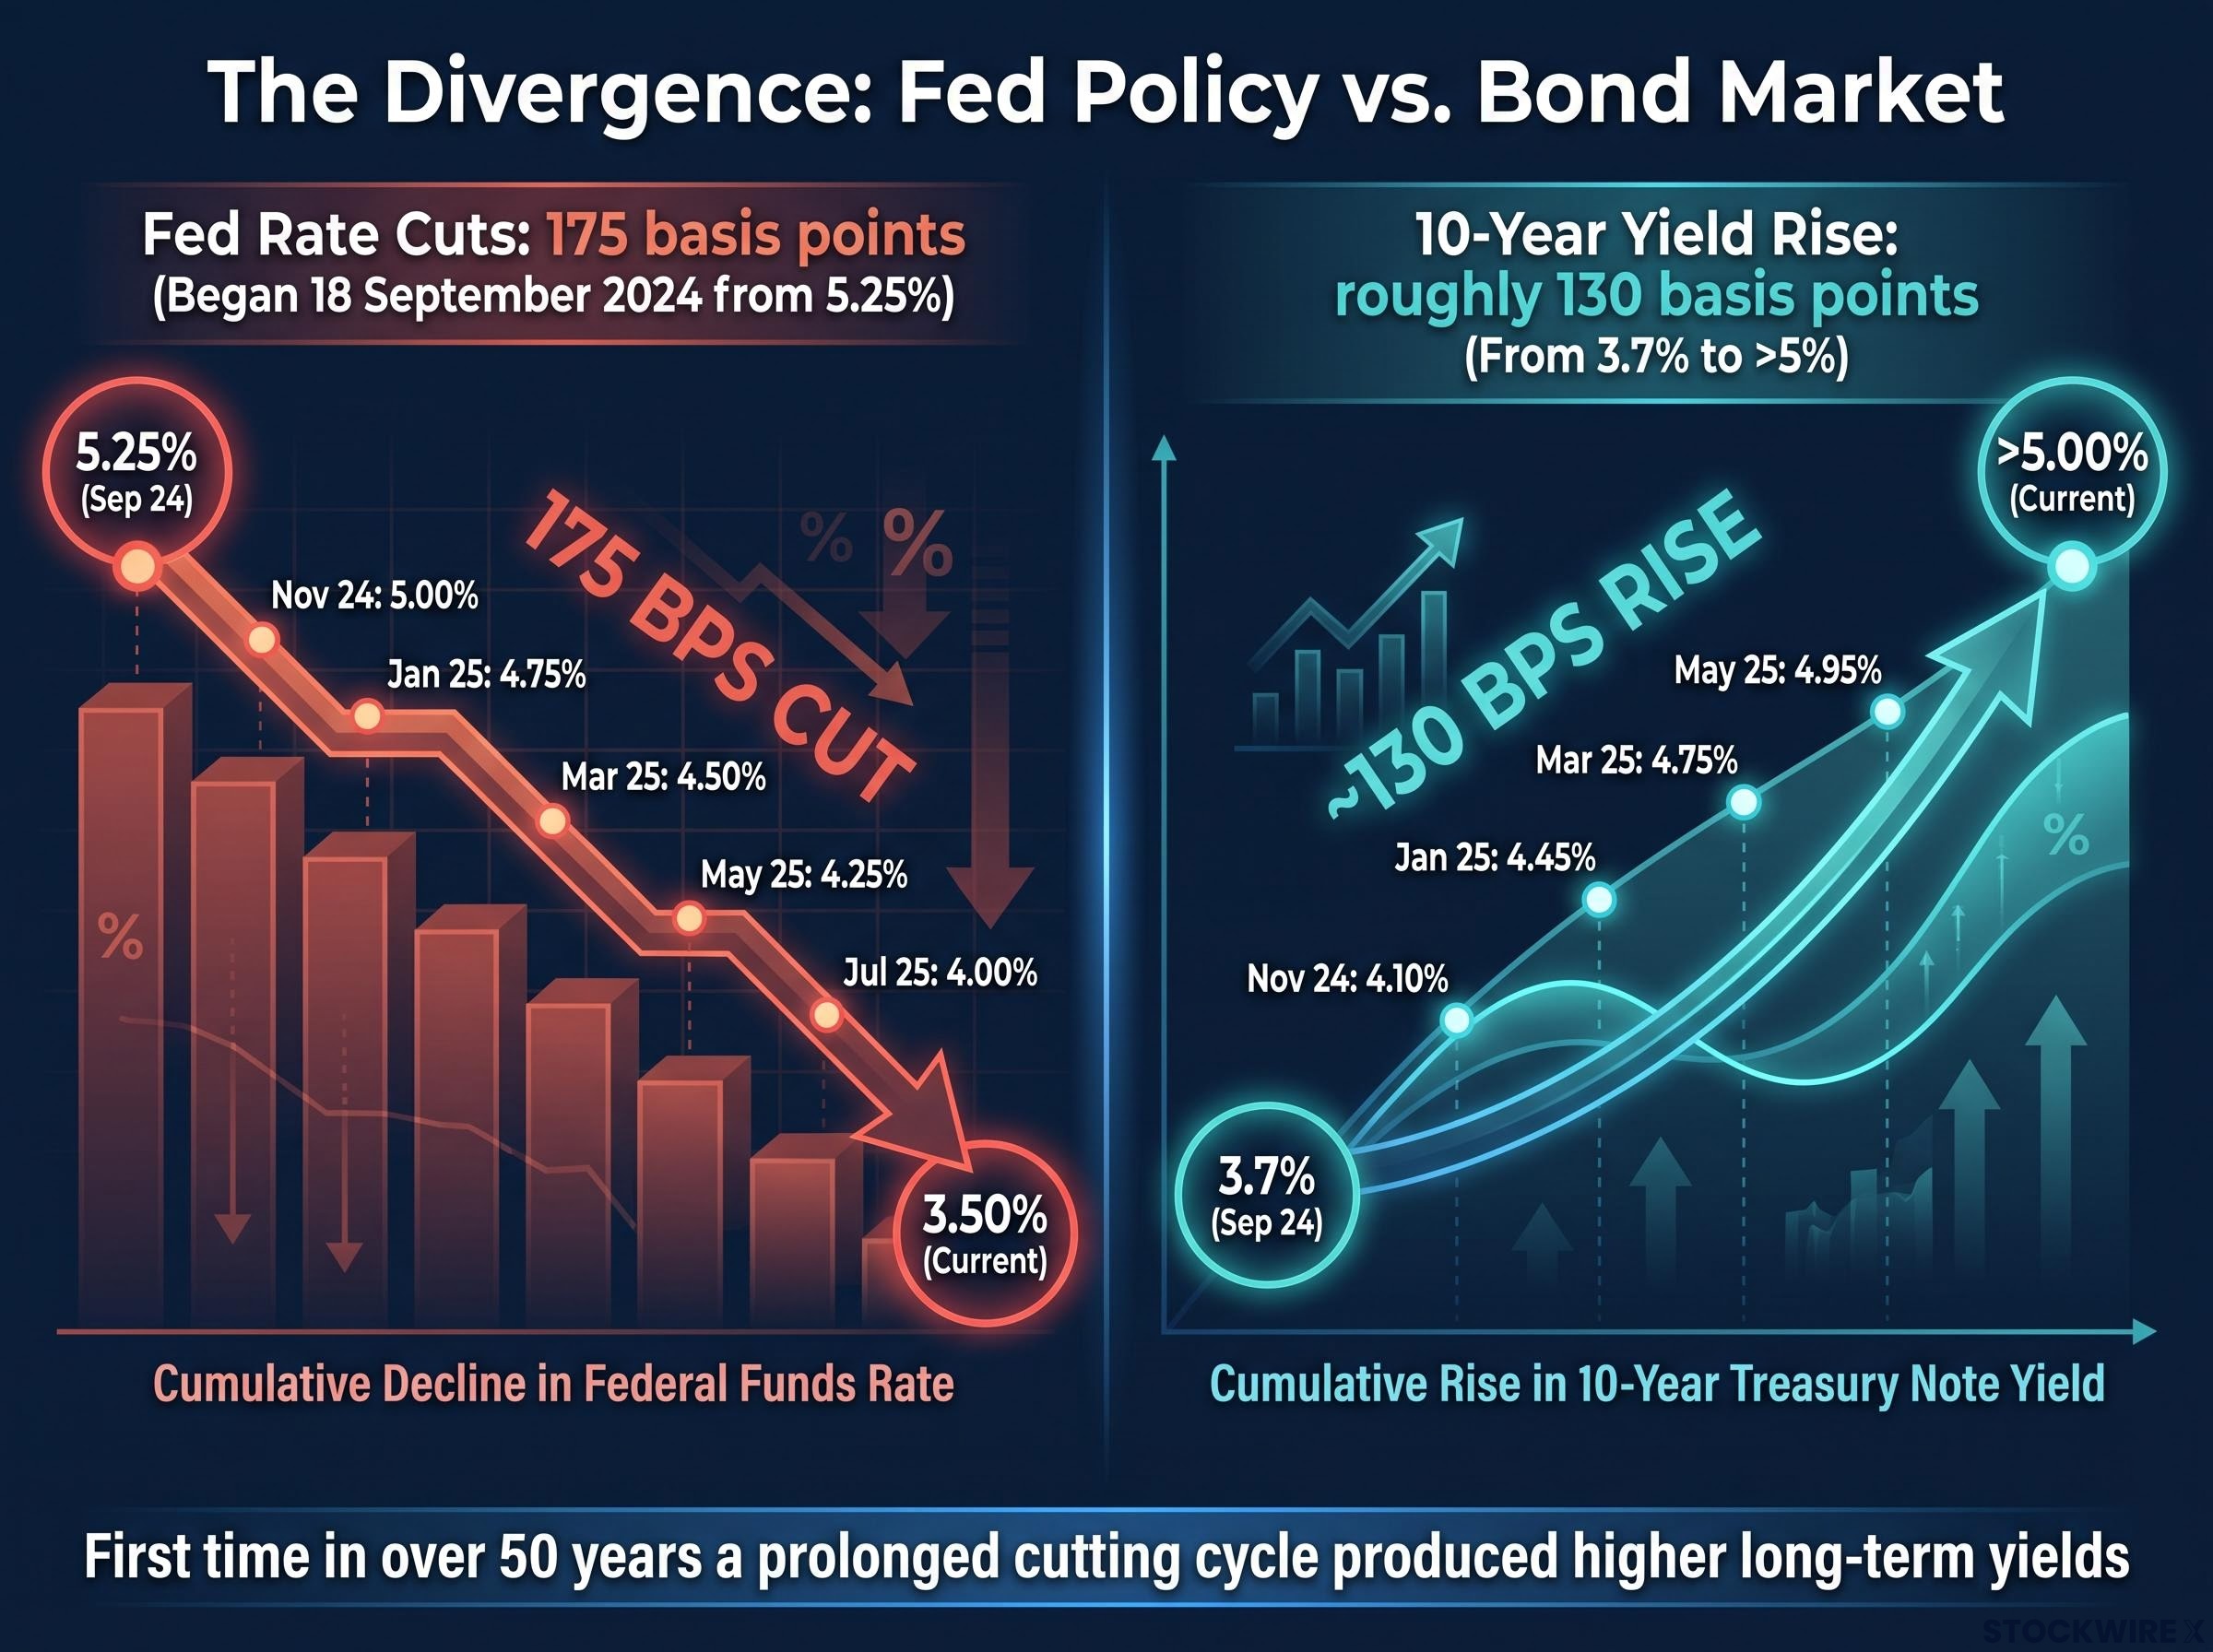
That dynamic is the evidence that the bond market, not the Fed, was setting the price of money. When the central bank cuts and long yields rise regardless, the market is signalling it believes policy is too loose. That reality is what Bianco’s shift is actually responding to.
His bullishness is not optimism. It is a recognition that the negative catalysts that drove yields higher are now largely reflected in the price. The three forces Bianco considers priced in:
- Inflation concerns that dominated the post-pandemic period
- Deficit worries tied to rising public debt
- Excess bond supply from heavy government issuance
With those pressures baked into current levels, the calculus changes. Bianco notes that average investment-grade bonds, including corporates and mortgages, now yield above 5.5%. Government bonds sit near 5.5% with minimal credit risk, making them competitive with riskier assets on a risk-adjusted basis.
Here is why that matters for you. A 5.5% yield does something a 3% or 4% yield never could: it pays you enough to compete with equities without asking you to take equity-level risk. That is the shift, and it is structural rather than a bet on the next rate cut.
When big ASX news breaks, our subscribers know first
The “four, five, six market”: what normal expected returns look like when bonds yield 5%
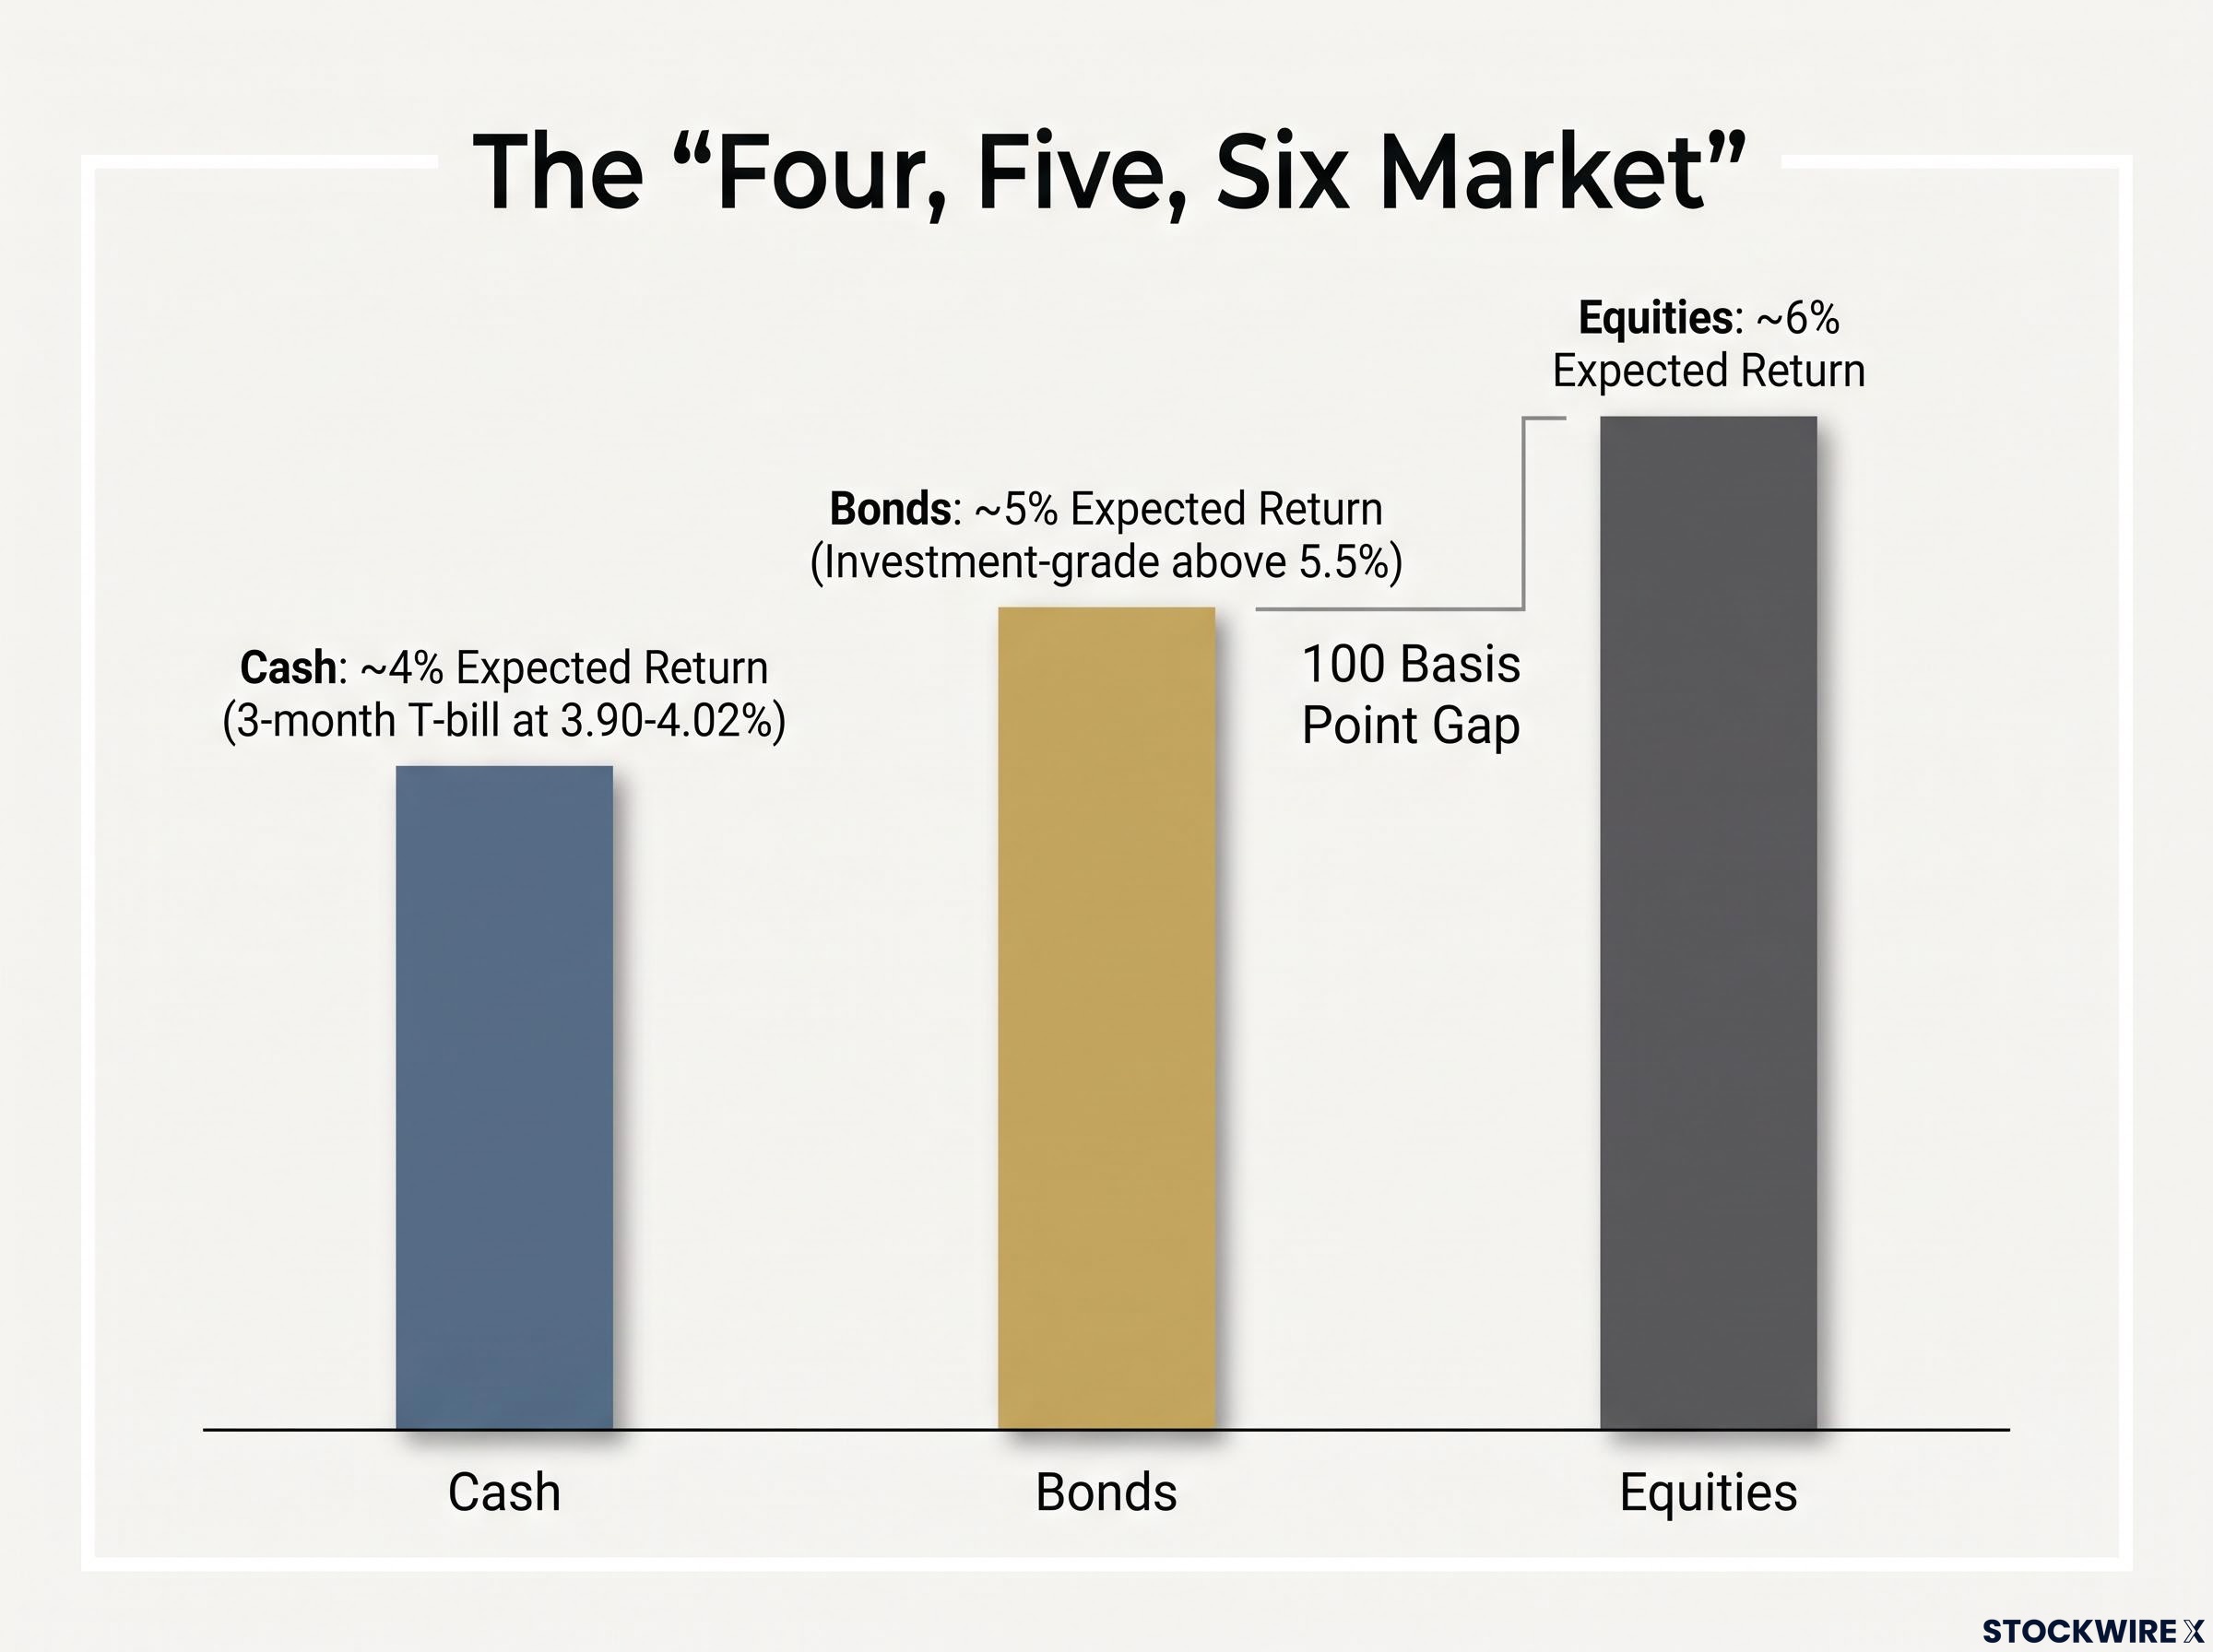
Bianco has a simple way of framing expected returns across the major asset classes. He calls it a “four, five, six market”: roughly 4% from cash, 5% from bonds, and 6% from equities in expected annual returns.
Apply that lens to your own portfolio for a moment. The gap between bonds and equities is only 100 basis points of expected return. That is a very different world from the one investors have lived in.
| Asset Class | Bianco Expected Return | Approximate Current Yield Reference |
|---|---|---|
| Cash | ~4% | 3-month T-bill at 3.90-4.02% |
| Bonds | ~5% | Investment-grade above 5.5% |
| Equities | ~6% | Historical equity risk premium anchor |
For most of the last decade, the choice was not close. Through the 2010-2020 near-zero era, bonds yielded almost nothing, and equities were effectively the only asset offering a real return. If you wanted growth, you concentrated in stocks, and diversification into bonds cost you.
That has now reversed. When bonds pay you 5% for taking duration risk you can measure, the diversification argument stops being a sacrifice and becomes a genuine portfolio conversation.
Bianco is not alone in this reading. PIMCO made the case in its 2023-2024 secular outlook that “bonds are back,” arguing that yields in the 4-5% range on high-quality government and investment-grade credit offered attractive income plus a capital-gain buffer if the economy turned. BlackRock’s Rick Rieder framed the same environment as a “structurally higher-rate world,” where 4-5% yields represent a lasting reset rather than a temporary spike. Both firms treat current levels as fairly priced duration risk, not a dislocation waiting to correct.
PIMCO’s 2026 secular outlook extends that institutional consensus, arguing that geopolitical fragmentation and structurally higher neutral rates make duration at current yield levels a more durable opportunity than the cyclical recoveries that characterised the post-2008 bond rallies.
Why the zero-rate decade was the anomaly, not the norm
Here is the mental adjustment that matters most. Before 2010, bond yields in the 4-6% range were historically ordinary. The near-zero period that followed was the exception, driven by crisis-era quantitative easing and a wave of global disinflation, not by a permanent new regime.
If you are looking at today’s 5.5% yields and feeling they are unusually high, you are comparing them to an anomaly. Measured against the longer historical record, they look like a return to normal. That distinction changes whether you see current yields as a peak to avoid or a baseline to work with.
The higher-rate environment is a structural fiscal reality rather than a cyclical Fed posture: with net interest outlays already exceeding defence spending at roughly $881 billion in FY2024 and the GAO projecting debt at 123% of GDP by 2036, the supply-driven pressure on long yields has a credible long-run foundation independent of any single FOMC decision.
The Fed’s October dilemma and what it means for the yield trajectory
The path of yields from here runs directly through one meeting. On 28 October 2026, the Federal Open Market Committee (FOMC) decides its next move, and the market and Wall Street disagree sharply about what it will do.
As of 28 September 2026, the CME FedWatch Tool and prediction markets both showed a 70% probability of a 25-basis-point rate hike at that meeting, up from roughly 50% just a few weeks earlier. Yet most major Wall Street forecasters expected no action at all, partly because the meeting sits close to the midterm election.
That is a genuine bind, not a routine decision.
Bianco frames the tension plainly: the Fed cannot satisfy everyone at once.
The Fed’s dilemma is that it cannot simultaneously please the sitting president, who would prefer lower rates, and the bond market, which has been signalling policy is too loose by pushing long-term yields higher throughout a cutting cycle.
If the Fed holds while markets are positioned for a hike, bond investors could respond by pushing long-term yields higher still. If it hikes, the near-term price impact on existing bonds would be immediate. The competing forces pulling on yields sit on either side of a fine line:
- Keeping yields elevated: persistent inflation, large fiscal deficits, ongoing quantitative tightening, and a higher neutral rate
- Pulling yields lower: a cyclical slowdown, inflation returning durably to target, or a shift toward fiscal consolidation
The yield curve itself reflects this unresolved tension. The 2-year/10-year spread sits at roughly 36 basis points, modestly positive, while the 3-month/10-year spread is around 100 basis points, its widest in several months. The curve has uninverted, but whether it keeps steepening or reverses remains an open question.
The yield curve itself reflects this unresolved tension, and the yield curve un-inversion carries a historically ominous meaning: the steep-front, flat-back configuration appearing in September 2026 has clustered almost exclusively around periods of elevated economic stress in the post-1990 record.
For you, the practical read is this. A 70% market-implied probability of a hike that most Wall Street desks are not forecasting means bond investors are positioned for volatility on 28 October regardless of the outcome. That uncertainty is itself a reason to understand yield levels carefully before taking on duration risk.
Where the risks actually sit for investors acting on 5.5% yields
None of this makes bonds risk-free at 5.5%. Acting on the Bianco thesis means taking on specific, identifiable risks, and knowing them is what separates calibrated confidence from either blind enthusiasm or paralysis.
Three risks matter most:
- Inflation resurgence. A 5% nominal yield in a 3-4% inflation world delivers a far weaker real return than the same yield in a 1-2% world, so a fresh inflation spike could erode your purchasing power and trigger mark-to-market losses.
- Fiscal supply pressure. Large deficits force governments to issue more long-term debt, and if demand fails to keep pace, yields may need to rise further, hurting the price of bonds you already hold.
- Policy-rate-path uncertainty. If the Fed holds rates higher for longer than expected, cash and short-term instruments could stay competitive with long bonds for years, giving you more flexibility and less price volatility.
Fiscal supply pressure is not an abstract tail risk: at roughly $2.6 billion per day in interest outlays and with the CBO projecting debt held by the public climbing from 100% to 118% of GDP by 2035, the structural incentive to issue more long-term debt is already compressing the equity risk premium to near multi-decade lows.
Bianco’s four, five, six framework is itself a response to these risks. By spreading expected returns across cash, bonds, and equities rather than concentrating in any single asset, it builds in the diversification that rate-path uncertainty demands.
How to implement without reaching for yield in the wrong places
The most common error in a high-yield environment is reaching for even higher yield by moving down the credit spectrum into high-yield or speculative debt. That adds default risk the 5.5% investment-grade case does not require. The whole point is that you no longer need to take that risk to earn a competitive income.
The institutional response is duration discipline. PIMCO, BlackRock, Goldman Sachs, and Morgan Stanley frameworks lean on laddered or barbell bond portfolios, spreading maturities to manage reinvestment risk. Low-cost bond funds or ETFs give broad exposure without concentrating in individual issues, and matching duration to your time horizon keeps the risk aligned with your goals.
Duration discipline is the central variable institutional managers are calibrating in 2026: a bond with duration of 7 loses roughly 7% in price for every one percentage point rise in rates, compared to roughly 3% for a duration-3 bond, which is why BlackRock, PIMCO, and Vanguard all favour the 1-5 year segment of the curve.
| Time Horizon | Recommended Instrument Type | Current Approximate Yield Reference |
|---|---|---|
| Short-term needs | Cash and short-term Treasuries | 3.90-4.02% (3-month T-bill) |
| Intermediate goals | Laddered or barbell bond portfolios | Blend across maturities |
| Long-term goals | Intermediate-to-long Treasuries and investment-grade corporates | Above 5.5% investment-grade |
The risks here are real but manageable. They argue for duration awareness and diversified positioning, not for avoiding bonds at 5.5% in favour of waiting for a moment of certainty that is unlikely to arrive.
Whether to act now or wait for a cleaner signal
Bring the pieces together and a decision framework emerges. Yields at 5.5% investment-grade are historically attractive, but the plausible path to them going higher still makes full, immediate commitment less defensible than staged positioning.
Investment-grade bonds are yielding above 5.5%, a level not seen in roughly two decades. Bianco’s case for them is structural, grounded in yield levels, not speculative bets on the next rate cut.
Waiting has its own cost, and most investors underestimate it. Sitting entirely in cash or short-term instruments leaves you exposed to yield compression if the Fed hikes and long rates then stabilise or fall. Waiting for a “cleaner signal” has historically meant waiting until yields have already dropped and the entry point has passed, the same mistake investors made throughout 2010-2020 while yields fell from already-low levels.
That is what Bianco’s shift actually signals. Not a call to sell equities and buy bonds wholesale, but a recognition that for the first time since 2020, bonds deserve a genuine seat at the allocation table rather than a token position. With only a 100-basis-point gap between expected bond and equity returns, the risk-adjusted trade-off has genuinely changed.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and forward-looking statements are speculative and subject to change based on market developments.