The average American carrying both a credit card balance and a new-vehicle loan is handing over roughly $2,874 a year to lenders, or about $240 every month. That money buys no asset. No goods. No service. It is the price of having borrowed, and nothing more.
Two numbers explain most of it. Credit card interest on accounts actually carrying a balance sits at 22.15% as of Q2 2026, according to Federal Reserve data, while the average new-vehicle loan has climbed to $43,610 per Experian Automotive. These are not headline abstractions. They are the direct inputs behind a specific monthly cash drain running through tens of millions of households right now.
This is not an argument about whether debt is good or bad in principle. It is an accounting of what that debt costs in concrete dollars, and what those same dollars could become instead. After reading, you will be able to see your own debt service not as a routine monthly payment, but as an investment decision you are making by default, month after month.
What the average American actually pays to borrow
Start with the card. The average balance per borrower reached $6,610 in Q2 2026, according to TransUnion’s Credit Industry Insights Report. Apply the 22.15% APR that the Federal Reserve reports for accounts actually accruing interest, and that balance generates roughly $1,464 in interest across a year. That works out to about $122 a month going to nothing but the cost of the balance itself.
The Federal Reserve G.19 consumer credit data, updated through Q2 2026, confirms that the 22.15% APR figure applies specifically to accounts actually accruing interest, a subset that excludes transactors who pay in full each month and therefore captures the true cost faced by revolving borrowers.
Now the car. Experian Automotive puts the average new-vehicle loan at $43,610, financed at 6.35% over 69.46 months, with an average monthly payment of $765. Averaged across the life of that loan, the interest component alone comes to roughly $1,410 a year, or about $118 a month.
Lifestyle creep through vehicle financing is one of the most common channels through which comparison-driven spending enters a household balance sheet, with the average new-vehicle loan carrying roughly $9,300 in total interest costs over its life.
Put the two together and the picture sharpens.
| Debt type | Average balance / loan amount | APR | Estimated annual interest |
|---|---|---|---|
| Credit card | $6,610 | 22.15% | $1,464 |
| Auto loan | $43,610 | 6.35% | $1,410 |
| Combined | – | – | $2,874 |
The cost of borrowing, isolated: roughly $240 a month goes to pure interest, with zero asset return attached to it.
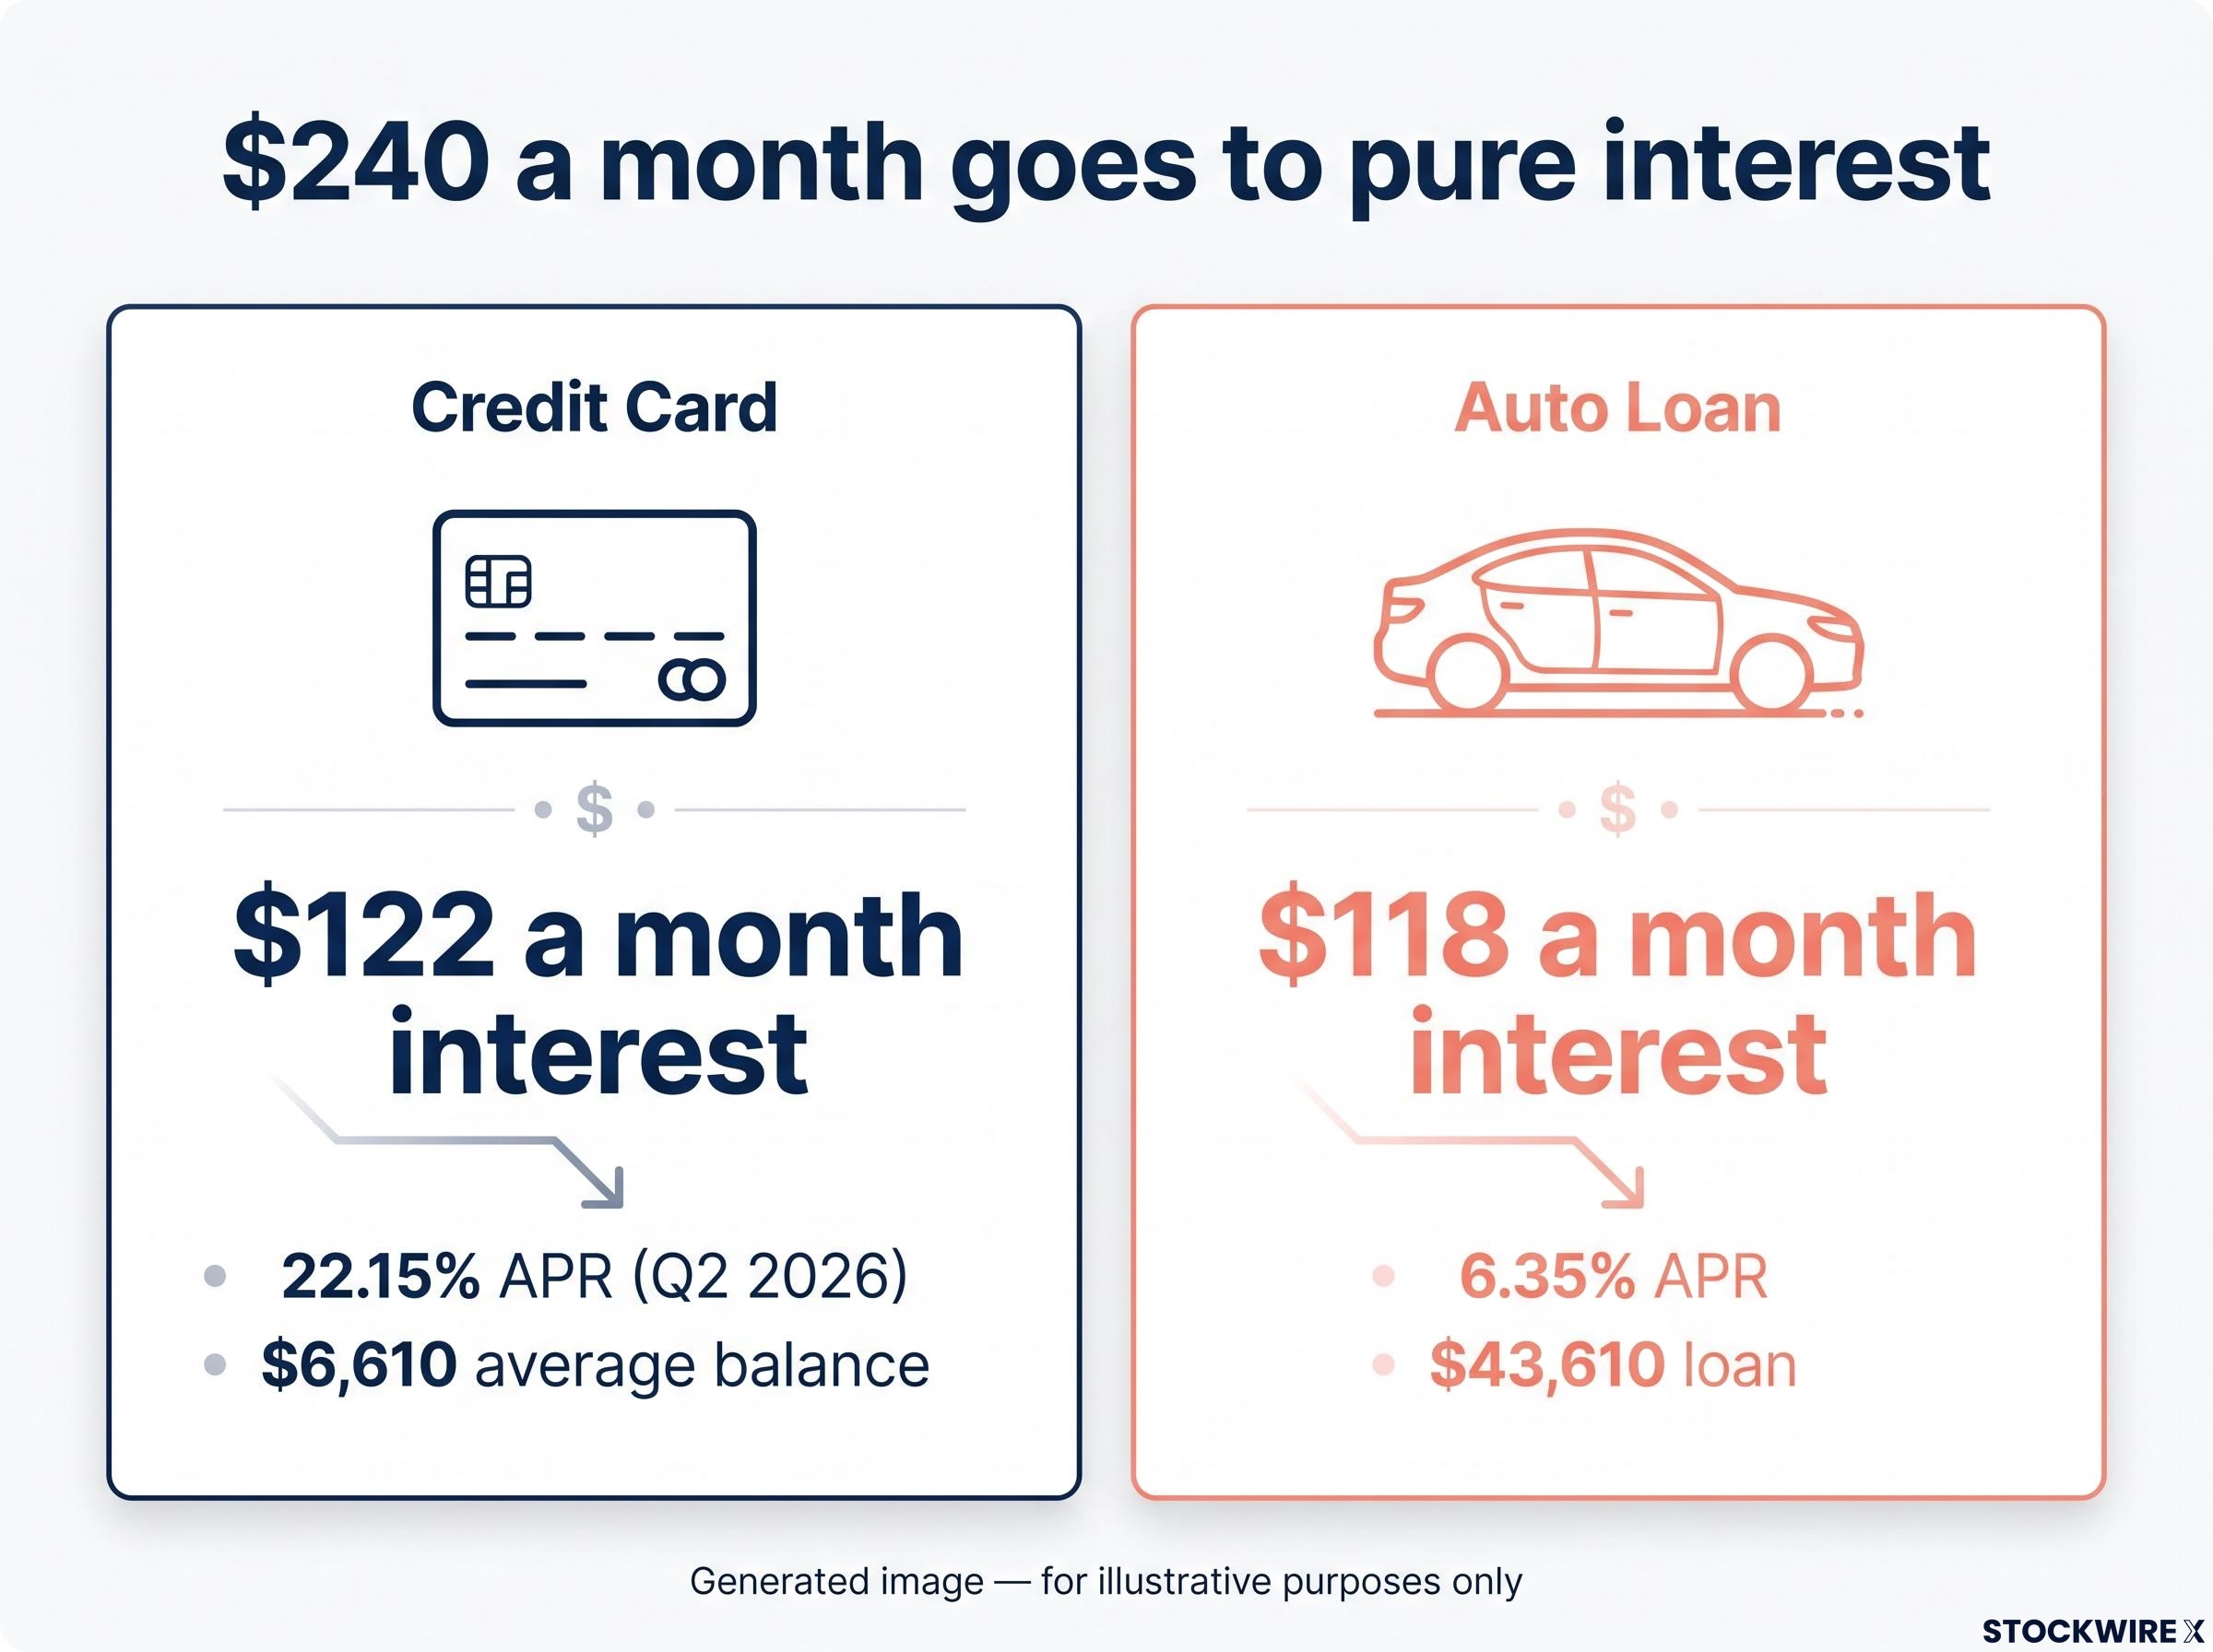
Here is what that figure actually represents. The $240 is not a bill for something you own or use. It is the fee charged for the timing gap between wanting something and having saved for it. Frame it that way and it stops feeling like a utility payment, the water bill you cannot avoid, and starts looking like what it is: an optional charge for impatience, paid every single month.
When big ASX news breaks, our subscribers know first
Why most borrowers stay in the cycle even when they know the rate
If the rate is that punishing, why do so many people stay put? The answer is partly structural, partly by design, and only rarely about willpower.
Start with the structural layer. The Consumer Financial Protection Bureau (CFPB), in its recurring Credit Card Market Reports, describes how many households lean on cards as a liquidity buffer for ordinary living expenses, not just discretionary buys, when income is uneven or savings are thin. The Federal Reserve’s well-being surveys reinforce the point: a large share of Americans cannot cover even a modest unexpected expense without borrowing. When the emergency fund is empty, the card becomes the emergency fund.
The structural reliance on cards as a liquidity buffer is visible in credit card delinquency data, which reached a 15-year high in Q1 2026 but remains concentrated among younger, lower-income, and subprime borrowers rather than reflecting broad consumer distress.
Then there is the way the product itself is built. Low minimum payments, introductory 0% promotions, and rewards programmes all pull attention toward monthly affordability rather than total interest cost, according to CFPB and Federal Reserve research. Academic work on credit card markets, including studies by economist Lawrence Ausubel, shows consumers frequently stay on high-APR cards through sheer inertia, rarely shopping for better terms.
The behavioural layer is quieter but just as powerful. Research on present bias by economists Stephan Meier and Charles Sprenger finds that many people systematically underweight future interest and misjudge how compound interest accumulates. There is also a specific tracking habit worth naming: borrowers tend to watch the post-payday dip in their balance, which feels like progress, while interest quietly rebuilds the balance across the rest of the month. It never quite reaches zero, so the cycle sustains itself.
The forces keeping balances revolving cluster into four distinct mechanisms:
- Income volatility: cards absorb the gap when pay is uneven and savings are insufficient.
- Card design: low minimums, promotional rates, and rewards redirect focus to monthly payment size rather than total cost.
- Behavioural anchoring: tracking the post-payday balance dip creates a false sense of progress.
- Credit-score management: some borrowers keep balances active believing it preserves access, though high utilisation often backfires and lowers scores.
The point of naming these forces is not to excuse the debt. It is to make clear that persistent balances are not simply a discipline failure. The system is architected to keep them revolving, and that architecture is the first thing to neutralise before any payoff strategy can hold.
How compound interest works against you, and what that costs over time
Compound interest is the most celebrated force in investing. Carrying a revolving balance is that same force, pointed in the opposite direction.
Here is the mechanism in plain terms. Compound interest means earning interest on your interest, so a balance grows on top of prior growth. When a card balance never reaches zero each month, the same thing happens, except the interest is being charged rather than earned. It accrues on last month’s unpaid interest, then on the month before that, continuously, working against your net worth instead of for it.
Compounding is the same engine whether it builds wealth or erodes it. On a revolving balance, it is running in reverse, every day.
That reversal does not stay contained to the card. It spills into two other costs that widen over time.
The first is a credit-score feedback loop. Persistent balances push credit utilisation, the share of your available credit you are using, higher. According to CFPB and credit bureau research from TransUnion and Experian, high utilisation depresses scores, and lower scores mean higher APRs on the next loan, whether a car, a personal loan, or sometimes a mortgage. Expensive debt begets a lower score, which begets more expensive debt.
The second is retirement readiness. Analyses drawing on the Federal Reserve’s Survey of Consumer Finances and Employee Benefit Research Institute (EBRI) data show households with persistent high-interest debt tend to hold lower retirement balances at comparable ages and under-save relative to recommended targets. Every dollar sent to a 22.15% APR is a dollar not compounding at even a modest investment return.
The long-run cost lands in three places:
- Retirement savings gap: dollars servicing high-rate debt are dollars not compounding toward retirement, and the shortfall widens across decades.
- Credit score feedback loop: high utilisation lowers scores, raising the rate on future borrowing.
- Emergency savings shortfall: heavy balances crowd out liquid buffers, making small setbacks trigger yet more high-rate borrowing.
This is the part most borrowers never see billed. If you are 35 with a persistent revolving balance, you are not only losing $2,874 this year. You are also losing the compounding return that $2,874 could have generated, and that second loss grows every year, silently, without ever appearing on a statement.
The dollar value of redirecting $240 a month away from interest
So what is the other path actually worth? This is where the abstraction becomes a number you can hold.
Clear the revolving card balance and stop renewing auto financing, and roughly $240 a month currently lost to pure interest becomes free. No raise required. No cut to lifestyle spending. The money is already leaving your account each month; it simply changes destination.
Redirect that $240 into a diversified portfolio earning an assumed 7% annual return, and over 10 years the arithmetic runs as follows. You contribute about $28,741 of your own money. The projected balance reaches roughly $41,455. The difference, approximately $12,700, is compounding growth that required no additional labour on your part.
Set the two paths side by side and the trade-off stops being theoretical.
The compounding cost of vehicle financing and wealth gaps is measurable at the household level: two people on identical $95,000 salaries can produce a $571,000 net worth difference over ten years purely through differences in financing and spending behaviour, not income.
| Metric | Debt path (status quo) | Investment path (redirect $240/mo) |
|---|---|---|
| Annual outflow | $2,874 in interest | $2,880 contributed |
| 10-year total out-of-pocket | $28,741 interest paid | $28,741 contributed |
| 10-year value created | $0 asset value | $41,455 projected portfolio value |
$12,700 in projected compounding gains above what you put in, produced by a modest monthly redirect at a conservative return assumption.
The $12,700 is not a best-case scenario. It is what a blended 7% return generates from a relatively small monthly amount over a single decade. Which means the opportunity cost of staying in the debt cycle is not hypothetical; it is already measurable, and it is material.
There is a psychological dimension too, and it is what makes the change durable. Employer financial-wellness research finds that eliminating debt payments shifts the subjective experience of spending. A purchase stops feeding an open-ended, accumulating balance and becomes a closed monthly transaction. Workers who clear high-interest debt are more likely to raise retirement contributions and stick with automatic savings, and American Psychological Association Stress in America surveys consistently link high debt loads to stress, with payoff associated with improved well-being and a greater willingness to plan for the long term.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and projections are subject to market conditions and various risk factors.
Debt elimination is not the finish line, it is the starting condition
The most useful thing to take from all of this is not motivation. It is a reframing of what financial progress actually looks like.
The $240 monthly interest drain is not a fixed cost of modern American life. It is the price of one specific financing pattern, and a pattern can be changed deliberately once you see it clearly.
That said, eliminating debt is rarely an all-or-nothing sprint, and the sequencing matters. Financial planners broadly agree that capturing a full employer retirement match, often an immediate 50-100% return on matched contributions, and holding a basic emergency fund typically take priority over accelerated payoff of moderate-rate debt. Think in terms of order, not either-or.
Choosing the right financial progress benchmarks matters when translating a debt-payoff sequence into a longer-term wealth plan: median US household net worth sits at $192,900, not the $1,063,700 mean figure most headlines cite, and the gap reflects how much of visible affluence is financed rather than accumulated.
A practical sequence looks like this:
- Establish a basic emergency fund so a car repair or medical bill does not force you back into high-rate borrowing.
- Contribute enough to capture the full employer retirement match, the highest guaranteed return available to most workers.
- Direct surplus cash toward eliminating high-APR revolving balances, starting with the most expensive.
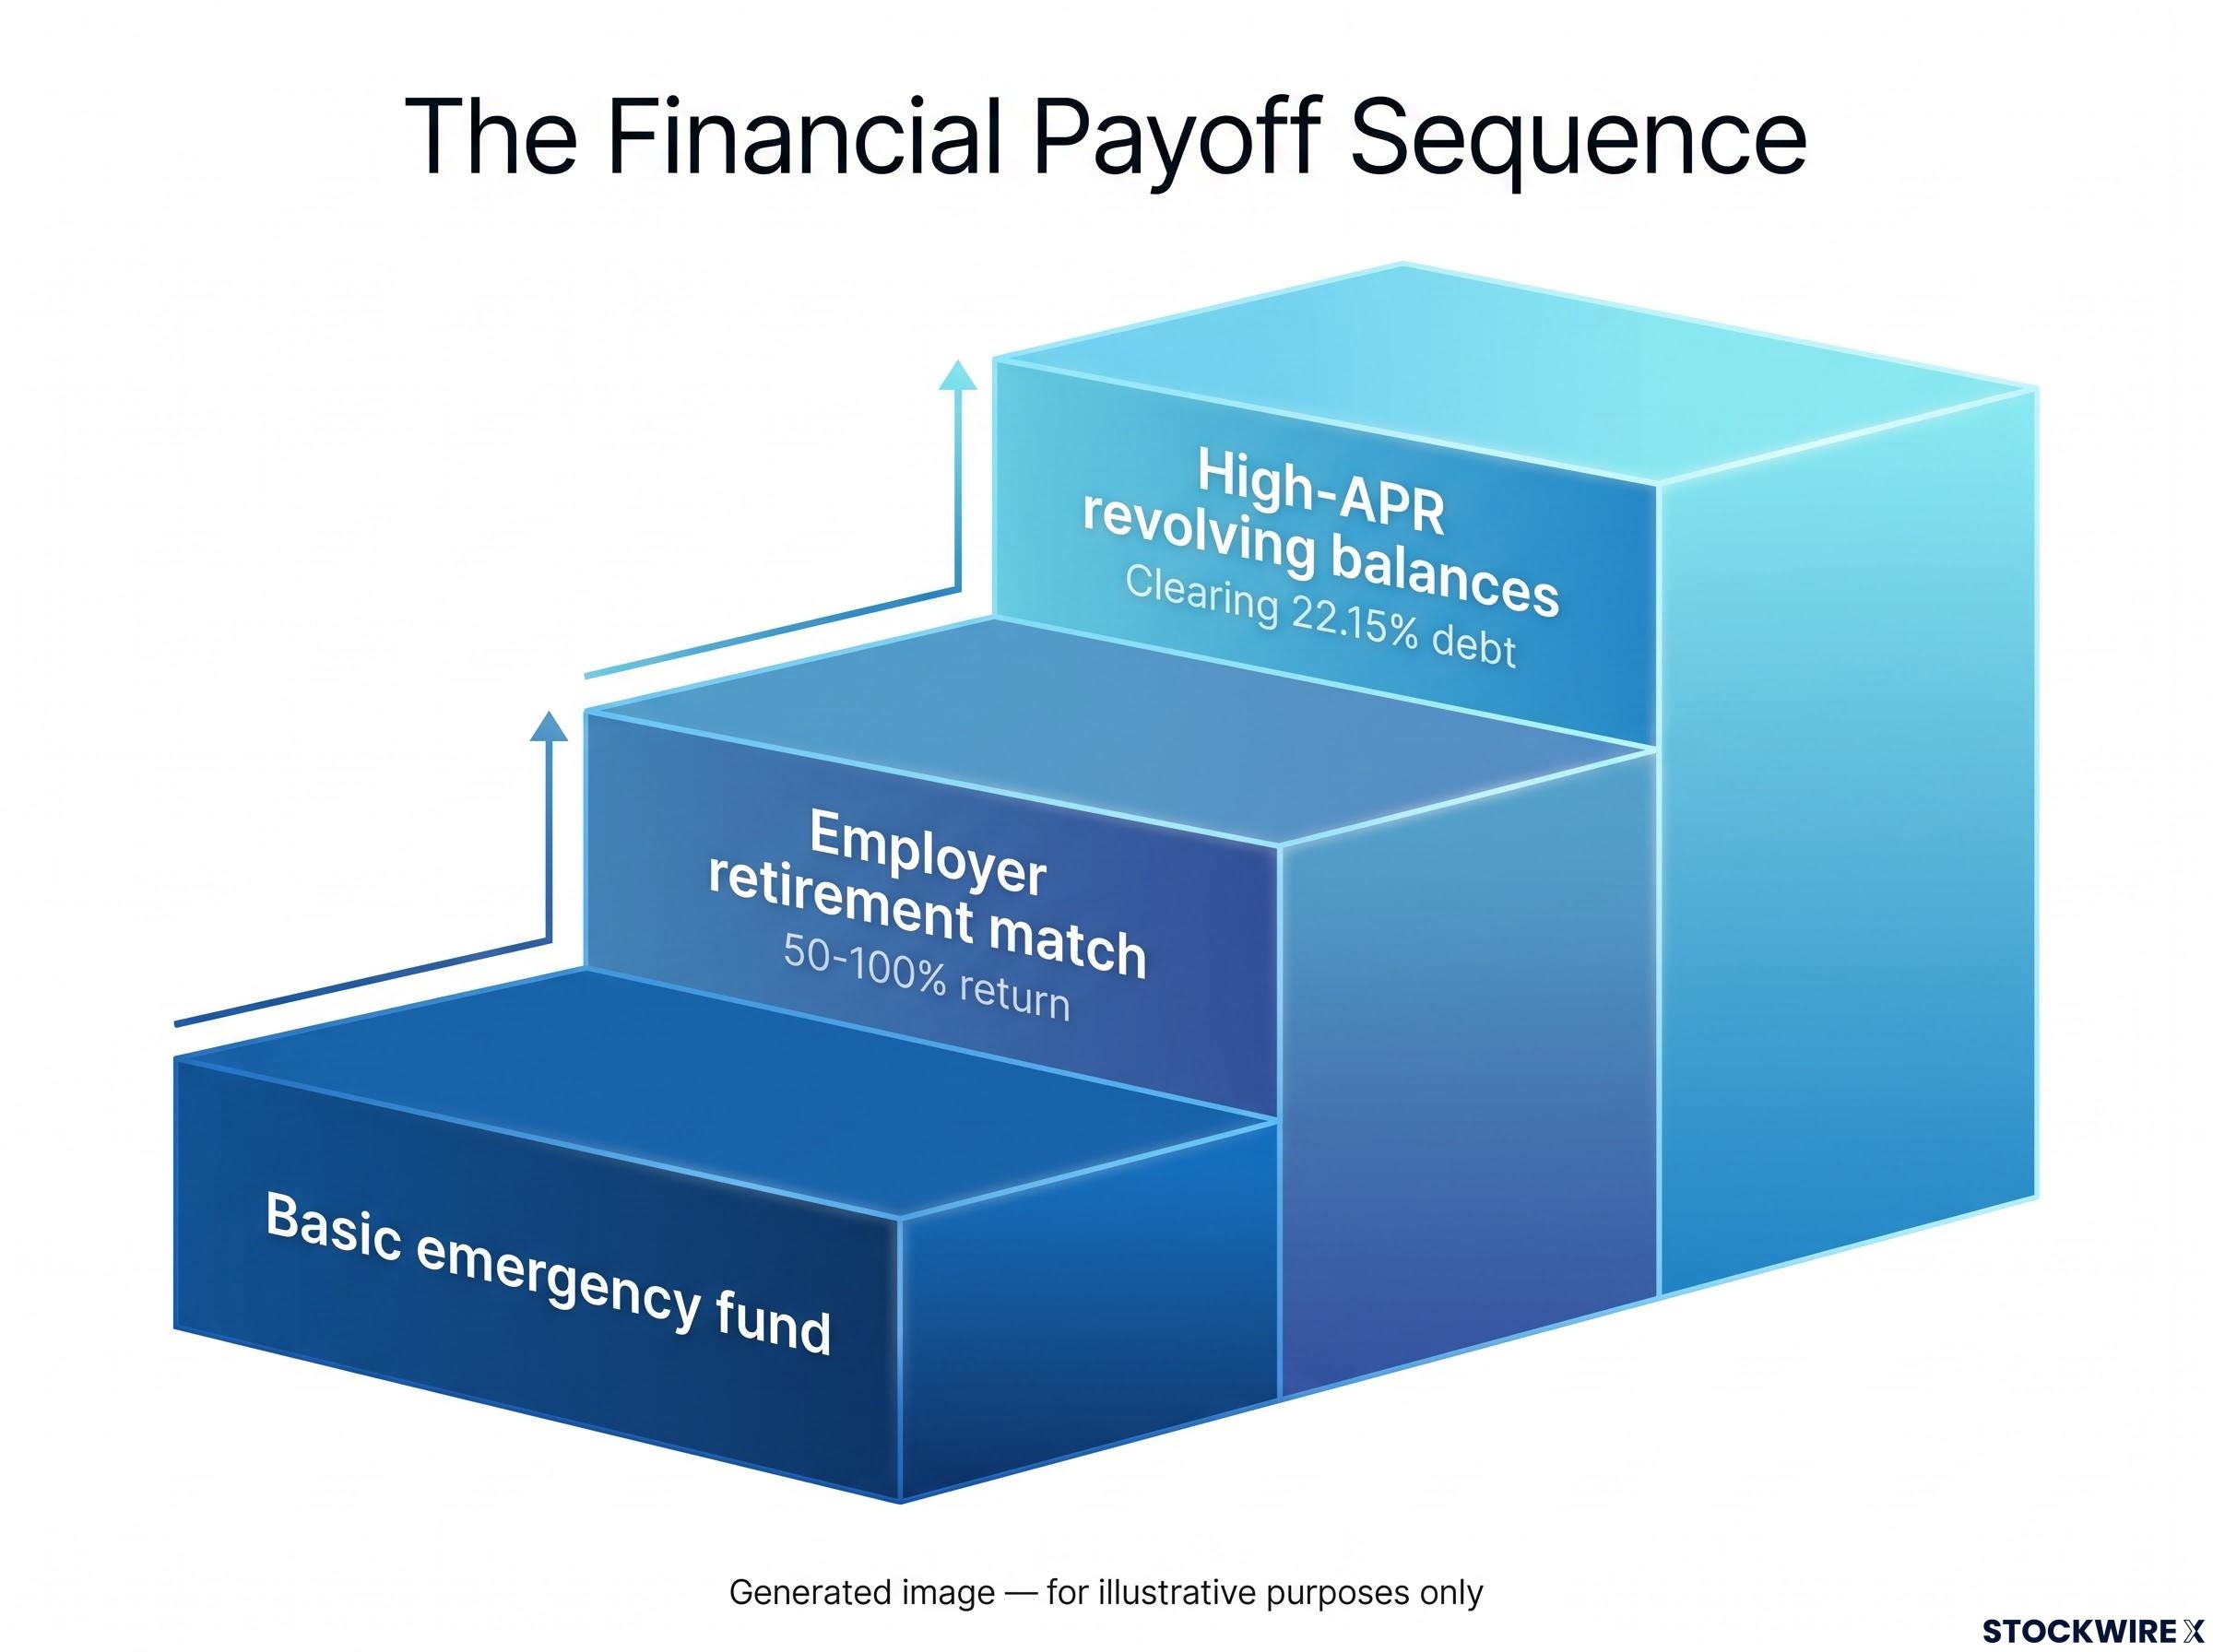
Here is the asymmetry worth remembering. Clearing a 22.15% balance does not merely stop the bleeding. It reverses the direction of compounding. The same dollar that was working against your net worth every month starts working for it. That reversal, not the payoff itself, is where the real wealth effect begins.