Brookfield has a signed deed, the Reliance Worldwide board has unanimously backed it, and two credible research houses are still on record saying the price is too low. Morningstar puts the standalone business at A$5.70 a share. Citi’s Samuel Seow calls the offer, worth roughly A$4.75 in Australian dollar terms, one that “appears low.” That gap between what is on the table and what these analysts say the company is worth is the whole story.
The clock matters here. The go-shop window that lets Reliance shop for a better bid closes on 16 October 2026, no rival offer has surfaced as of 20 September 2026, and the scheme booklet is not due until November 2026. There is a narrow window to form a view before the process hardens into a binding vote. Notably, RWC shares sit at A$4.59, below the offer’s implied A$4.75, which tells you the market is already pricing in some chance the deal wobbles.
Here is what the competing valuations, the business fundamentals, and the deal structure actually tell you about whether US$3.38 is the right exit price for a share you hold today.
What the Brookfield deal actually involves
Brookfield Capital Partners has signed a scheme implementation deed (SID) to buy every Reliance Worldwide Corporation share for US$3.38 in cash. The board has recommended shareholders accept, but that recommendation carries two conditions: no superior proposal emerges, and an independent expert concludes the scheme serves shareholders’ best interests.
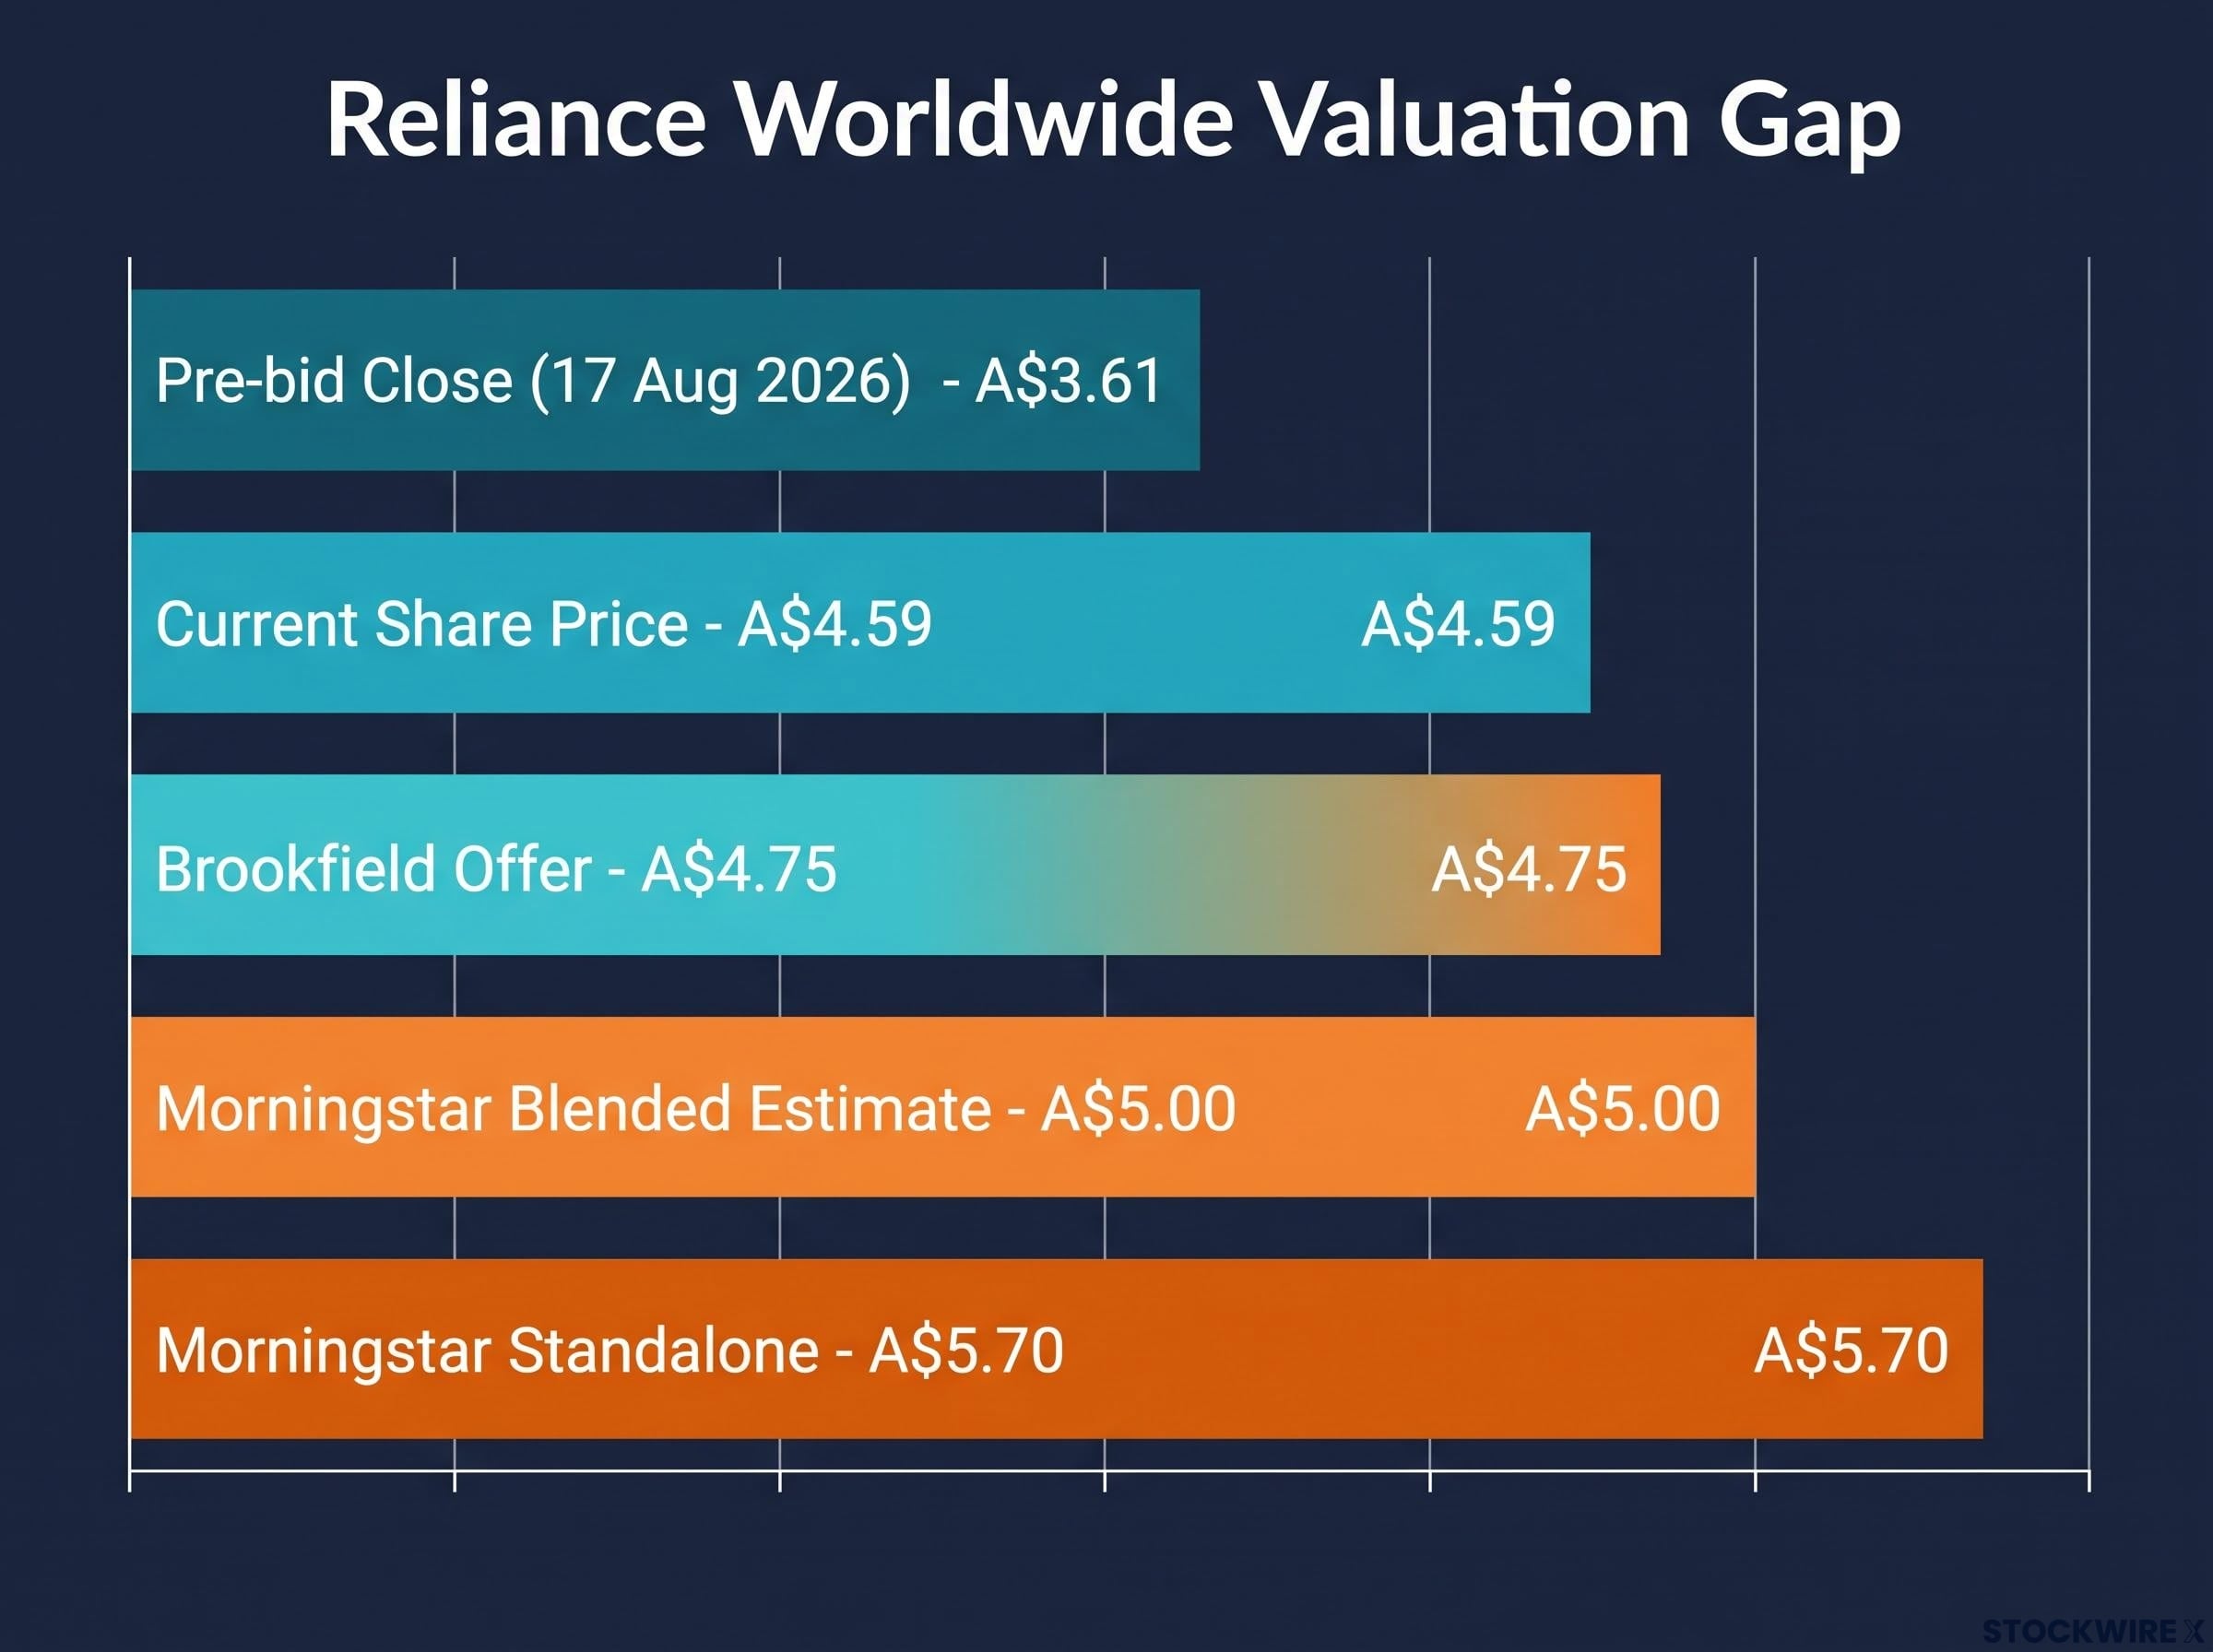
The currency mechanics are worth pausing on. The original non-binding bid was pitched at A$4.75 per share, then switched to US dollars at signing to match RWC’s reporting currency. At an AUD/USD rate of 0.7126, that US$3.38 converts back to roughly A$4.75, but the Australian-dollar value now floats with the exchange rate right up to completion in early 2027.
The headline numbers are substantial. The deal values RWC at approximately A$4.1 billion (US$2.9 billion) including debt, a premium of about 32% to the pre-bid close of roughly A$3.61 on 17 August 2026. This was Brookfield’s fourth run at the company.
Brookfield’s escalating bid history is central to understanding the current offer: the consortium approached RWC four separate times, moving from A$4.15 in April 2026 through A$4.25 and A$4.50 before landing at the current figure, which itself signals how much negotiating room Brookfield absorbed before signing the SID.
The recommendation is conditional, not locked in. The board’s unanimous backing applies only while no superior proposal exists and only if the independent expert concludes the scheme is in shareholders’ best interests. Neither condition is settled yet.
The structurally important feature still in play is the go-shop provision. Until 16 October 2026, Reliance can actively solicit rival bidders, hand them due-diligence materials, and negotiate terms. After that date, Brookfield’s matching rights kick in and a break fee of about US$25.3 million applies.
Here is the sequence that matters:
- SID signed and offer converted to USD: 15 September 2026
- Go-shop period closes: 16 October 2026
- Scheme booklet expected: November 2026
- Anticipated completion: early 2027
The A$0.16 gap between the current A$4.59 share price and the implied A$4.75 offer is your signal. The market is discounting some probability the deal fails, gets renegotiated, or is eroded by currency movement, and that discount is information you should weigh before deciding to hold or position for the vote.
When big ASX news breaks, our subscribers know first
Why two credible analysts say Brookfield is buying at a discount
The disagreement over this offer is not a squabble over a few cents. It is a genuine contest between two ways of reading what Reliance is worth, and understanding both is what lets you judge whether A$4.75 is enough.
Morningstar’s Esther Holloway puts the standalone fair value at A$5.70 a share, roughly 17% above the offer. Her argument rests on treating RWC’s current pressures, tariffs, a weak US housing cycle, and input-cost inflation, as transitory rather than permanent. On that view the market has been over-penalising cyclical risk relative to the company’s underlying earnings power.
Holloway also runs a probability-weighted number, blending the two possible outcomes into a single estimate of A$5.00. That reflects a 75% chance the deal completes near A$4.75 and a 25% chance it fails and the shares drift back toward the A$5.70 standalone value over time.
Citi’s Samuel Seow arrives at a similar conclusion by a different route. He values the offer at about 12.1 times FY26 EBITDA, roughly RWC’s long-term average multiple, and that is precisely his objection. Paying an average multiple on FY26 adjusted EBITDA of US$242.1 million, down 12.8% year on year and about 13% below normalised levels, means Brookfield is buying on depressed earnings. Seow’s verdict is that the bid “appears low despite the approximately 32% premium.”
The premium looks generous only against a beaten-down starting point. RWC was trading near A$3.61 before the bid, already about 25% below Morningstar’s A$5.70 valuation. A 32% premium on a discounted price does not necessarily bridge the gap to intrinsic value.
ASX scheme of arrangement premiums have historically run 35-40% above pre-bid trading prices at the long-run median, which puts RWC’s 32% premium slightly below that benchmark and reinforces the Citi and Morningstar critique that the offer is priced at the lower end of what comparable transactions have delivered.
| Analyst / Firm | View on Offer | Key Metric or Rationale | Implied Fair Value |
|---|---|---|---|
| Morningstar (Holloway) | Below intrinsic value | Current headwinds transitory; market over-penalising cyclical risk | A$5.70 standalone; A$5.00 blended |
| Citi (Seow) | “Appears low” | 12.1x FY26 EBITDA on depressed earnings | Above offer (not specified) |
| Macquarie (Steyn / Lavender) | Risk-adjusted attractive | Binding SID de-risks deal; go-shop retains upside | Emphasises certainty over a number |
| Bloomberg / Reuters | Neutral on valuation | Notes 32% premium and A$4.1bn enterprise value | No valuation opinion |
The split is really a disagreement about whether today’s earnings are the right basis for valuation at all. Accepting or rejecting the price now is essentially a bet on which camp reads RWC’s earnings trajectory correctly.
The case for taking the certainty
Macquarie analysts Peter Steyn and William Lavender decline to call the offer too low. They frame the binding SID as “materially de-risking the transaction and providing valuation certainty,” and they point out the go-shop still preserves upside optionality if a superior bidder appears.
Their argument sits on the specific risks a shareholder trades away by holding out: tariff uncertainty running through to early 2027, sustained US housing weakness, the ongoing restructuring of the APAC manufacturing footprint, and the currency risk baked into a US-dollar offer. Against that backdrop, certain cash has real appeal.
There is one number worth keeping honest about here. If the scheme fails, the realistic near-term floor is the pre-bid price of roughly A$3.61, not A$5.70. The higher figure is a long-term view that assumes the recovery Morningstar expects actually arrives.
What Reliance Worldwide is actually worth on its own merits
To judge whether A$5.70 is fanciful or fair, you need to understand what the business earns when conditions are normal. Reliance is a behind-the-wall plumbing manufacturer, and its crown asset is SharkBite, the push-to-connect fitting brand that holds an estimated 85% of the US push-to-connect category.
The competitive position is stronger than the recent share price suggests:
- SharkBite is the sole push-to-connect brand stocked by both Home Depot and Lowe’s, the two largest US home-improvement retailers.
- Roughly 75% of revenue comes from the repair, renovation, and improvement category, which is far less exposed to new-build housing cycles than most plumbing peers.
- Growth initiatives such as SharkBite Max, a premium push-to-connect line, and EvoPex, aimed at new-construction penetration, extend the product range.
- A steady bolt-on acquisition pipeline (Holman, EZFlo, John Guest, HoldRite) has broadened the portfolio over recent years.
The earnings are geographically concentrated in the US. On Morningstar’s midcycle estimates, the Americas contribute about two-thirds of EBITDA, Asia-Pacific around 20%, and EMEA roughly 15%. That US weighting is exactly why tariffs and American housing weakness hit RWC’s numbers so hard in FY26.
Now the headwinds, because they explain the gap between intrinsic value and the market price. US tariffs carried an estimated US$25-30 million earnings impact. Weak existing-home turnover dented demand, and input-cost inflation pushed the adjusted EBITDA margin down to 18.5% from 21.1% the year before.
RWC’s tariff cost containment proved better than the market initially feared: the net FY26 tariff impact tracked toward the lower end of the US$25-30 million guidance range, and a refund claim was lodged after the US Supreme Court struck down IEEPA-based tariffs in February 2026, partially offsetting the headwind Brookfield is now using to justify a depressed-earnings multiple.
The most alarming figure is reported NPAT of just US$6.3 million. But that number is almost entirely the product of about US$103 million in one-off restructuring and impairment charges tied to rationalising the APAC metals manufacturing footprint, including the closure of Melbourne brass casting, forging, and machining operations.
RWC’s FY26 operating cash flow conversion of 108.8% significantly outpaced reported earnings, a divergence that matters because it shows the business generating real cash even as one-off restructuring charges compressed the statutory NPAT figure to US$6.3 million.
| Metric | FY26 Reported | FY26 Adjusted |
|---|---|---|
| Net sales | US$1,305.6M (down 0.7%) | Up 3.0% |
| EBITDA | Reflects one-off charges | US$242.1M (down 12.8%) |
| EBITDA margin | Depressed by charges | 18.5% (from 21.1%) |
| NPAT | US$6.3M | US$125.1M |
| EPS | Distorted by one-offs | 16.5 US cents |
The distinction that matters for your decision is cyclical versus structural. On adjusted earnings, the business still generated US$125.1 million of NPAT and strong operating cash flow, which is why the shares fell about 40% from their 2024 high yet Morningstar sees value at A$5.70. One genuine structural caveat: the original push-to-connect patents have lapsed, so the moat now rests on brand strength, retailer exclusivity, and product iteration rather than patent protection.
What ASX precedents tell us about fighting a PE bid on valuation grounds
Holding out for more is not a costless option, and recent ASX history shows exactly what it can mean. The most instructive case is Origin Energy.
AustralianSuper held more than 17% of Origin and publicly branded the Brookfield-led consortium’s offer as “substantially below” long-term value, arguing the company was better off in existing hands than with a private-equity buyer “seeking to make a quick return.” It voted against.
AustralianSuper on the Origin bid: the consortium offer sat “substantially below” long-term value, and the business was “an ideal platform to invest in the energy transition.”
At the scheme meeting, only 68.92% of votes were cast in favour, short of the 75% threshold Australian scheme law requires. The takeover failed. The outcome for holdouts was not a higher bid; it was retaining an Origin holding whose long-term trajectory remained uncertain, with no PE cash received.
Two more recent cases show boards themselves refusing to engage. Monash IVF’s board rejected a consortium proposal it called “opportunistic in its timing” and one that “materially undervalues” the company. In September 2026, Ingenia Communities’ board rejected a Warburg Pincus approach as “substantially undervaluing the property group.” In both, no deal proceeded at those prices and shareholders kept their exposure.
| Company | Bidder | Board / Shareholder Response | Outcome for Holdouts |
|---|---|---|---|
| Origin Energy | Brookfield / EIG consortium | AustralianSuper voted against (“substantially below” value) | Scheme failed at 68.92%; retained exposure, no cash |
| Monash IVF | Genesis Capital / WHSP | Board rejected as “opportunistic” and undervaluing | No deal; retained exposure |
| Ingenia Communities | Warburg Pincus | Board rejected as “substantially undervaluing” | No deal; retained exposure |
The parallel for RWC is direct. Australian scheme law needs 75% of votes cast in favour plus a majority in number of shareholders, so a unanimous board recommendation does not guarantee passage if large institutions share the Morningstar and Citi view.
ASIC’s scheme of arrangement rules set the 75% approval threshold and procedural framework that governs the RWC vote, meaning a concentrated bloc of dissenting institutional shareholders holds genuine power to sink the deal at the scheme meeting.
The Origin case is the one to sit with. A credible large holder with a clear thesis voted no, the threshold failed, and the reward was continued business risk rather than a fatter bid. That means holding out is not a riskless claim on a higher price. It is an exchange of cash certainty for business risk, with a realistic floor near A$3.61 if the scheme collapses and no competing bidder appears before 16 October 2026.
Making a call before the go-shop window closes
The honest position is that this is not yet resolved, and three variables will decide it before the scheme vote:
- Whether a competing bidder emerges before 16 October 2026 (none has as of 20 September 2026).
- Whether major institutional shareholders signal an intent to vote against.
- Whether the independent expert concludes the scheme is in shareholders’ best interests, in the booklet expected November 2026.
The independent expert conclusion that must satisfy shareholders before this scheme can proceed is governed by ASIC RG 111 expert report standards, which require the expert to form a view on whether the scheme is fair and reasonable to shareholders on a standalone valuation basis, not merely relative to the pre-bid market price.
For a shareholder holding today, two realistic paths sit in front of you. Accept roughly A$4.75 in certain cash, about 17% below Morningstar’s A$5.70 standalone value. Or hold through the vote betting on either a higher bid or a long-term recovery toward A$5.70, accepting a realistic near-term floor near A$3.61 if the scheme fails.
There is a currency wrinkle that Australian holders should not ignore. The offer is fixed at US$3.38, so its Australian-dollar value floats until early 2027. A strengthening Australian dollar would quietly erode the cash you eventually receive.
Morningstar’s probability framing: a 75% chance the deal completes near A$4.75, and a 25% chance it fails and the shares revert toward the A$5.70 standalone value over time.
The A$0.16 gap between the current A$4.59 price and the implied A$4.75 offer is the market’s live estimate of deal-failure, renegotiation, and currency risk combined. That gap is more useful to you than any abstract debate about fairness.
So the real question is not whether US$3.38 is fair in isolation. It is whether A$4.75 is adequate compensation for giving up the recovery upside Morningstar prices at A$5.70, given the tariff, housing, restructuring, and currency risks that sit between now and normalised earnings.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and financial projections are subject to market conditions and various risk factors. These statements are speculative and subject to change based on market developments and company performance.