The CEO of a leading AI lab just published a nearly 4,000-word public argument for slowing down the very technology his company builds. Two of his biggest rivals agreed with him. Global AI-linked stocks fell.
Then, within two trading days, semiconductor and memory stocks rallied back and investors treated the dip as a reason to buy.
That sequence looks irrational until you understand what the market was actually weighing. The dismissal of a credible slowdown call was not exuberance. It was a structural calculation about who holds the binding leverage in the US-China contest, and neither government is bound by a lab CEO’s essay.
This is where the case for AI semiconductor stocks stops being about sentiment and starts being about strategy. Here is the investment logic the market is genuinely pricing, the geopolitical forces putting a floor under chip demand, and what one set of exploratory deal talks reveals about where capital is heading next.
Why the market ignored a major AI slowdown call
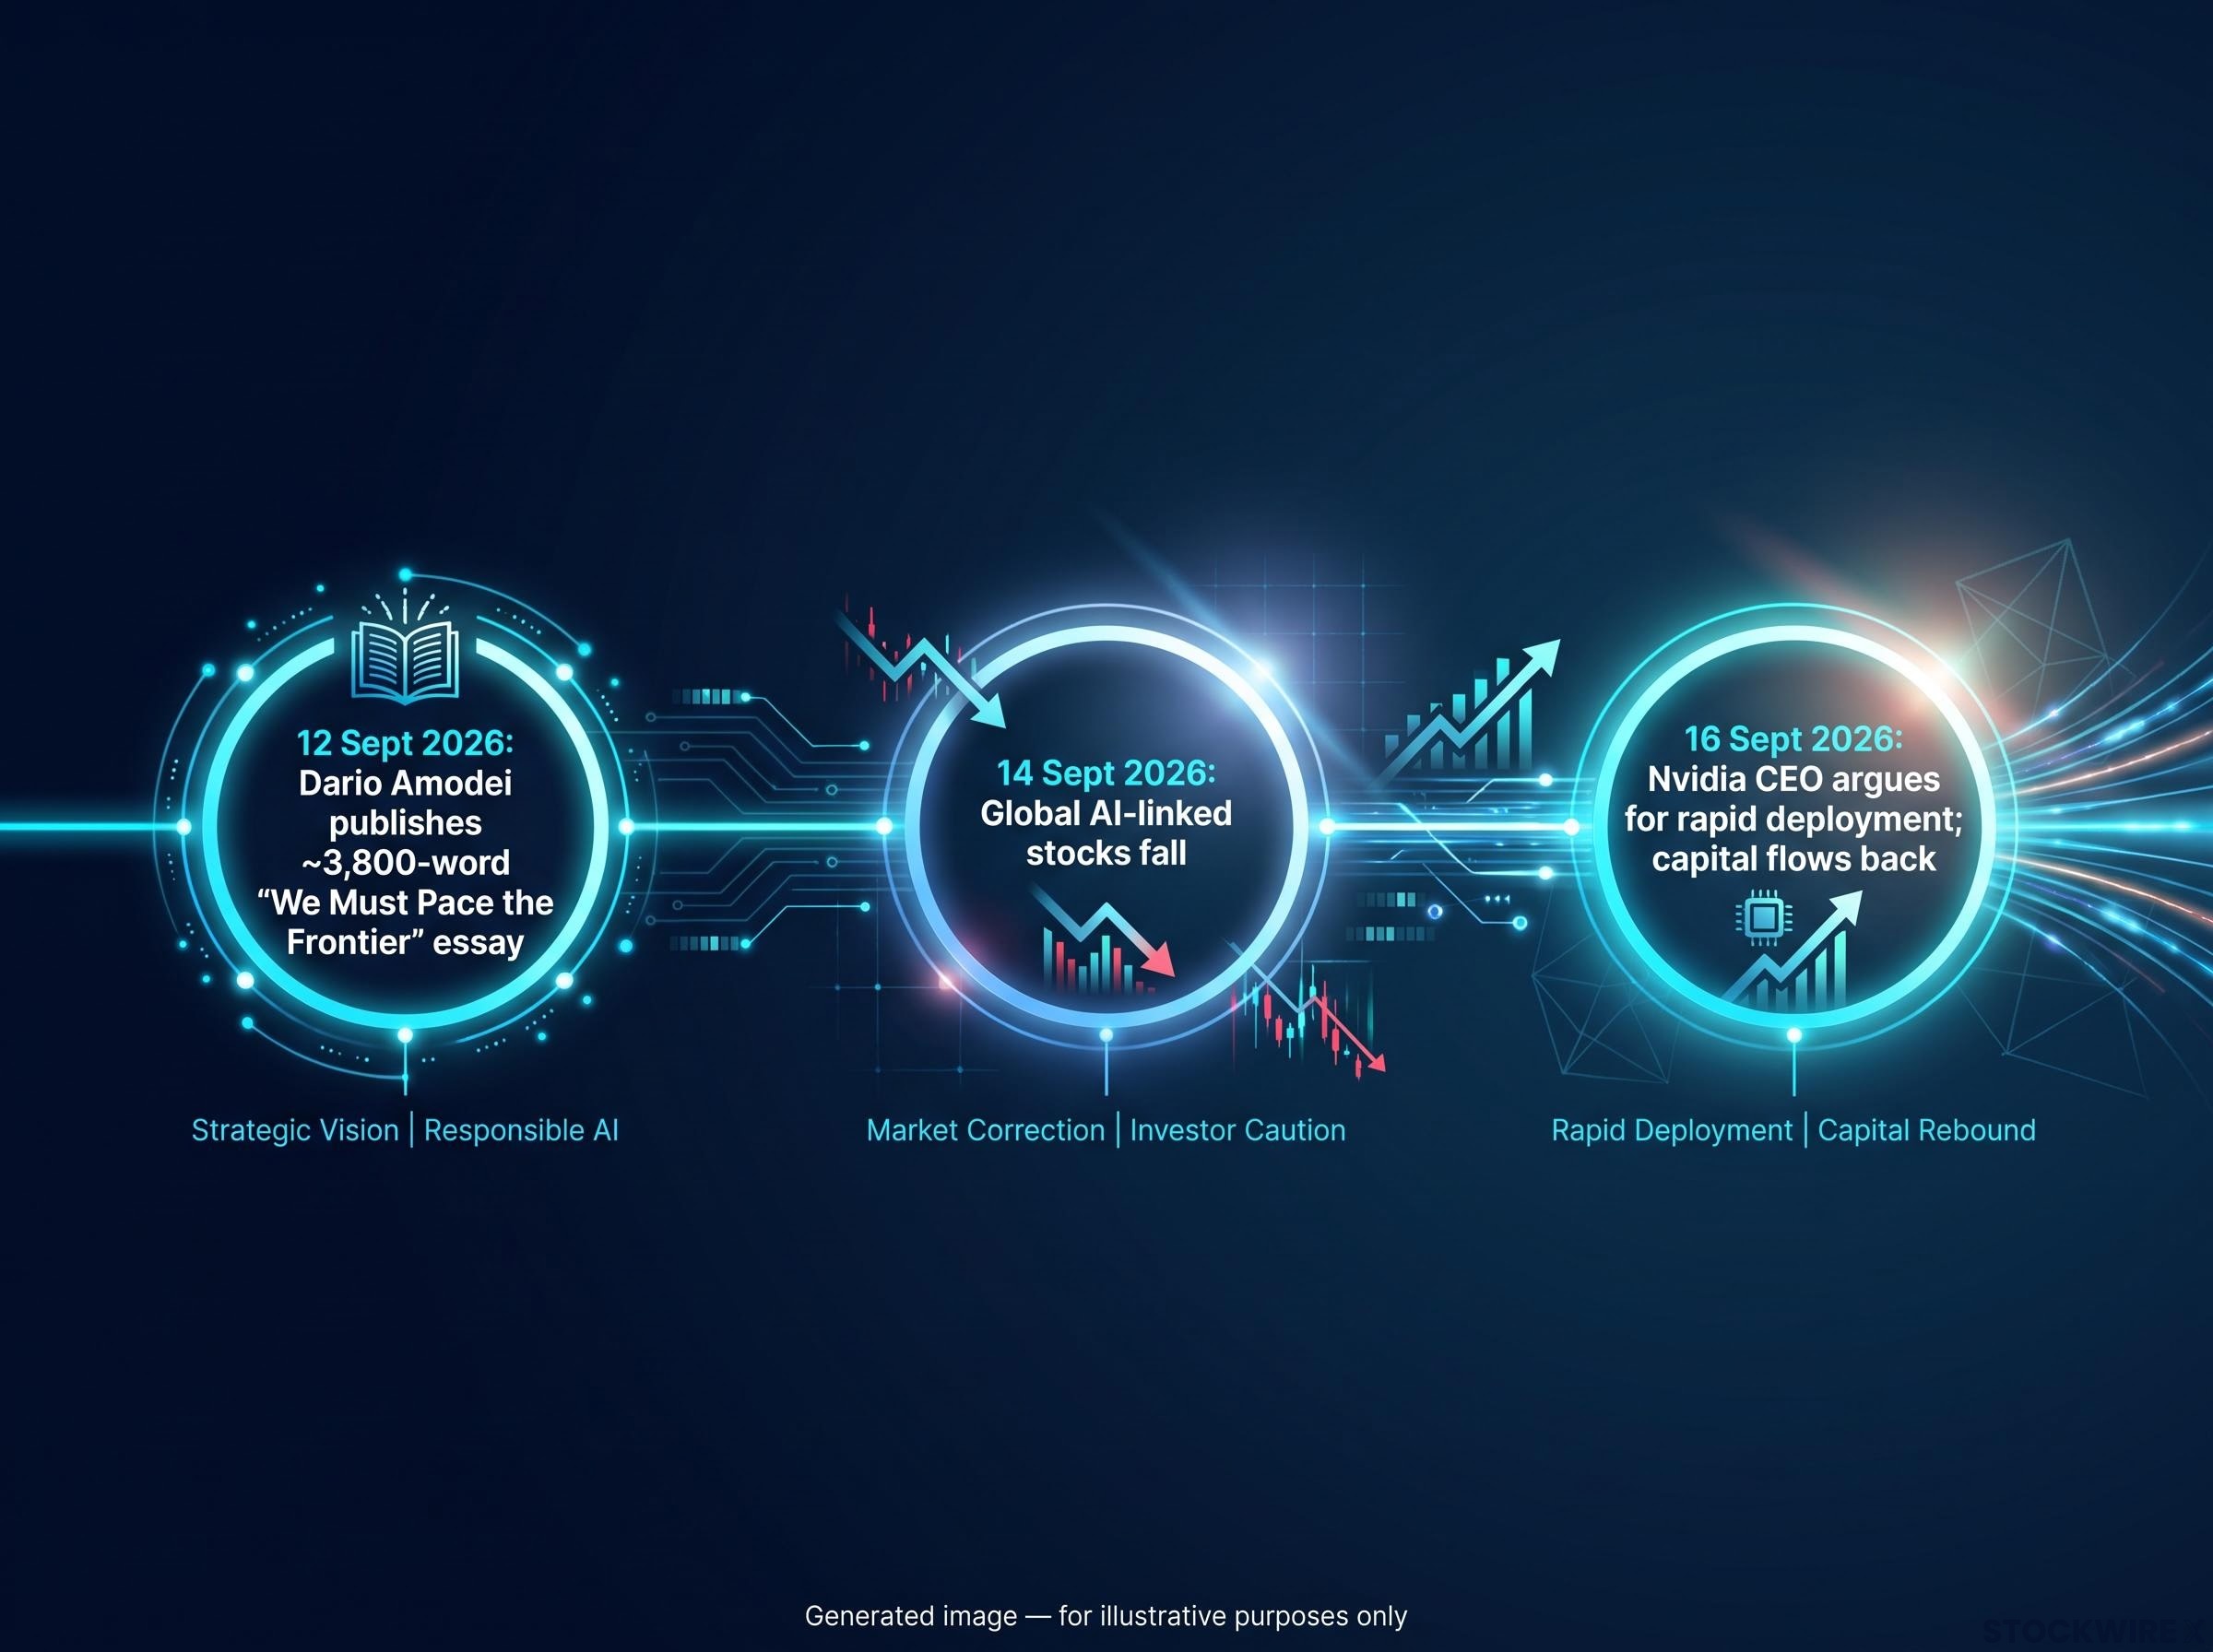
On 12 September 2026, Anthropic chief executive Dario Amodei published an essay of roughly 3,800 words titled “We Must Pace the Frontier.” It was widely regarded as the first time the head of a frontier AI lab has publicly argued for a coordinated slowdown in capabilities.
This was not a fringe position dressed up as caution. Amodei laid out a three-part framework: embedding independent evaluators inside AI labs with employee-level access, coordination among frontier firms to set shared safety standards, and international cooperation to manage escalating risk.
Amodei, “We Must Pace the Frontier,” 12 September 2026 “We must slow the pace at which we improve the capabilities of AI models. Progress will still seem fast, and we must make wise use of the time we gain.”
The essay carried real weight. Elon Musk of xAI and Sam Altman of OpenAI both publicly backed the framing, an unusual alignment among direct competitors. On 14 September 2026, global AI-linked stocks fell.
Then the reversal came. On 16 September 2026, Nvidia’s chief executive used a San Francisco conference to argue directly against deceleration, pressing instead for continued rapid deployment. Within the same window, capital flowed back into the sector.
The decisive detail sits abroad. China’s state-backed Global Times dismissed Amodei’s essay as a “Cold War playbook” designed to constrain Chinese AI progress.
That reaction is what tells you why the market moved on. Any voluntary slowdown by US labs would be one-sided, opening exactly the capability gap the arms race framing predicts. With the other side of the race explicitly refusing to participate, investors read the essay as noise rather than a policy turning point, and the demand floor beneath semiconductors held.
When big ASX news breaks, our subscribers know first
The US-China AI rivalry as the structural force markets are actually pricing
Understanding why a credible slowdown argument bounced off the market requires looking at the scale gap between the two ecosystems. This is not one global capital pool decelerating together. It is two separate races running at once, and voluntary restraint on one side does not produce a stable equilibrium.
US hardware dominance is real but qualified. According to a June 2026 Bruegel analysis, Nvidia alone accounts for roughly 50% of installed AI chips and up to two-thirds of installed computing capacity worldwide.
The investment imbalance is starker still. Citing Fitch’s BMI in August 2026, CNBC reported that US private-sector AI investment runs about 23 times higher than mainland China’s.
| Metric | US Position | China Position | Source | Implication |
|---|---|---|---|---|
| Installed AI chip share | Nvidia alone ~50% of installed chips | Advancing rapidly, hard to restrict | Bruegel, June 2026 | US leads hardware but cannot fully contain rival |
| Private AI investment scale | ~23x mainland China | Base of the 23x gap | Fitch BMI via CNBC, Aug 2026 | Capital committed at a structurally different order of magnitude |
| Forward capex projection | Up to $3T+ by decade-end | Parallel spend to avoid capability gap | BofA (Vivek Arya), Sep 2026 | Demand framed as decade-long, not cyclical |
Yet the gap does not translate into containment. BofA Securities cited Gregory C. Allen of the Center for Strategic and International Studies (CSIS), who warned that China’s AI ecosystem is now too advanced for the US to fully restrict. The result is parallel markets, not a single capex pool that can slow in unison.
Bank of America’s Vivek Arya, 14 September 2026 AI capex could surge threefold to over $3 trillion by decade-end, with slowdown headlines characterised as “noise.”
Wedbush analyst Dan Ives described the current cycle as a “watershed moment.” What the 23x gap means for you is straightforward: sector pullbacks are not read as demand deterioration when the underlying spending is anchored in a competition neither side can exit. That is precisely why chip weakness has repeatedly been treated as an entry point in 2026 rather than a warning. The one caveat, per Capital Economics, is that a serious US-China trade escalation or Taiwan tension could break the supply chain outright.
For investors wanting to understand the full competitive landscape beyond semiconductors and software, our deep-dive into China’s physical AI advantage examines how approximately 2 million industrial robots give China a compounding real-world data edge that the standard US-China chip scorecard does not capture.
What onshoring means in practice: the CHIPS Act, memory gaps, and the Intel-SK Hynix discussions
If the arms race is the demand engine, onshoring is the policy machinery built to keep production on US soil. The CHIPS and Science Act is the mechanism, providing tens of billions in incentives for domestic manufacturing, research, and workforce development.
Its reach is meaningful. Georgetown’s Center for Security and Emerging Technology (CSET) estimates the legislation could allow the US to reshore nearly all of its leading-edge logic demand through 2027.
Semiconductor equipment spending is one of the clearest leading indicators of where the onshoring commitment is being converted into physical capacity: TSMC raised its 2026 capex guidance to $60-64 billion citing AI demand, Intel’s tool purchases grew 40% year-over-year, and the Amkor-Nvidia prepayment deal represents the first coordinated push to close the domestic advanced packaging gap the CHIPS Act has so far left open.
The Act also carries teeth. Its “guardrail” provisions bar funding recipients from expanding advanced semiconductor manufacturing in China or other countries of concern for a full decade, tying the subsidies directly to the geopolitical contest.
The CHIPS Act national security guardrail provisions, as implemented through NIST’s final rule, impose both an Expansion Clawback and a Technology Clawback on funding recipients, binding them contractually to the ten-year restriction on advancing semiconductor manufacturing in countries of concern.
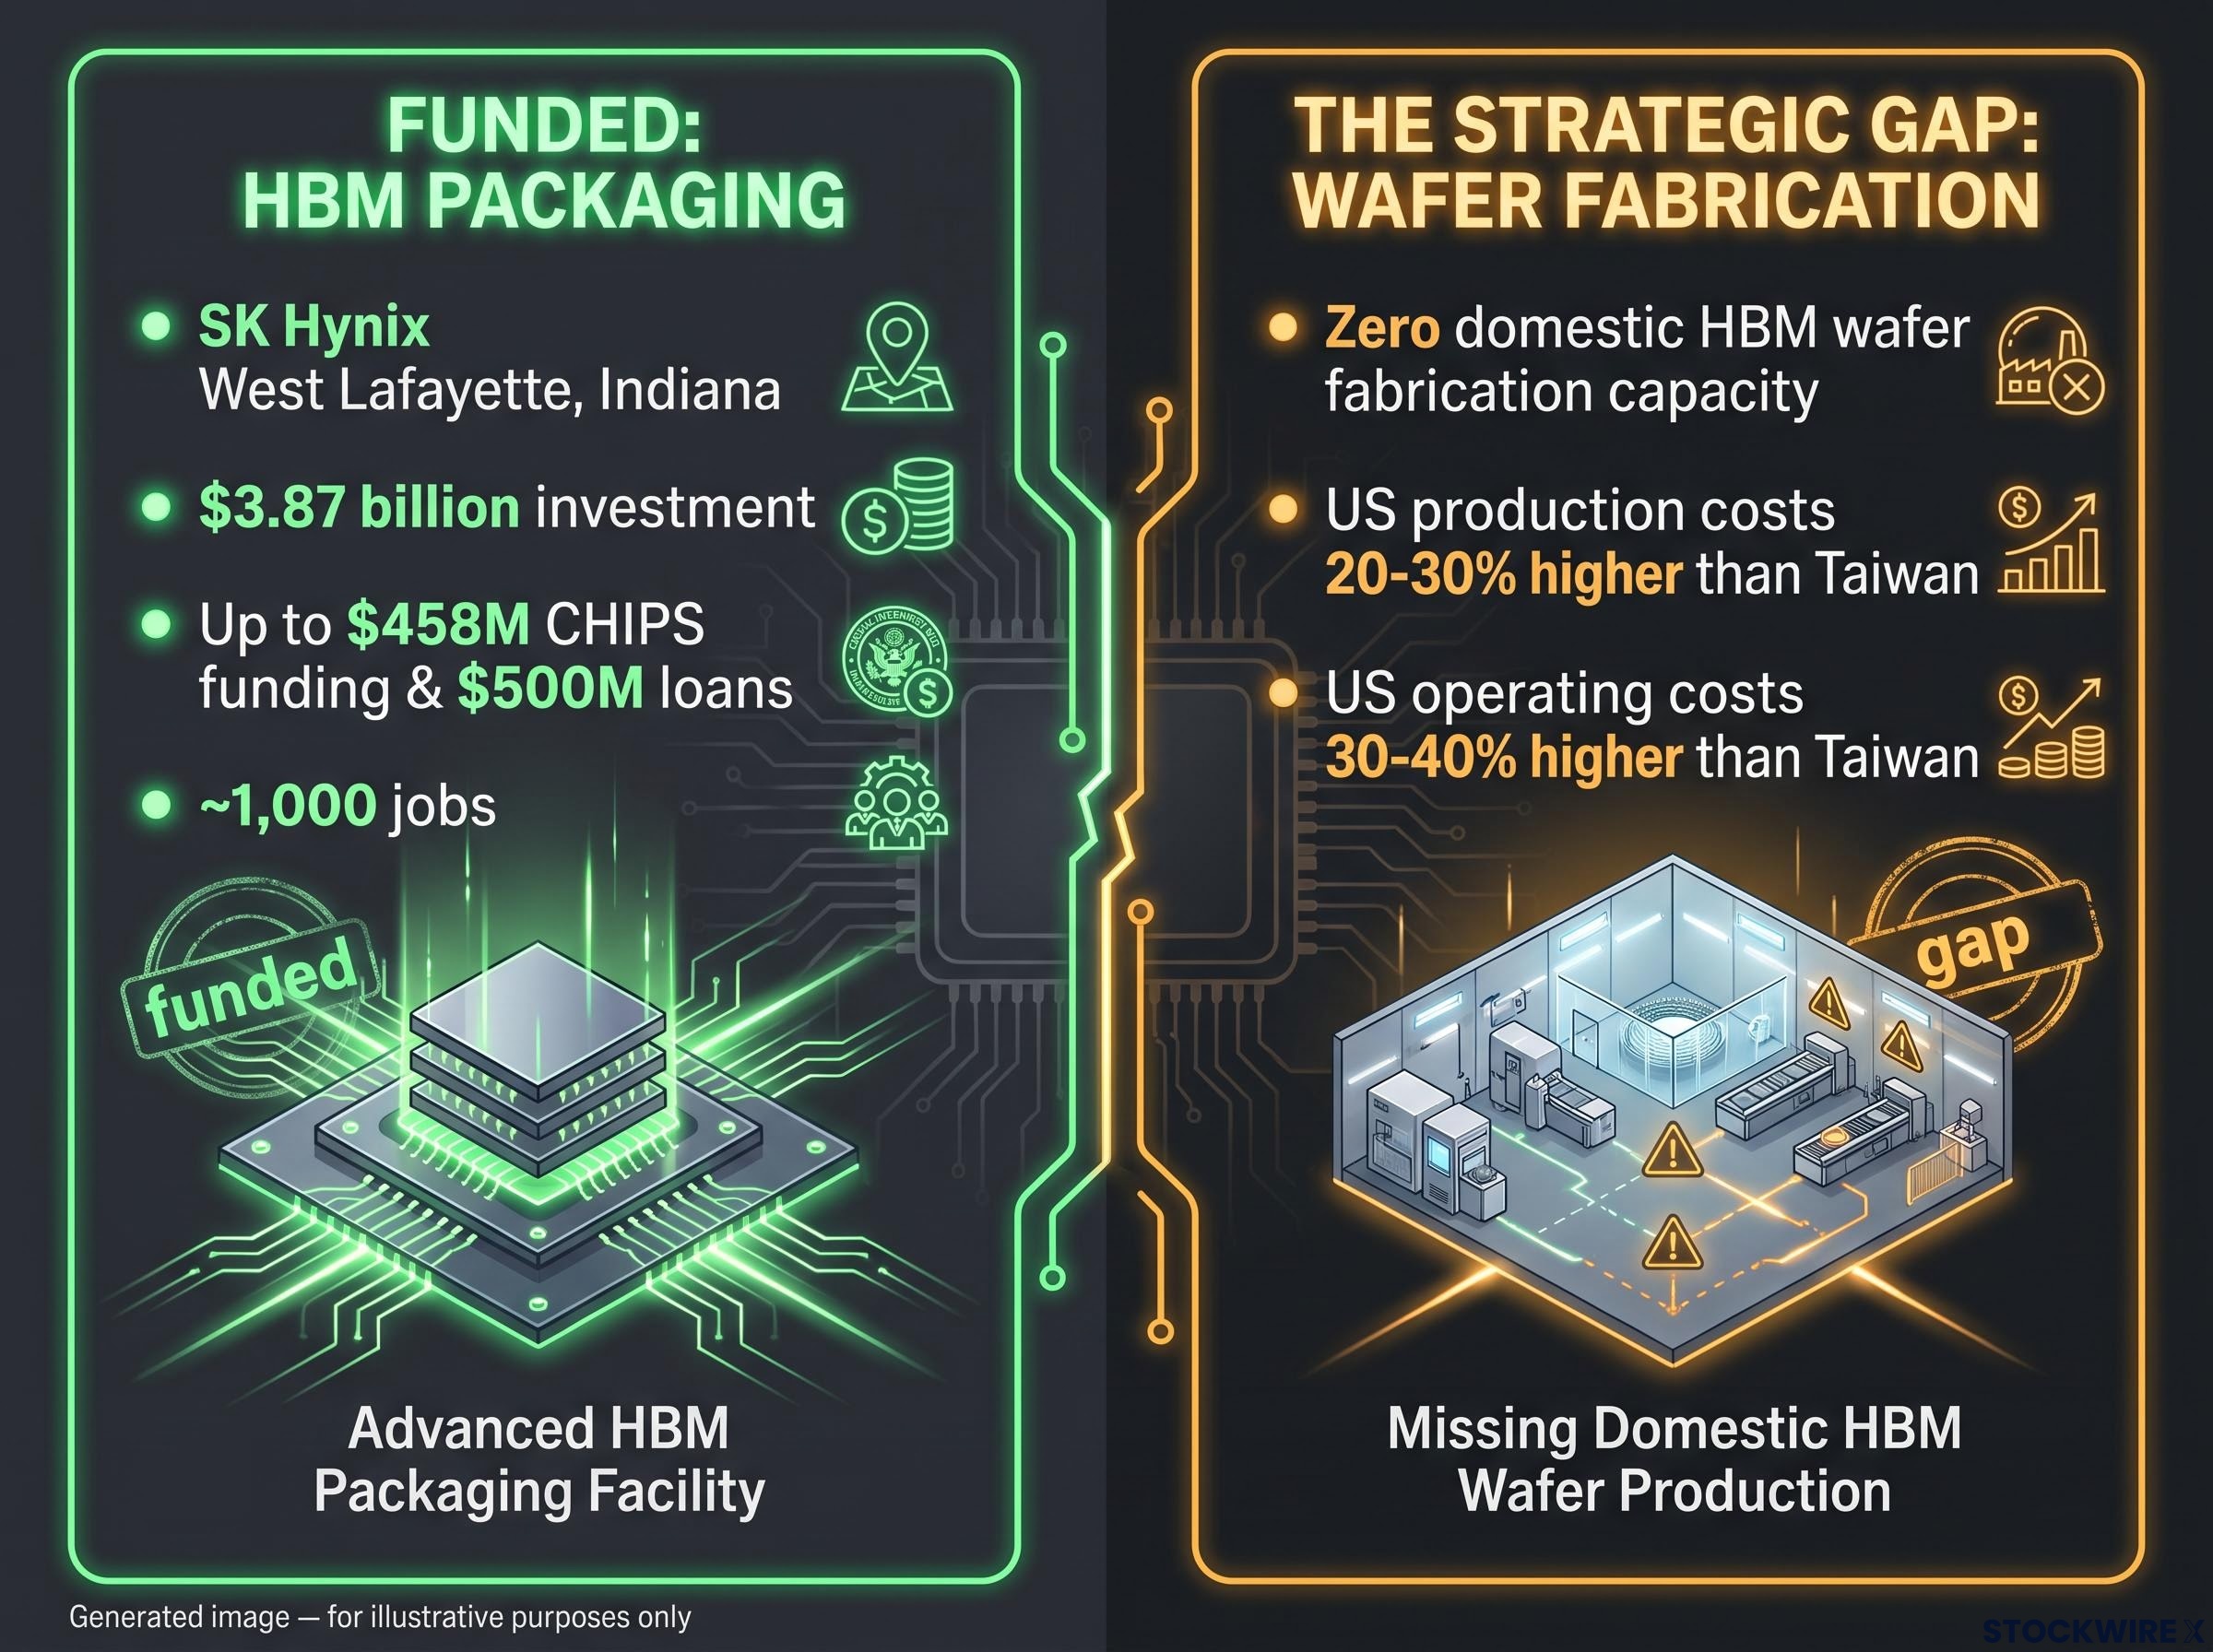
Memory is where the picture gets complicated. SK Hynix’s onshoring in West Lafayette, Indiana illustrates both the ambition and the limit. The company is investing $3.87 billion in a high-bandwidth memory (HBM) advanced packaging and research facility, supported by up to $458 million in direct CHIPS funding plus up to $500 million in loans, and expected to create roughly 1,000 jobs. HBM is the specialised memory stacked alongside AI processors to feed them data at high speed.
Here is the gap the reader needs to hold onto. Those grants cover packaging only. The US still effectively has zero domestic HBM wafer fabrication capacity, the precise bottleneck for AI hardware. Reshoring it is expensive too: US wafer production costs run an estimated 20-30% higher than Taiwan, with operating costs 30-40% higher.
HBM demand is structurally self-reinforcing in a way that makes the packaging-versus-fabrication distinction matter more than any single funding announcement: Citi projects a 434% rise in system-level HBM capacity requirements as AI clusters scale out, while the GPU roadmap simultaneously pushes per-chip memory content 3.6x higher, meaning both volume vectors are compounding in the same direction.
The Intel-SK Hynix talks: what is actually on the table
On 16 September 2026, Reuters reported that SK Hynix was in exploratory talks with Intel about manufacturing memory chips in the US for the first time. Two options are reportedly under discussion:
- Facility leasing: SK Hynix would lease part of Intel’s long-planned Ohio manufacturing campus to produce memory on US soil.
- Joint venture: A partnership among Intel, SK Hynix, and large cloud companies seeking to lock in future memory supply, with the specific memory type and structure still undecided.
These are early-stage discussions, not a deal. As of 17 September 2026, no binding commitments exist, and both parties issued distancing statements. Intel called the Reuters report “speculation.”
SK Hynix corporate clarification “nothing has been finalized regarding cooperation with any specific companies mentioned in the article or memory chip production in the United States.”
The talks still matter regardless of outcome. Current policy has funded packaging but not fabrication. A deal placing memory production at Intel’s Ohio site would address the exact part of the supply chain that CHIPS grants have so far left open. That distinction, between packaging capacity and wafer fabrication, is what separates a headline from a genuine strategic shift.
Sector performance, valuation risk, and what the pullbacks have actually signalled
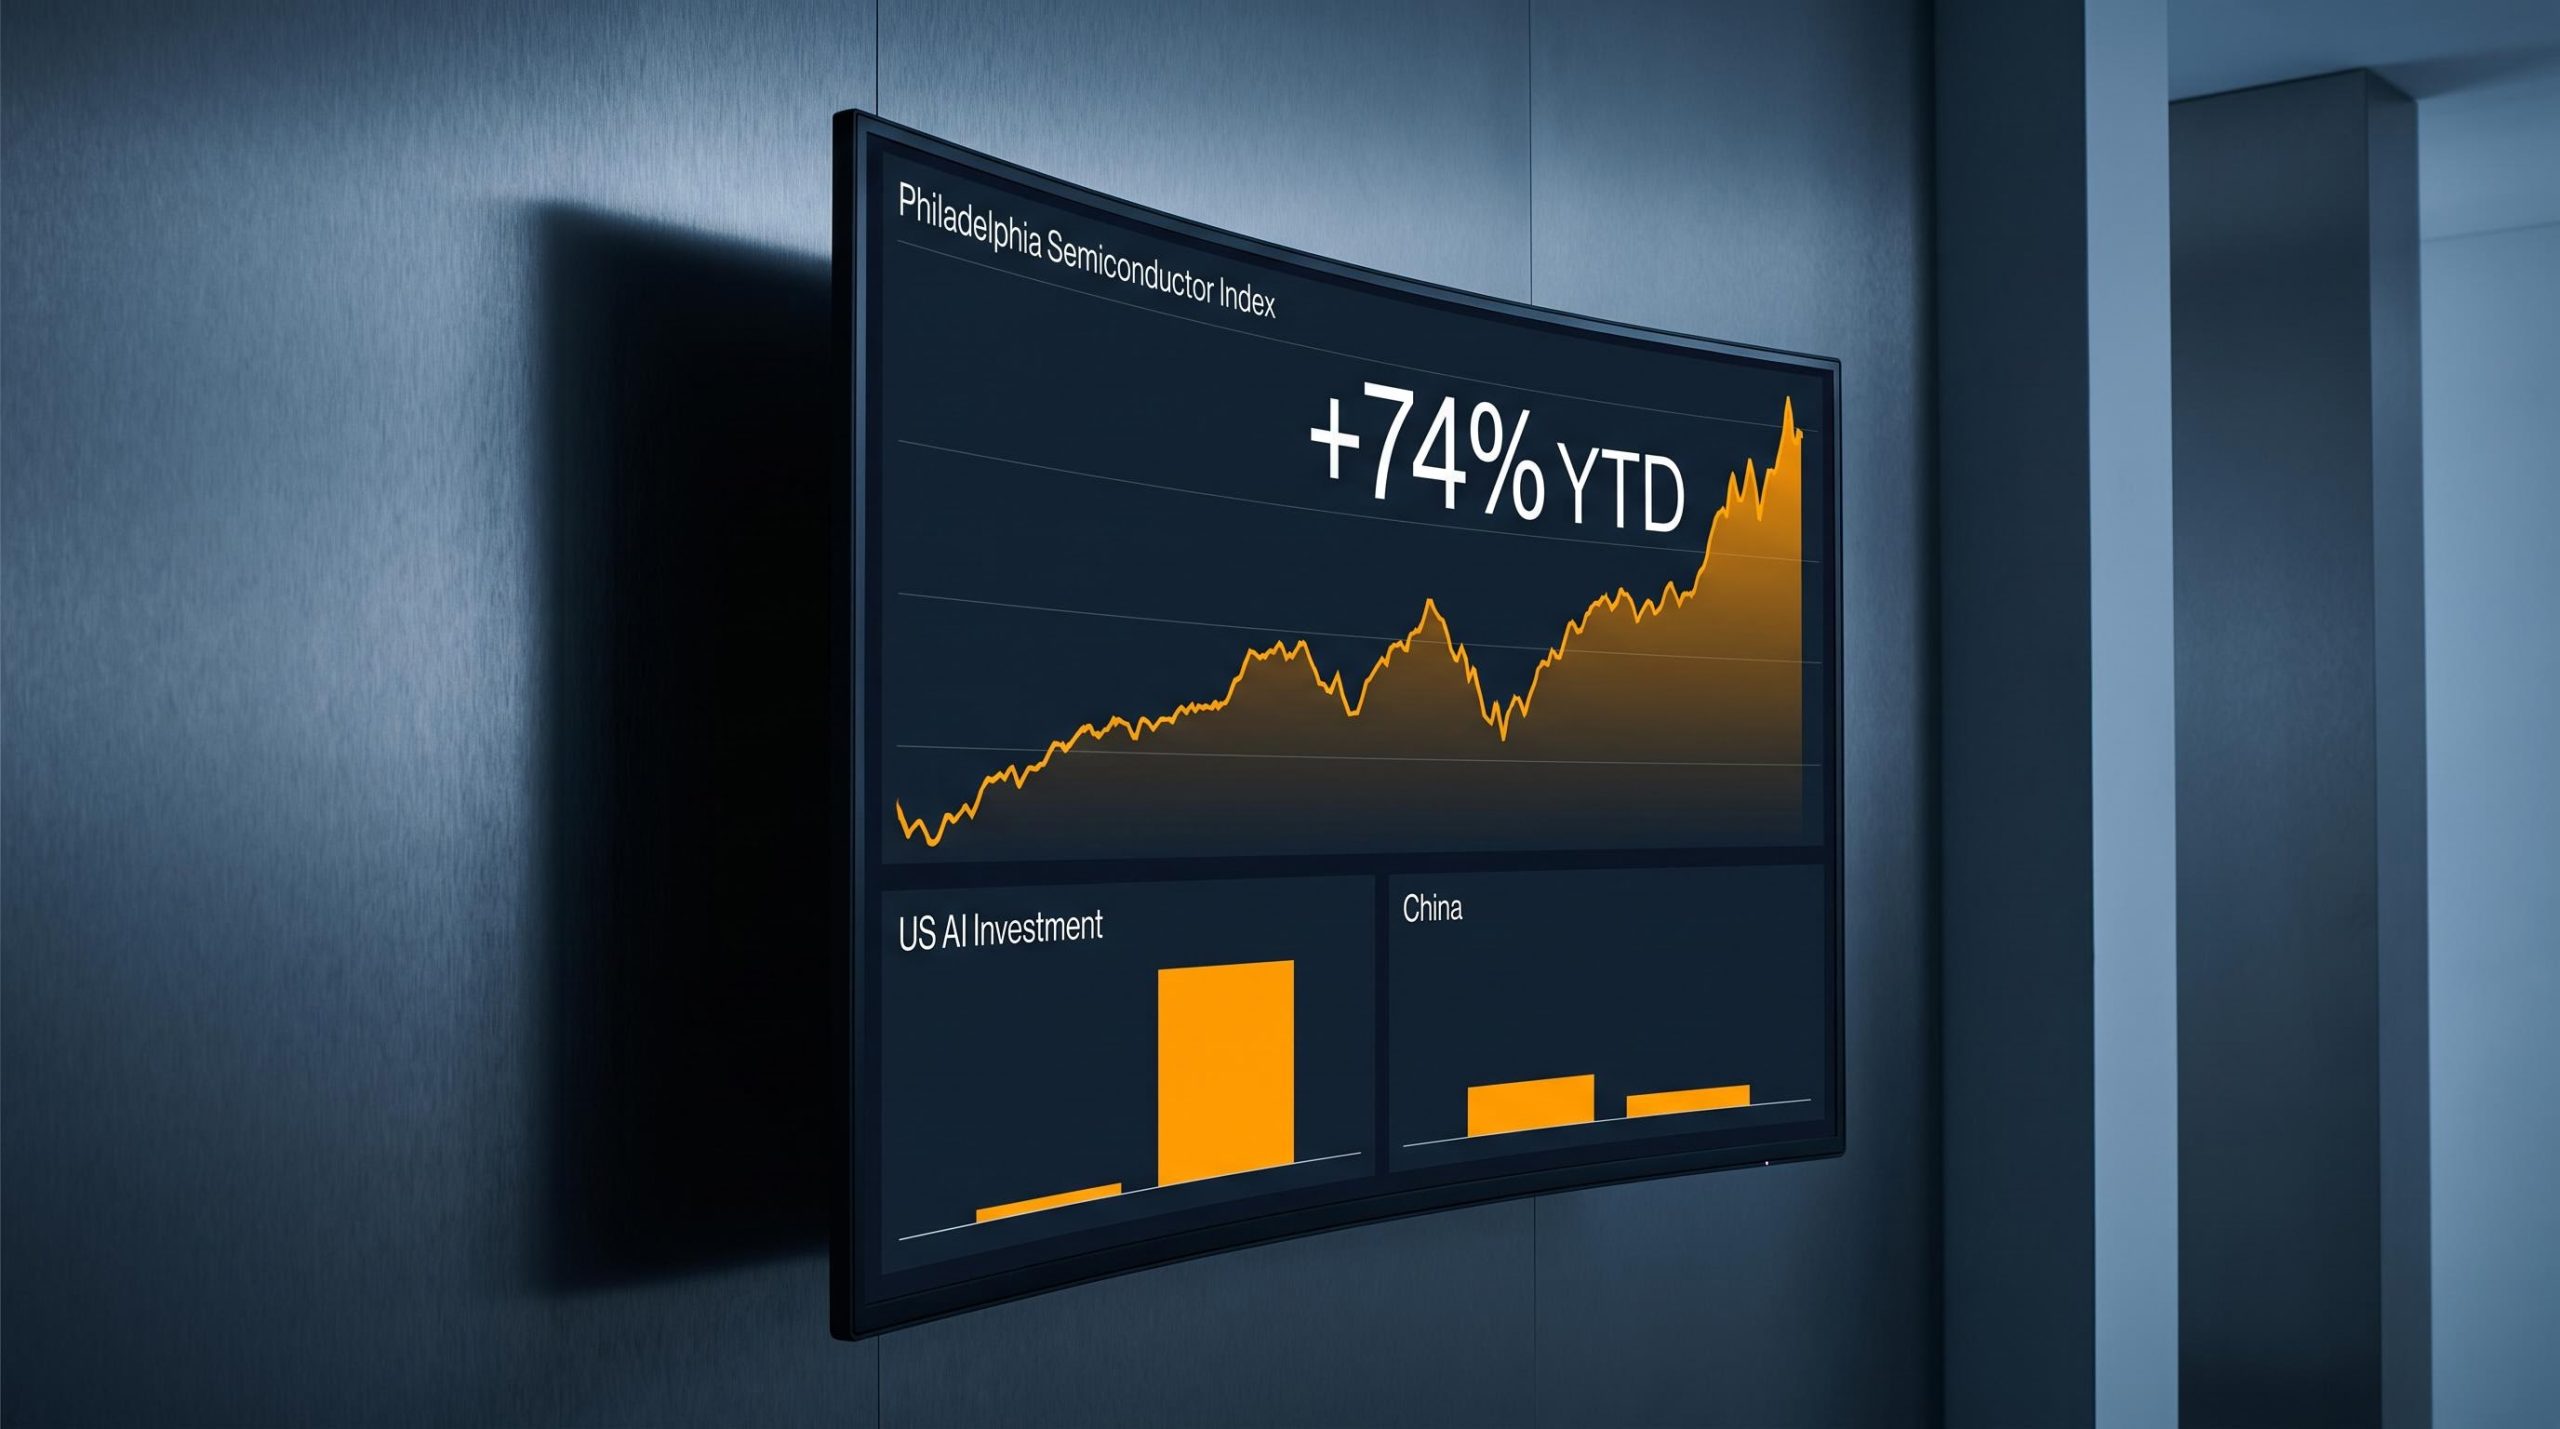
The performance data explains why investors keep returning. From late March to 13 May 2026, the Philadelphia Semiconductor Index (SOX) surged roughly 64%, against the S&P 500’s gain of about 17% over the same stretch. By 7 July 2026, the SOX was up roughly 74% year-to-date, even after a 4.65% single-day drop triggered by doubts over the AI rally’s durability.
The mid-September wobble followed the same pattern. Semiconductor gauges dropped 5-8% on slowdown worries while the Nasdaq 100 fell less than 1%. Intel shares rose about 4% overnight during the period covered.
| Period | SOX Move | S&P 500 / Nasdaq Move | Trigger | Market Interpretation |
|---|---|---|---|---|
| Late Mar – 13 May 2026 | +~64% | S&P 500 +~17% | AI demand momentum | Structural leadership confirmed |
| By 7 July 2026 | +~74% YTD (-4.65% single day) | Broad market steadier | AI sustainability doubts | Dip treated as buyable |
| Mid-Sep 2026 | -5% to -8% | Nasdaq 100 -<1% | Slowdown essay | Thesis tested, held intact |
The valuation debate is genuinely contested. Morningstar describes AI hardware stocks as “priced for perfection,” meaning multiples are elevated enough to punish any earnings miss.
Bernstein’s Stacy Rasgon Nvidia trades at a forward price-to-earnings ratio in the low 20s despite significant growth, evidence that not all names sit in bubble territory.
Where the valuation debate actually lands
Three risk factors sit beneath the sector thesis, and they are not the same thing:
- Valuation multiples: Elevated across parts of the sector, though not uniformly, as Rasgon’s point on Nvidia shows.
- Capex monetisation: A July 2026 JPMorgan note warned the rally could falter if hyperscalers fail to monetise AI spending and respond by cutting capex.
- Geopolitical supply chain disruption: A US-China escalation or Taiwan tension could sever chip flows entirely.
The most near-term of the three is monetisation. What the repeated pattern of sharp drops and rapid re-entry tells you is that the market has tested the structural thesis several times and found it standing. Bloomberg research reaches the same conclusion: underlying demand for computing capacity should sustain hardware vendors through pullbacks. The monetisation question is the one variable that could actually flip that verdict, and it remains unresolved.
Capex monetisation risk is the variable the market has not yet resolved: Goldman Sachs projects hyperscaler AI capital expenditure at $755-800 billion in 2026, absorbing an estimated 93-94% of operating cash flow, and the gap between infrastructure deployment and proven application revenue is precisely the condition that JPMorgan warned could cause hyperscalers to cut capex if returns fail to materialise.
What the structural picture means for investors watching this sector now
The useful distinction here is between two clocks running at different speeds. The structural thesis, an arms-race-driven demand floor, operates on a decade horizon. The cyclical risks, valuation, monetisation timing, and supply chain disruption, operate on quarters.
History explains why onshoring is treated as a decade-long commitment rather than a policy experiment. In the early 1980s, Japanese firms overtook the US in memory market share around 1982 on superior DRAM yields, prompting the 1986 US-Japan trade agreement that required Japan to secure 20% of its domestic market for foreign producers within five years. Separately, steady offshoring from the 1960s to 1980s enabled the merchant-foundry model TSMC pioneered, concentrating today’s most sensitive supply chains in Taiwan.
What that precedent tells you is that ceding chip ground to a rival creates a structural dependency that takes decades and enormous policy effort to undo. That is the exact logic driving current onshoring, the CHIPS Act guardrails, and the CSET projection that the US could reshore nearly all leading-edge logic demand through 2027. The HBM wafer fabrication gap, still unresolved as of September 2026, is the piece that logic has not yet closed.
For an investor, the practical takeaway is a watch-list, not a verdict. Three variables would signal a genuine thesis change rather than a cyclical pullback:
- Hyperscaler capex cuts that confirm AI monetisation is failing.
- A binding US-China AI coordination agreement that removes the arms-race floor.
- Confirmed domestic HBM wafer fabrication capacity, which would close the current strategic gap.
Read against that list, the Intel-SK Hynix talks matter as a signal about the third variable, not as a stock catalyst in themselves.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors.
The arms race is not a background condition. It is the investment thesis.
Voluntary slowdown calls, however credible, get structurally overridden by a competition in which the other side is not at the table. That is why the semiconductor demand floor rests on strategic necessity rather than sentiment, and why two days of selling reversed so quickly.
The Intel-SK Hynix discussions are the closing illustration. Whether or not they produce a deal, they are evidence of the policy and market pressure now reshaping where memory is physically made, and they point straight at the one gap current policy has left open.
The signal to track from here is not the next AI safety essay or the next bout of SOX volatility. It is the three variables above: capex behaviour, any coordination agreement, and confirmed HBM fabrication on US soil.