Cleveland Fed President Beth Hammack said on Thursday, 12 November 2026, that inflation is moving “in the wrong direction” and that the Federal Reserve needs gradual, steady increases to reach a restrictive stance. A restrictive stance means rates high enough to actively slow spending. The dollar was already moving: the US Dollar Index (DXY), which tracks the greenback against a basket of major currencies, rose to roughly 103.02, its highest level since April 2025.
Hammack heads a regional reserve bank. She is not a Washington-based governor. She has already put her view on record: at the 28 October meeting she dissented in favour of a 25 basis point hike when the Federal Open Market Committee (FOMC) held its target range at 3.75%-4.00% by a 10-2 vote. A basis point is one hundredth of a percentage point.
The next meeting runs 8-9 December. A hike there would feed into mortgage and corporate borrowing costs, the dollar and the pricing of almost every asset in your portfolio.
Markets have already priced much of the next move. The sections below set out how that pricing works, why one regional president wants small steps instead of big ones, and where the real disagreement inside the Fed sits.
Why the dollar hit a 19-month high before the Fed has moved
No vote has been taken, yet the dollar has already repriced. According to Reuters, the DXY rose 0.15% on 12 November and posted its largest two-day gain in five months. Another report put the index at 102.85, so the level is best read as roughly 103.
Traders now assign roughly 80%-90% odds to a quarter-point increase in December. Governor Christopher Waller has said he leans towards a 25 bp hike, and Goldman Sachs forecasts 25 bp in December and another in March 2027.
The latest dollar index strength builds on an October peak near 102.54, supported by Fed-driven yields, energy-led inflation and relative US growth, three pillars that a December hike would test.
How hawkish signals move currencies
When markets expect higher US rates, dollar assets offer better returns. Global capital flows in to capture them, and the extra demand for dollars lifts the currency. A speech that makes a hike more likely moves the dollar the same way a hike would, only sooner.
Balance sheet policy works the same way. Quantitative easing (QE), in which the Fed creates money to buy bonds, usually weakens the dollar, while quantitative tightening (QT), in which it lets those bonds mature without replacing them, usually supports it.
What stocks, bonds and gold usually do
| Asset | Typical reaction to tightening | Why | Current backdrop |
|---|---|---|---|
| US dollar | Strengthens | Higher expected returns attract capital | DXY near 103, a 19-month high |
| Growth and tech shares | Most sensitive to falls | Higher discount rates cut the value of future earnings | Hike odds at 80%-90% |
| Treasuries | Yields rise, prices fall | Tightening is priced into new bonds | December hike largely expected |
| Gold | Usually pressured | Pays no interest and is priced in dollars | Firmer dollar and higher real yields |
The 2013 taper episode shows how far expectations alone can travel. After the Fed hinted at slowing its bond purchases, the S&P 500 fell about 8% and the 10-year Treasury yield climbed from about 2% to 3%, all before anything changed.
For you, the implication is timing. If you wait for the December decision before reassessing dollar or rate-sensitive exposure, much of the repricing may already be done.
What is behind Hammack’s call for gradual increases?
Hammack’s case starts with the Fed’s dual mandate: maximum employment and stable prices, with inflation targeted at 2%. She argues the Fed has done well on jobs but has missed on inflation for years. Speaking in Columbus, as reported by Bloomberg and FXStreet, she said:
“Inflation is moving in the wrong direction.”
Her reasoning rests on four points:
- Broadening price pressures, reflecting both supply and demand
- Strong demand, particularly investment tied to artificial intelligence
- The risk of an “inflationary mindset” taking hold
- A “static” labour market that she would not call especially healthy
The numbers back the diagnosis.
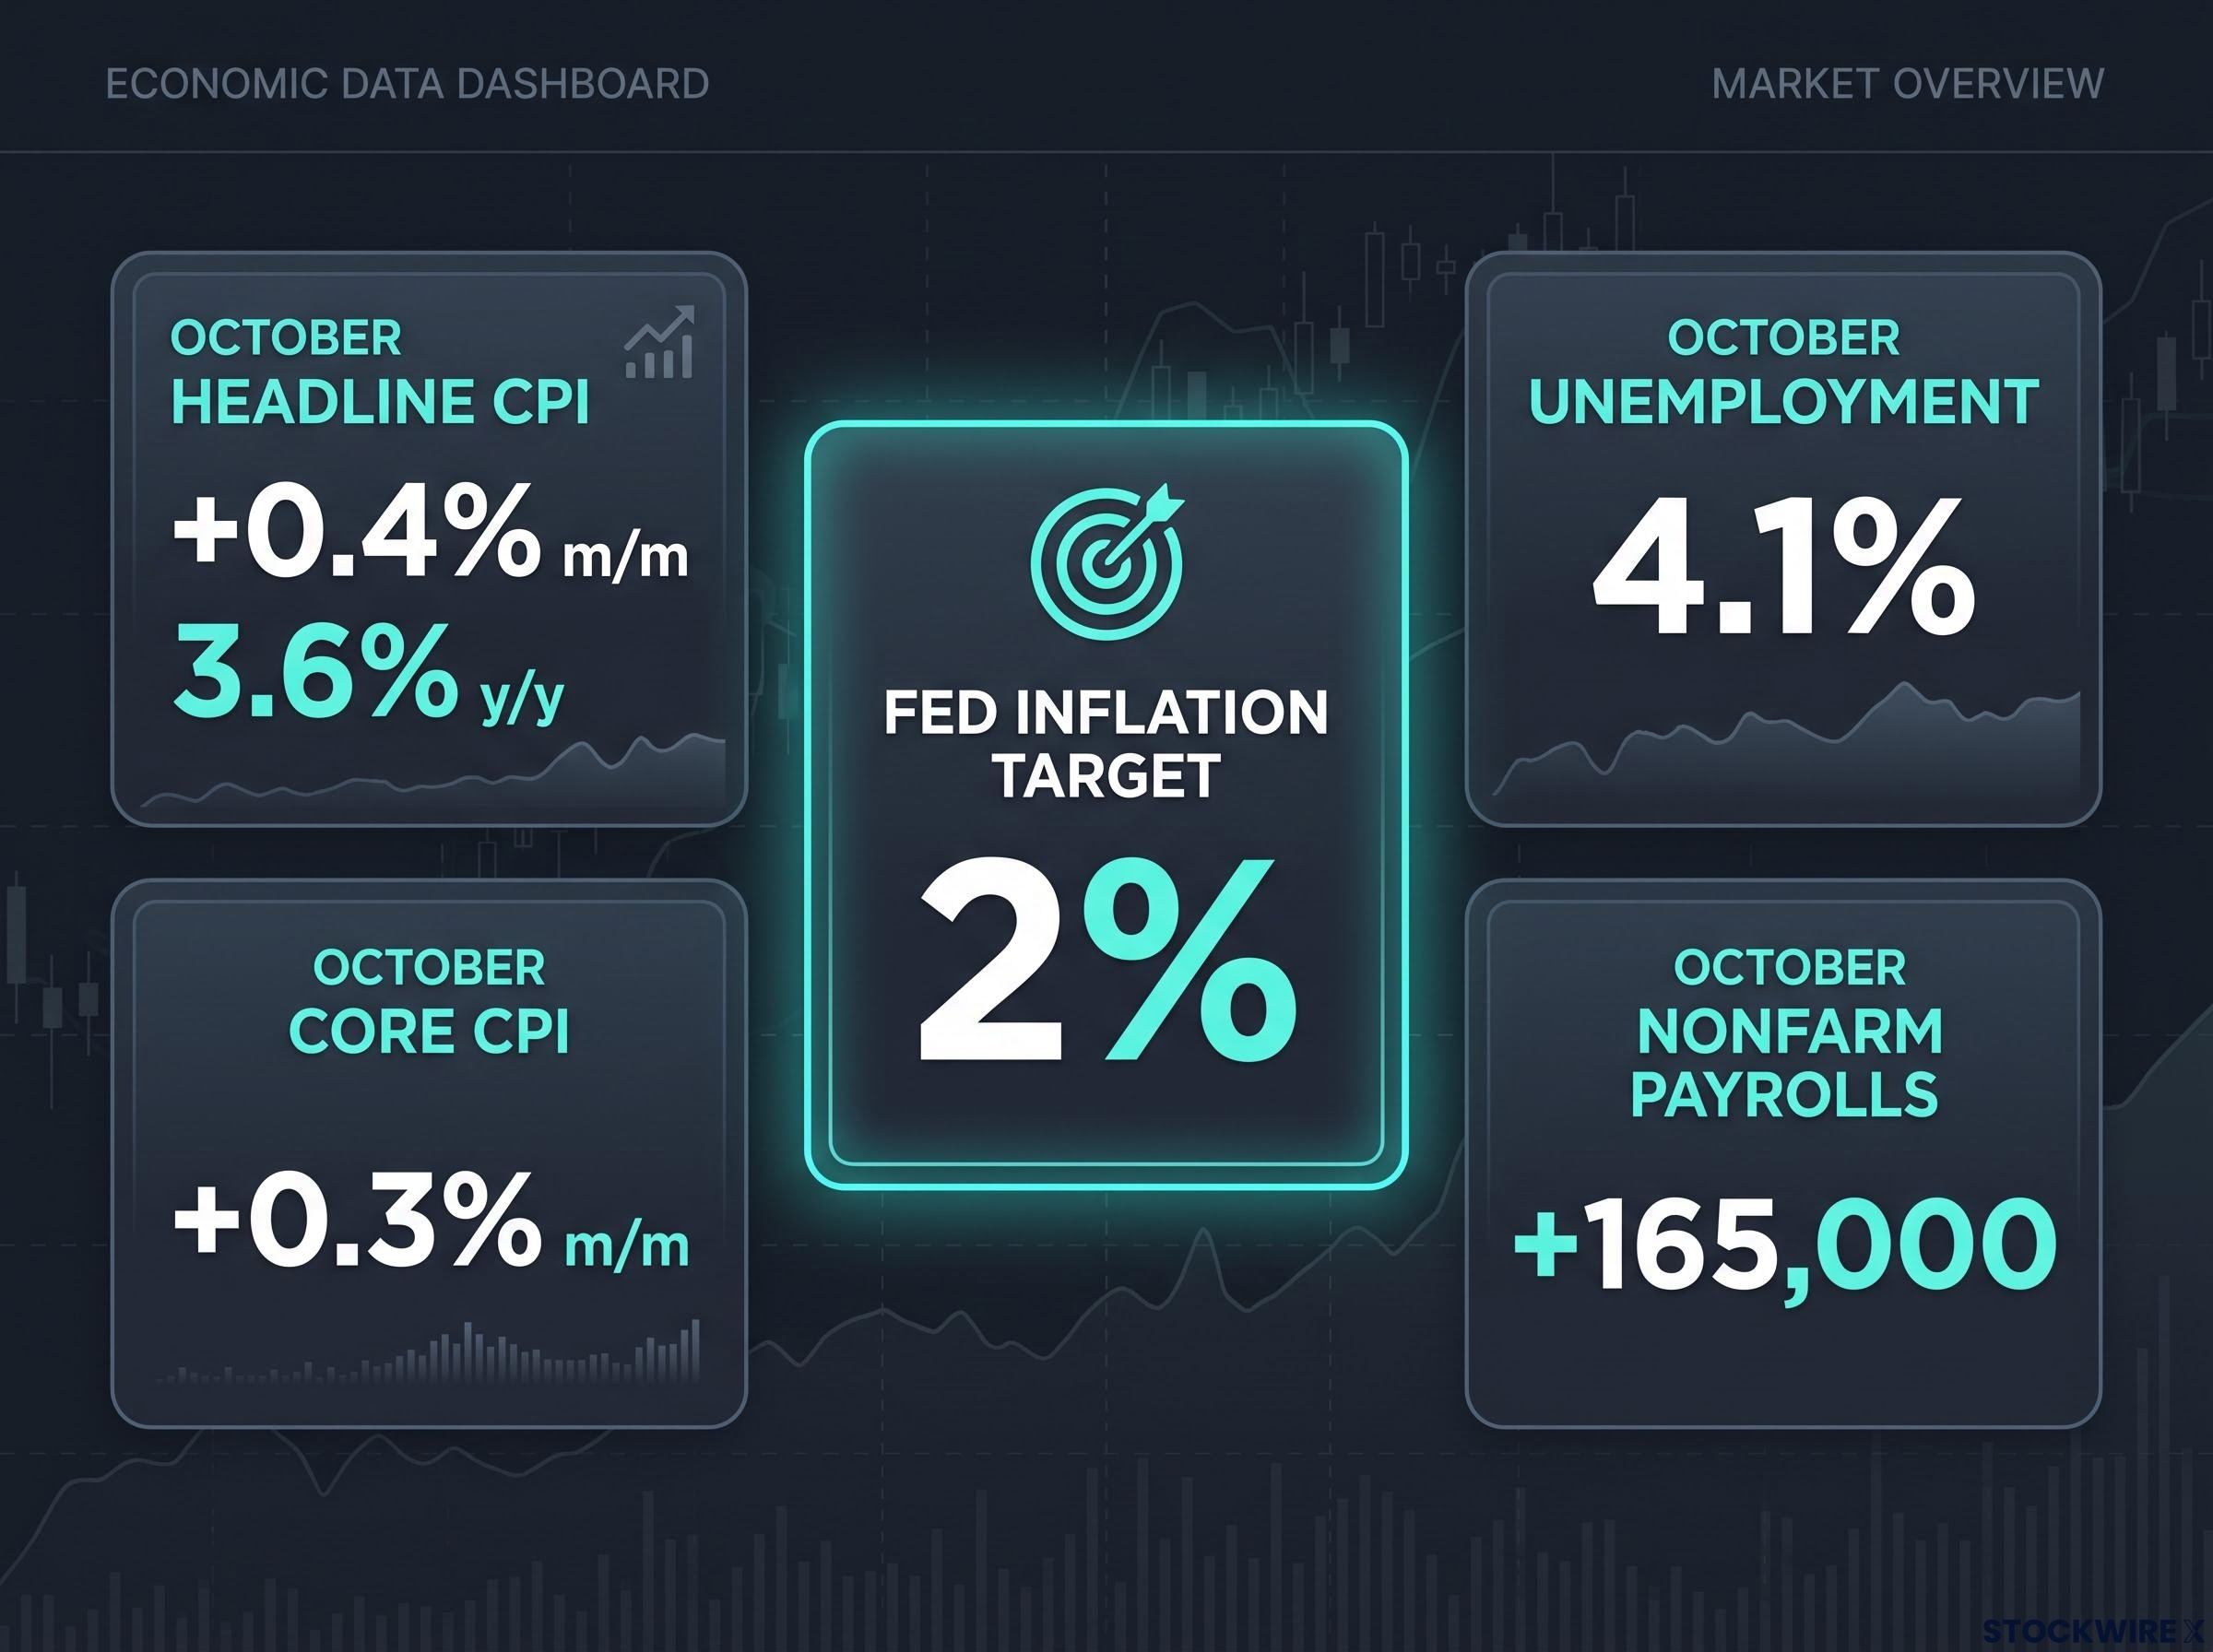
Key October data like 4.1% unemployment and +165,000 payrolls support the case for further action toward the 2% Fed inflation target.
| Indicator | Latest reading | Source | Date |
|---|---|---|---|
| Headline CPI, October | +0.4% m/m, about 3.6% y/y | BLS | 10 November 2026 |
| Core CPI, October | +0.3% m/m | BLS via CNBC | 10 November 2026 |
| PCE, September | Headline 3.6%, core 3.1% y/y | BEA | 29 October 2026 |
| Unemployment, October | 4.1% | BLS | 6 November 2026 |
| Nonfarm payrolls, October | +165,000 | BLS | 6 November 2026 |
In Zurich on 5 November, according to the Cleveland Fed, she said policy must turn restrictive to return inflation to 2% “in a timely manner”. She warned that workers and firms could start building higher prices and wages into contracts. Once that happens, inflation becomes harder to dislodge.
That fear is why she prefers frequent, smaller moves. In her view, they give the economy time to adjust, cause less disruption and reduce the chance that expectations become entrenched. She insists the Fed is not behind the curve, though she would consider more aggressive action if it fell behind. She also says she enters every meeting with an open mind.
Her argument rests on current data, not forecasts. If the next CPI prints come in firm, holding rates gets harder for the rest of the committee to defend.
Where the Fed disagrees on pace, and what to watch before December 8-9
Nobody inside the Fed is arguing that inflation has gone away. The fight is over speed and size.
FOMC dissenting votes often show how close the committee is to changing course, and a cluster of dissents in the same direction has historically coincided with turning points in the rate cycle.
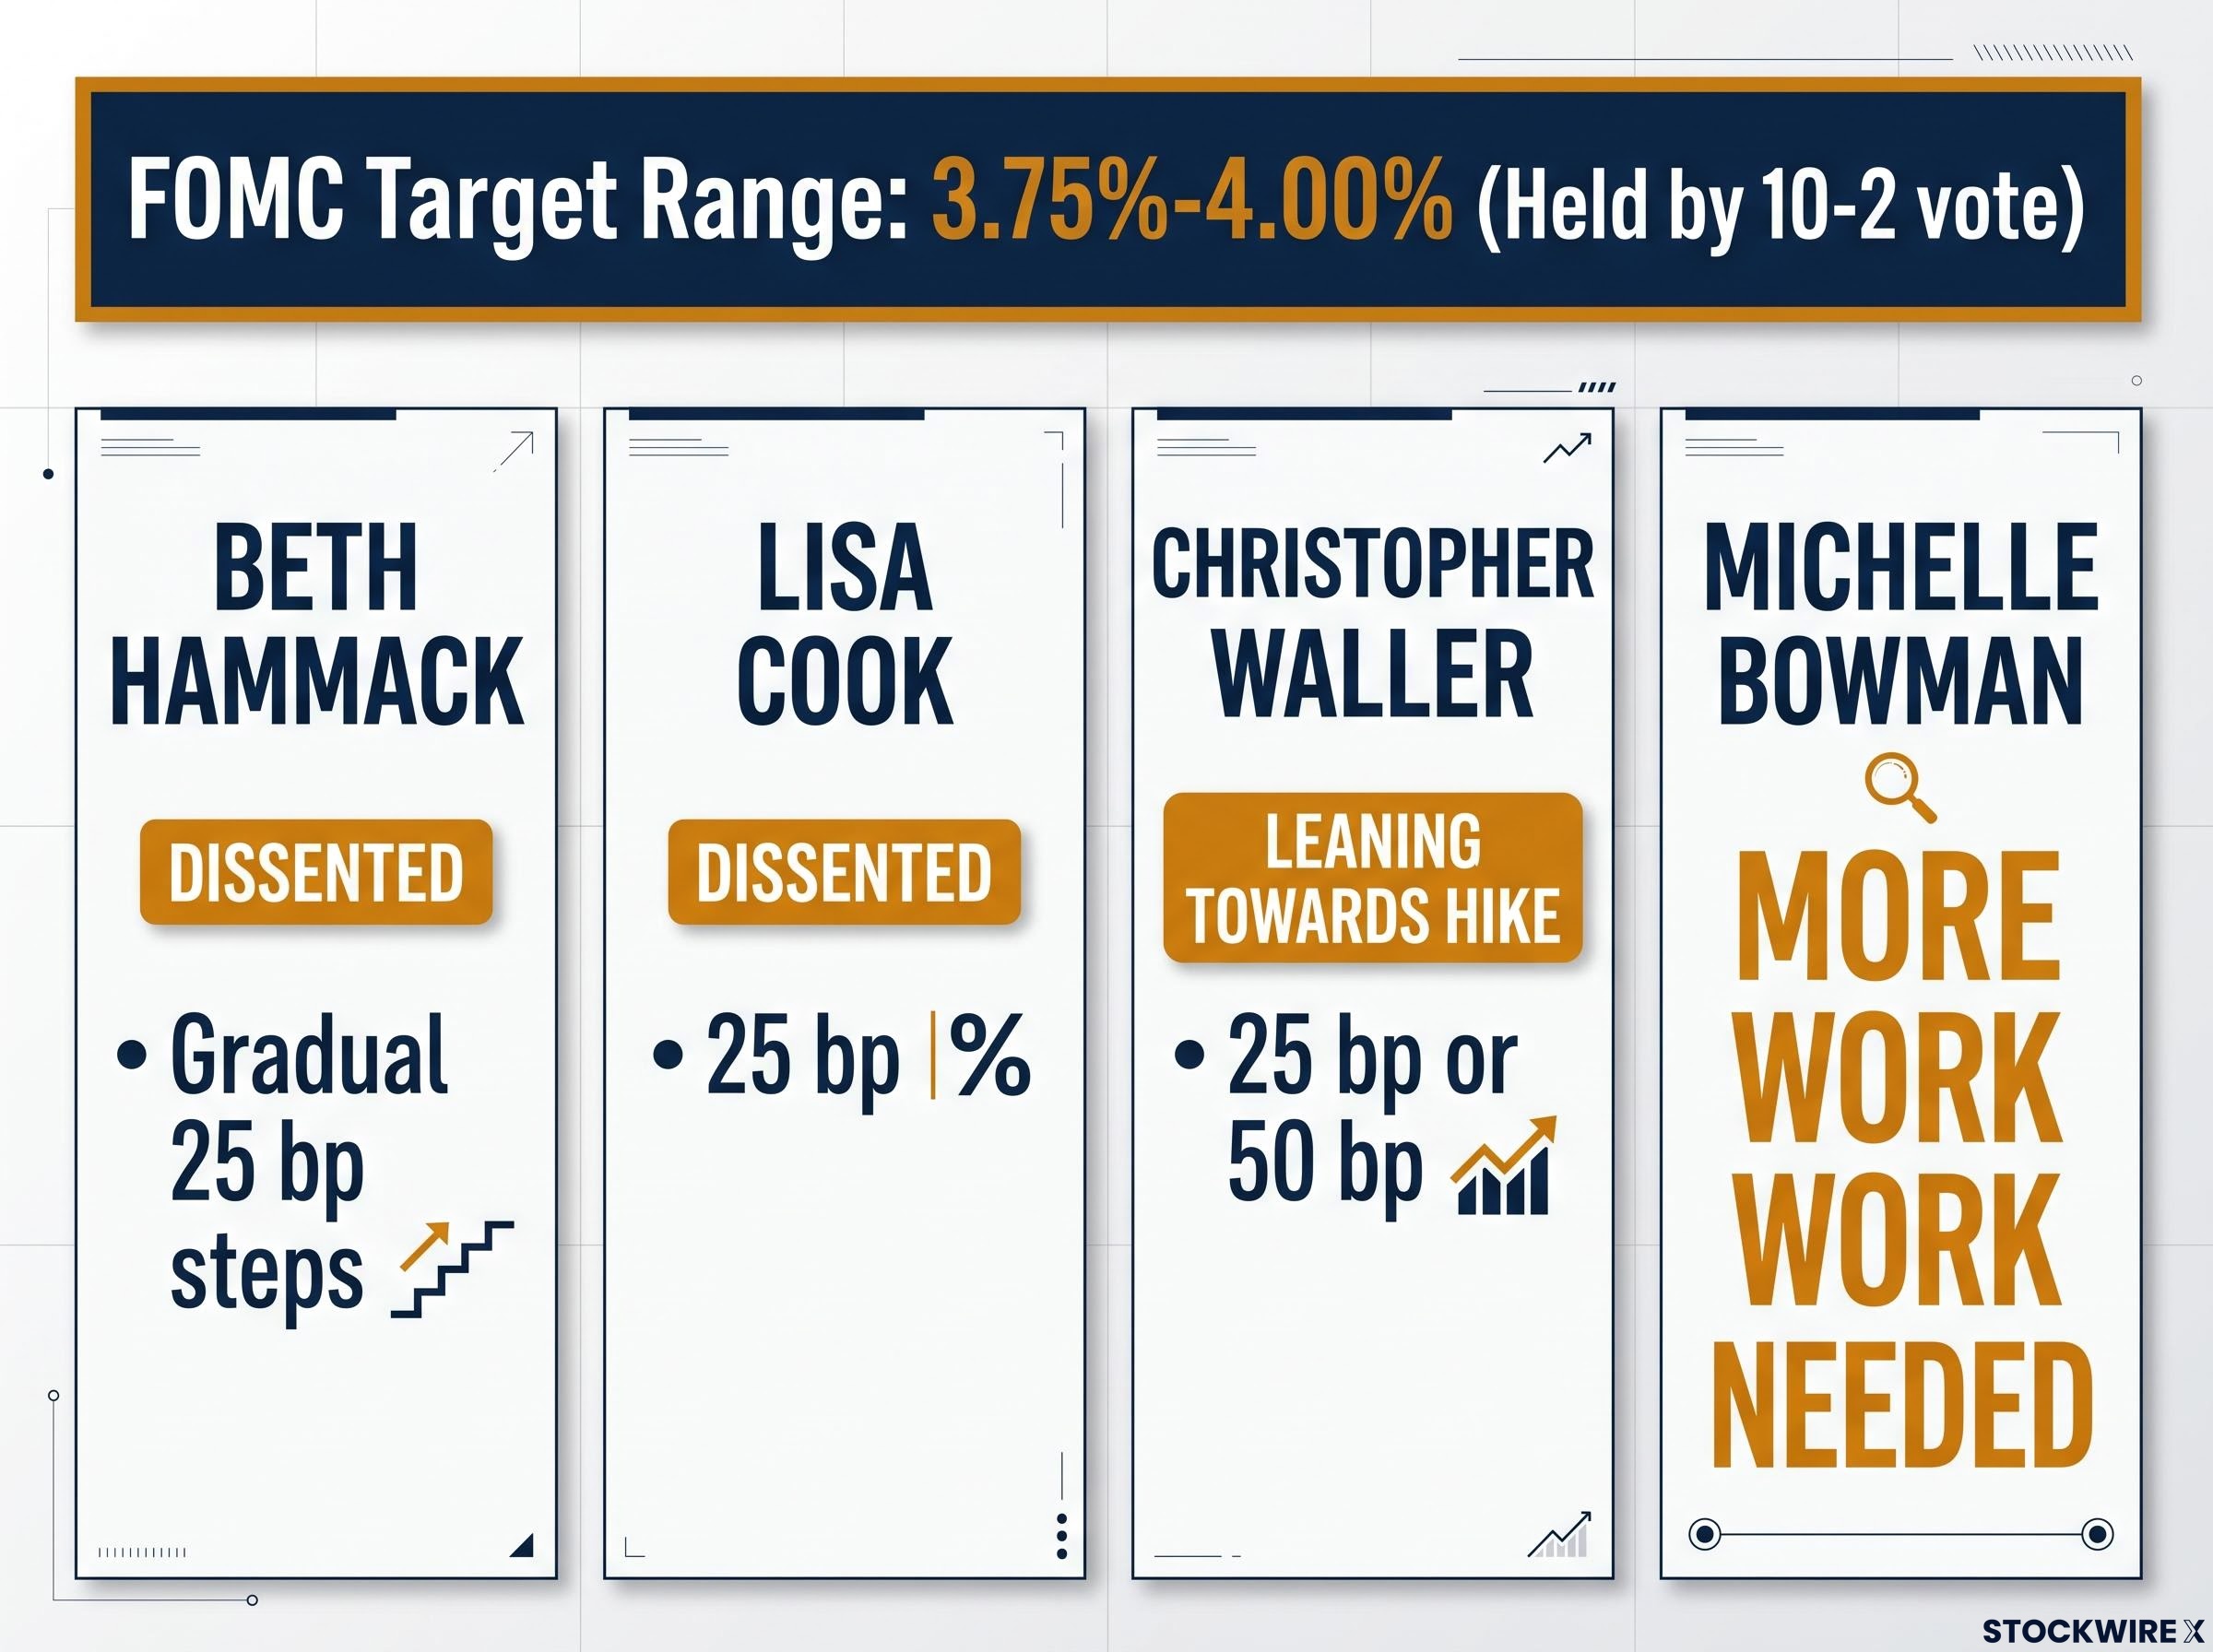
While the FOMC held the 3.75%-4.00% target by a 10-2 vote, dissenting members like Hammack favor 25 bp steps, and Waller leans 25 bp or 50 bp.
| Official or institution | Stance | Pace or size | Date |
|---|---|---|---|
| Beth Hammack, Cleveland Fed President | Dissented for a hike | Gradual, 25 bp steps | 28 October, 12 November |
| Governor Lisa Cook | Dissented for a hike | 25 bp | 28 October |
| Governor Christopher Waller | Leaning towards a hike | 25 bp, possibly 50 bp on strong core CPI | 10-11 November |
| Governor Michelle Bowman | More work needed on inflation | Not specified | 10 November |
| FOMC majority | Held pending more information | No change | 28 October |
The October majority has reasons for patience. Earlier hikes may not have fully worked through the economy yet. Goldman’s David Mericle estimates residual seasonality added about 5 bp to October CPI, and lower energy prices could cool the next readings. Goldman expects softer near-term inflation followed by renewed pressure early next year. Forecasts are subject to market conditions and may not prove accurate.
The 2022-2023 cycle showed what sustained tightening does: higher US yields supported the dollar while weighing on rate-sensitive assets.
For you, the size of the move matters more than whether one comes. A 50 bp surprise would force markets to reprice, while another 25 bp step is largely expected. These dates will settle it:
- 25 November: PCE inflation release for October
- Early December: November CPI and jobs reports
- 8-9 December: FOMC decision
Where the Fed rate hike debate goes from here
The hawkish case rests on current inflation data and on the risk that higher prices become built into expectations. The committee’s disagreement is about pace, and the dollar has already priced a good part of the answer. The 25 November PCE data, the next CPI report and the 8-9 December meeting will show whether the Fed steps gradually, as Hammack prefers, or moves faster.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.