The euro fell roughly half a percent against the US dollar on Wednesday 14 October 2026, sliding to around 1.11-1.12, its weakest level since May 2025. The trigger was US core inflation, which rose 0.3% in September against a 0.2% consensus.
The headline monthly figure matched forecasts at 0.6%, so the sting sat entirely in underlying prices. That small gap was enough to roughly double the market’s odds of a Federal Reserve rate hike in October, from about 22% to the mid-40s.
For anyone building a EUR/USD forecast, the day offers a clean case study in how one inflation number travels through rate expectations and into the currency market. The price levels and dates below are the ones that decide whether this move extends or reverses.
Why did core inflation, not the headline, move the dollar?
On paper, the release looked tame. Headline CPI (the consumer price index, which tracks the cost of a basket of everyday goods and services) came in exactly where economists expected.
Then traders looked underneath.
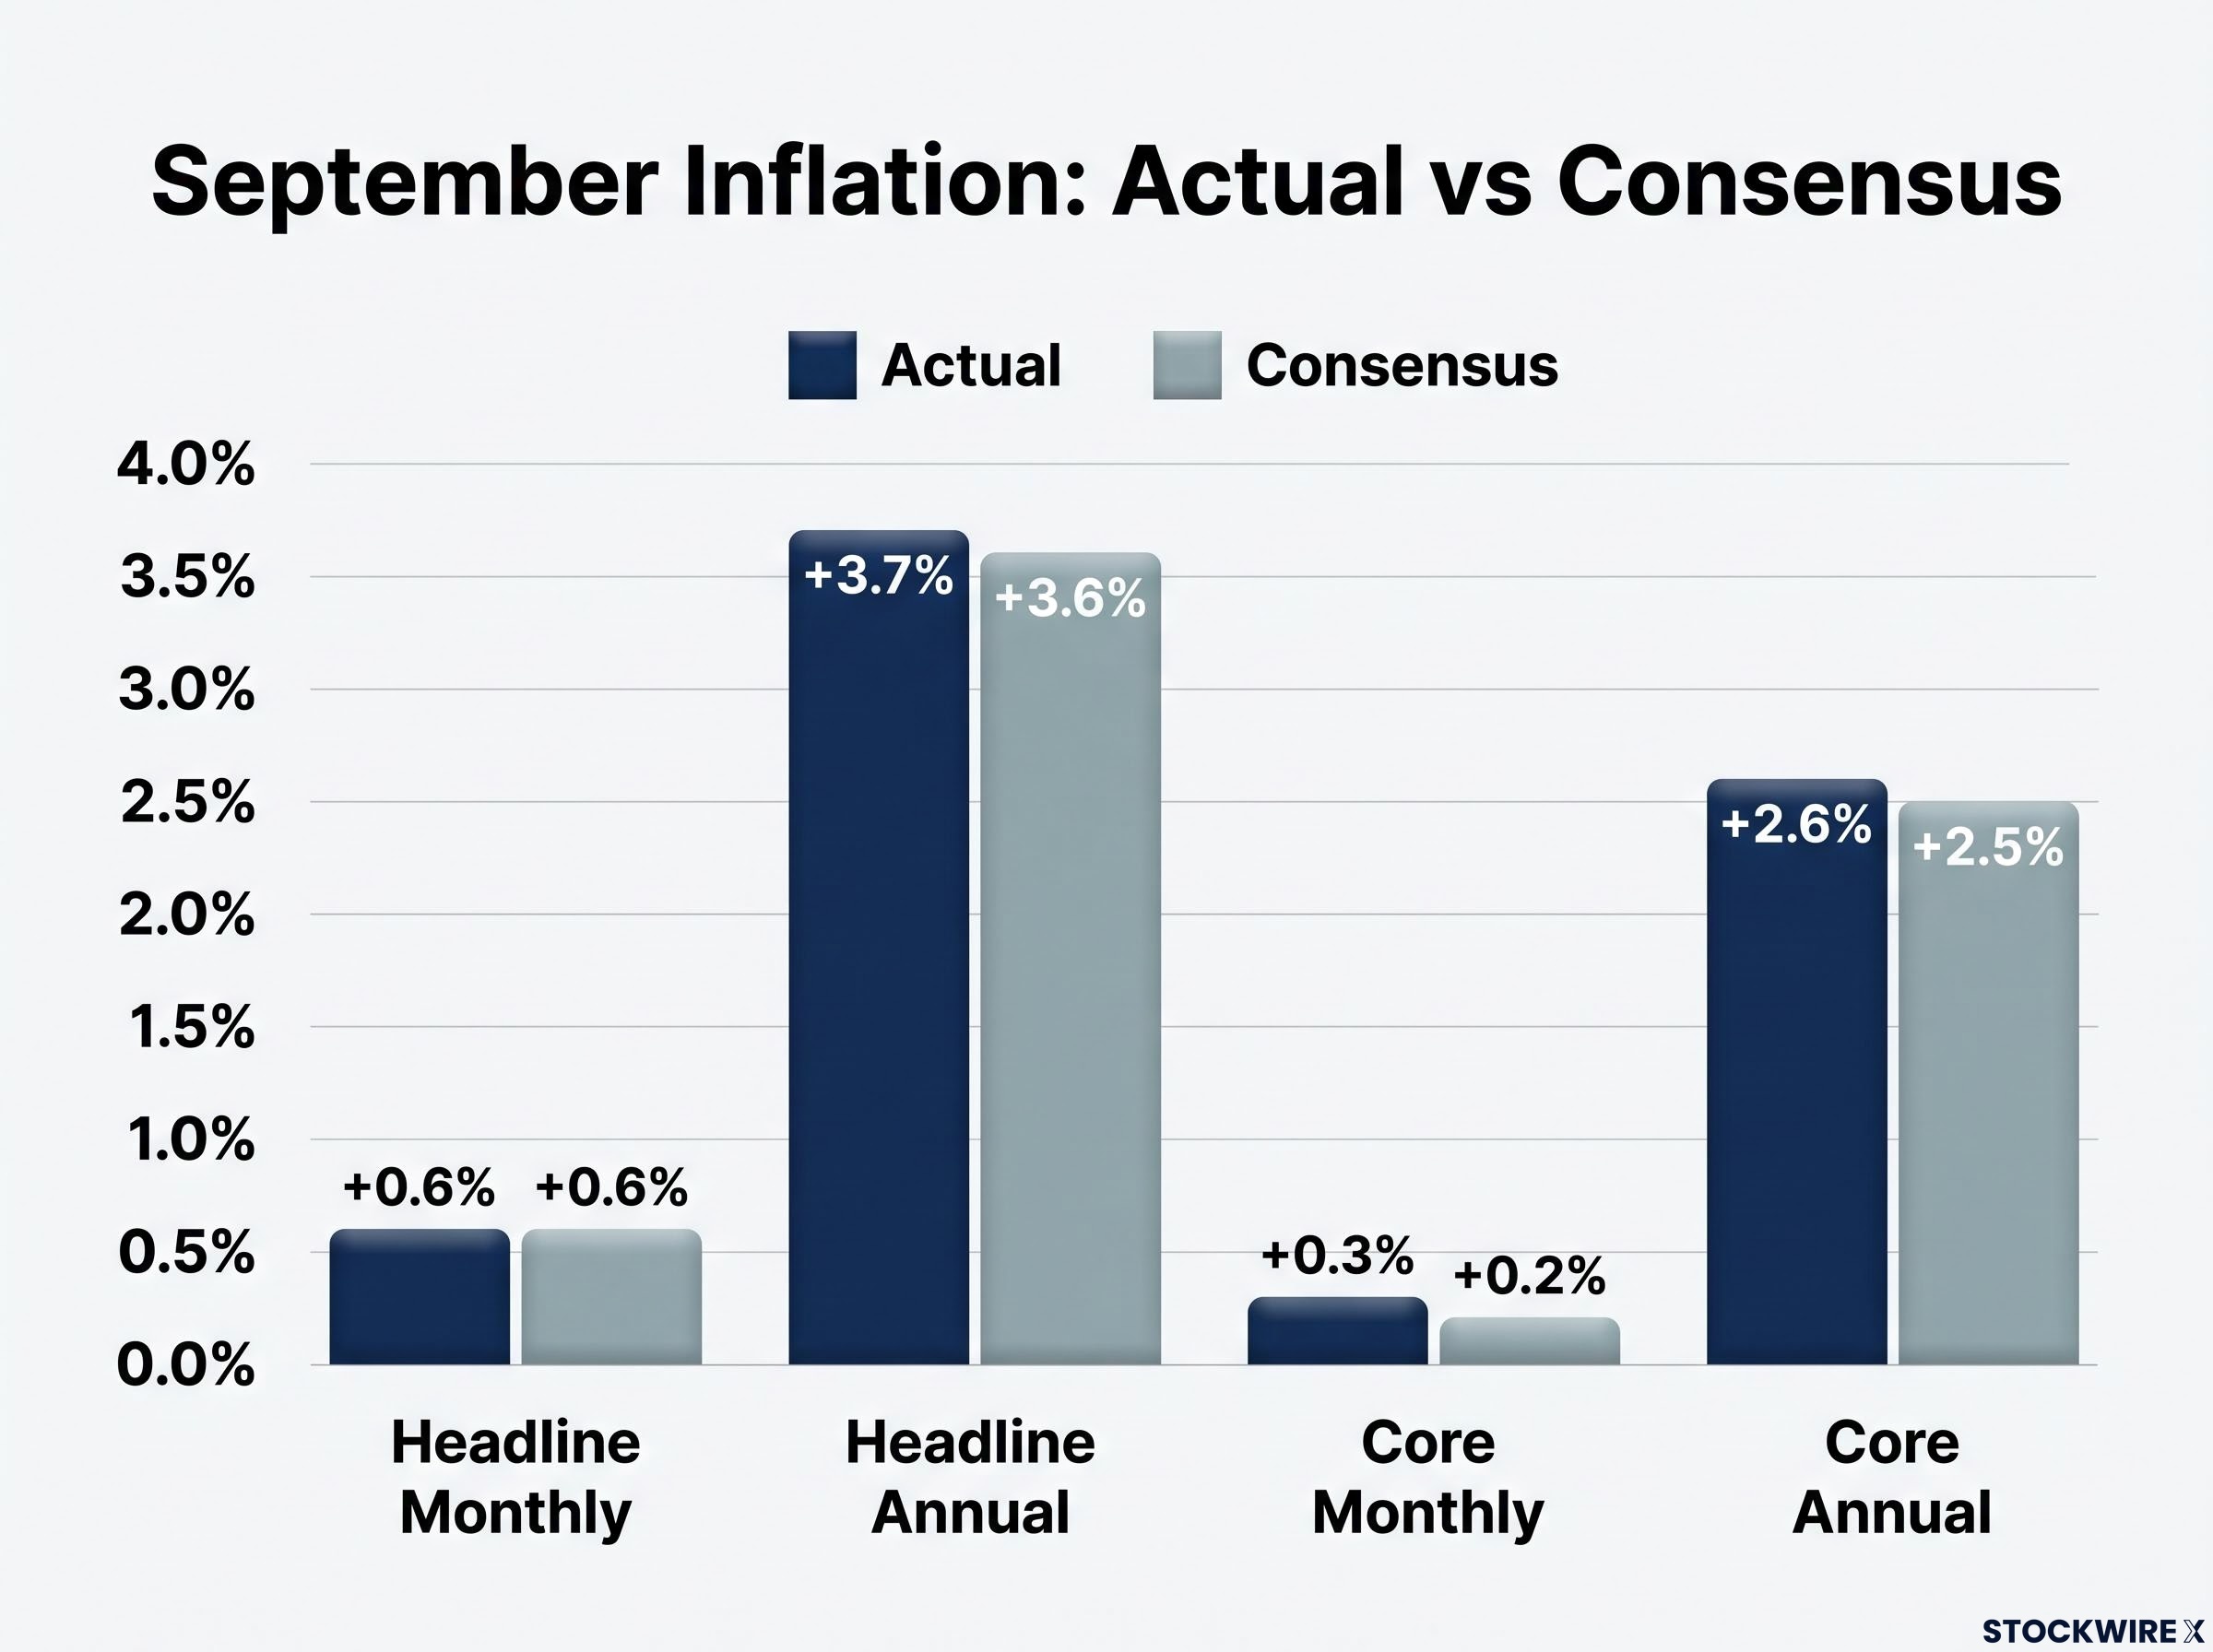
| Measure | Actual | Consensus | Previous |
|---|---|---|---|
| Headline CPI, monthly | +0.6% | +0.6% | +0.4% |
| Headline CPI, annual | +3.7% | +3.6% | +3.4% |
| Core CPI, monthly | +0.3% | +0.2% | +0.3% |
| Core CPI, annual | +2.6% | +2.5% | +2.4% |
Core CPI strips out volatile food and energy prices, so central banks treat it as the better guide to persistent inflation. Before rounding, monthly core ran at 0.33%, its strongest pace since April. The market then priced the surprise through a familiar chain:
- Hotter core inflation lifts the expected Fed rate path.
- Higher expected rates push Treasury yields up.
- Dollar assets offer a better relative return.
- Traders buy dollars and sell lower-yielding currencies such as the euro.
- Stop-losses, options hedging and short-dollar unwinds amplify the move.
How Fed hike odds repriced
CME FedWatch put October hike odds at 43%, with CNBC citing 43.7% and Reuters reporting 47.1% intraday. Year-end odds climbed to above 95% per CNBC and about 94% per Reuters and Citi. The original source had the dollar index (DXY) at year-to-date highs above 102.50, though other reports found levels of 102.09-102.30.
Citi now expects a hold in October and a December hike, Goldman Sachs expects a 25 basis point December move, and TD Securities said the data complicates the October decision. Still, New York Fed President John Williams had said there was “no need for urgency,” so the pricing is a bet, not a commitment.
The reason hot inflation strengthens the dollar is mechanical: hotter prints raise hike expectations, lift yields on dollar assets and draw foreign capital that bids up the currency, a pattern also visible in the August 2026 CPI reaction.
The lesson for you: markets react to the gap between actual and expected, and a 0.1 point core miss can double hike odds. Check core before you react to a headline.
When big ASX news breaks, our subscribers know first
Is this only a dollar story? What the euro’s monthly slide says
If this were purely about the dollar, the euro would be holding steady against other currencies. It is not.
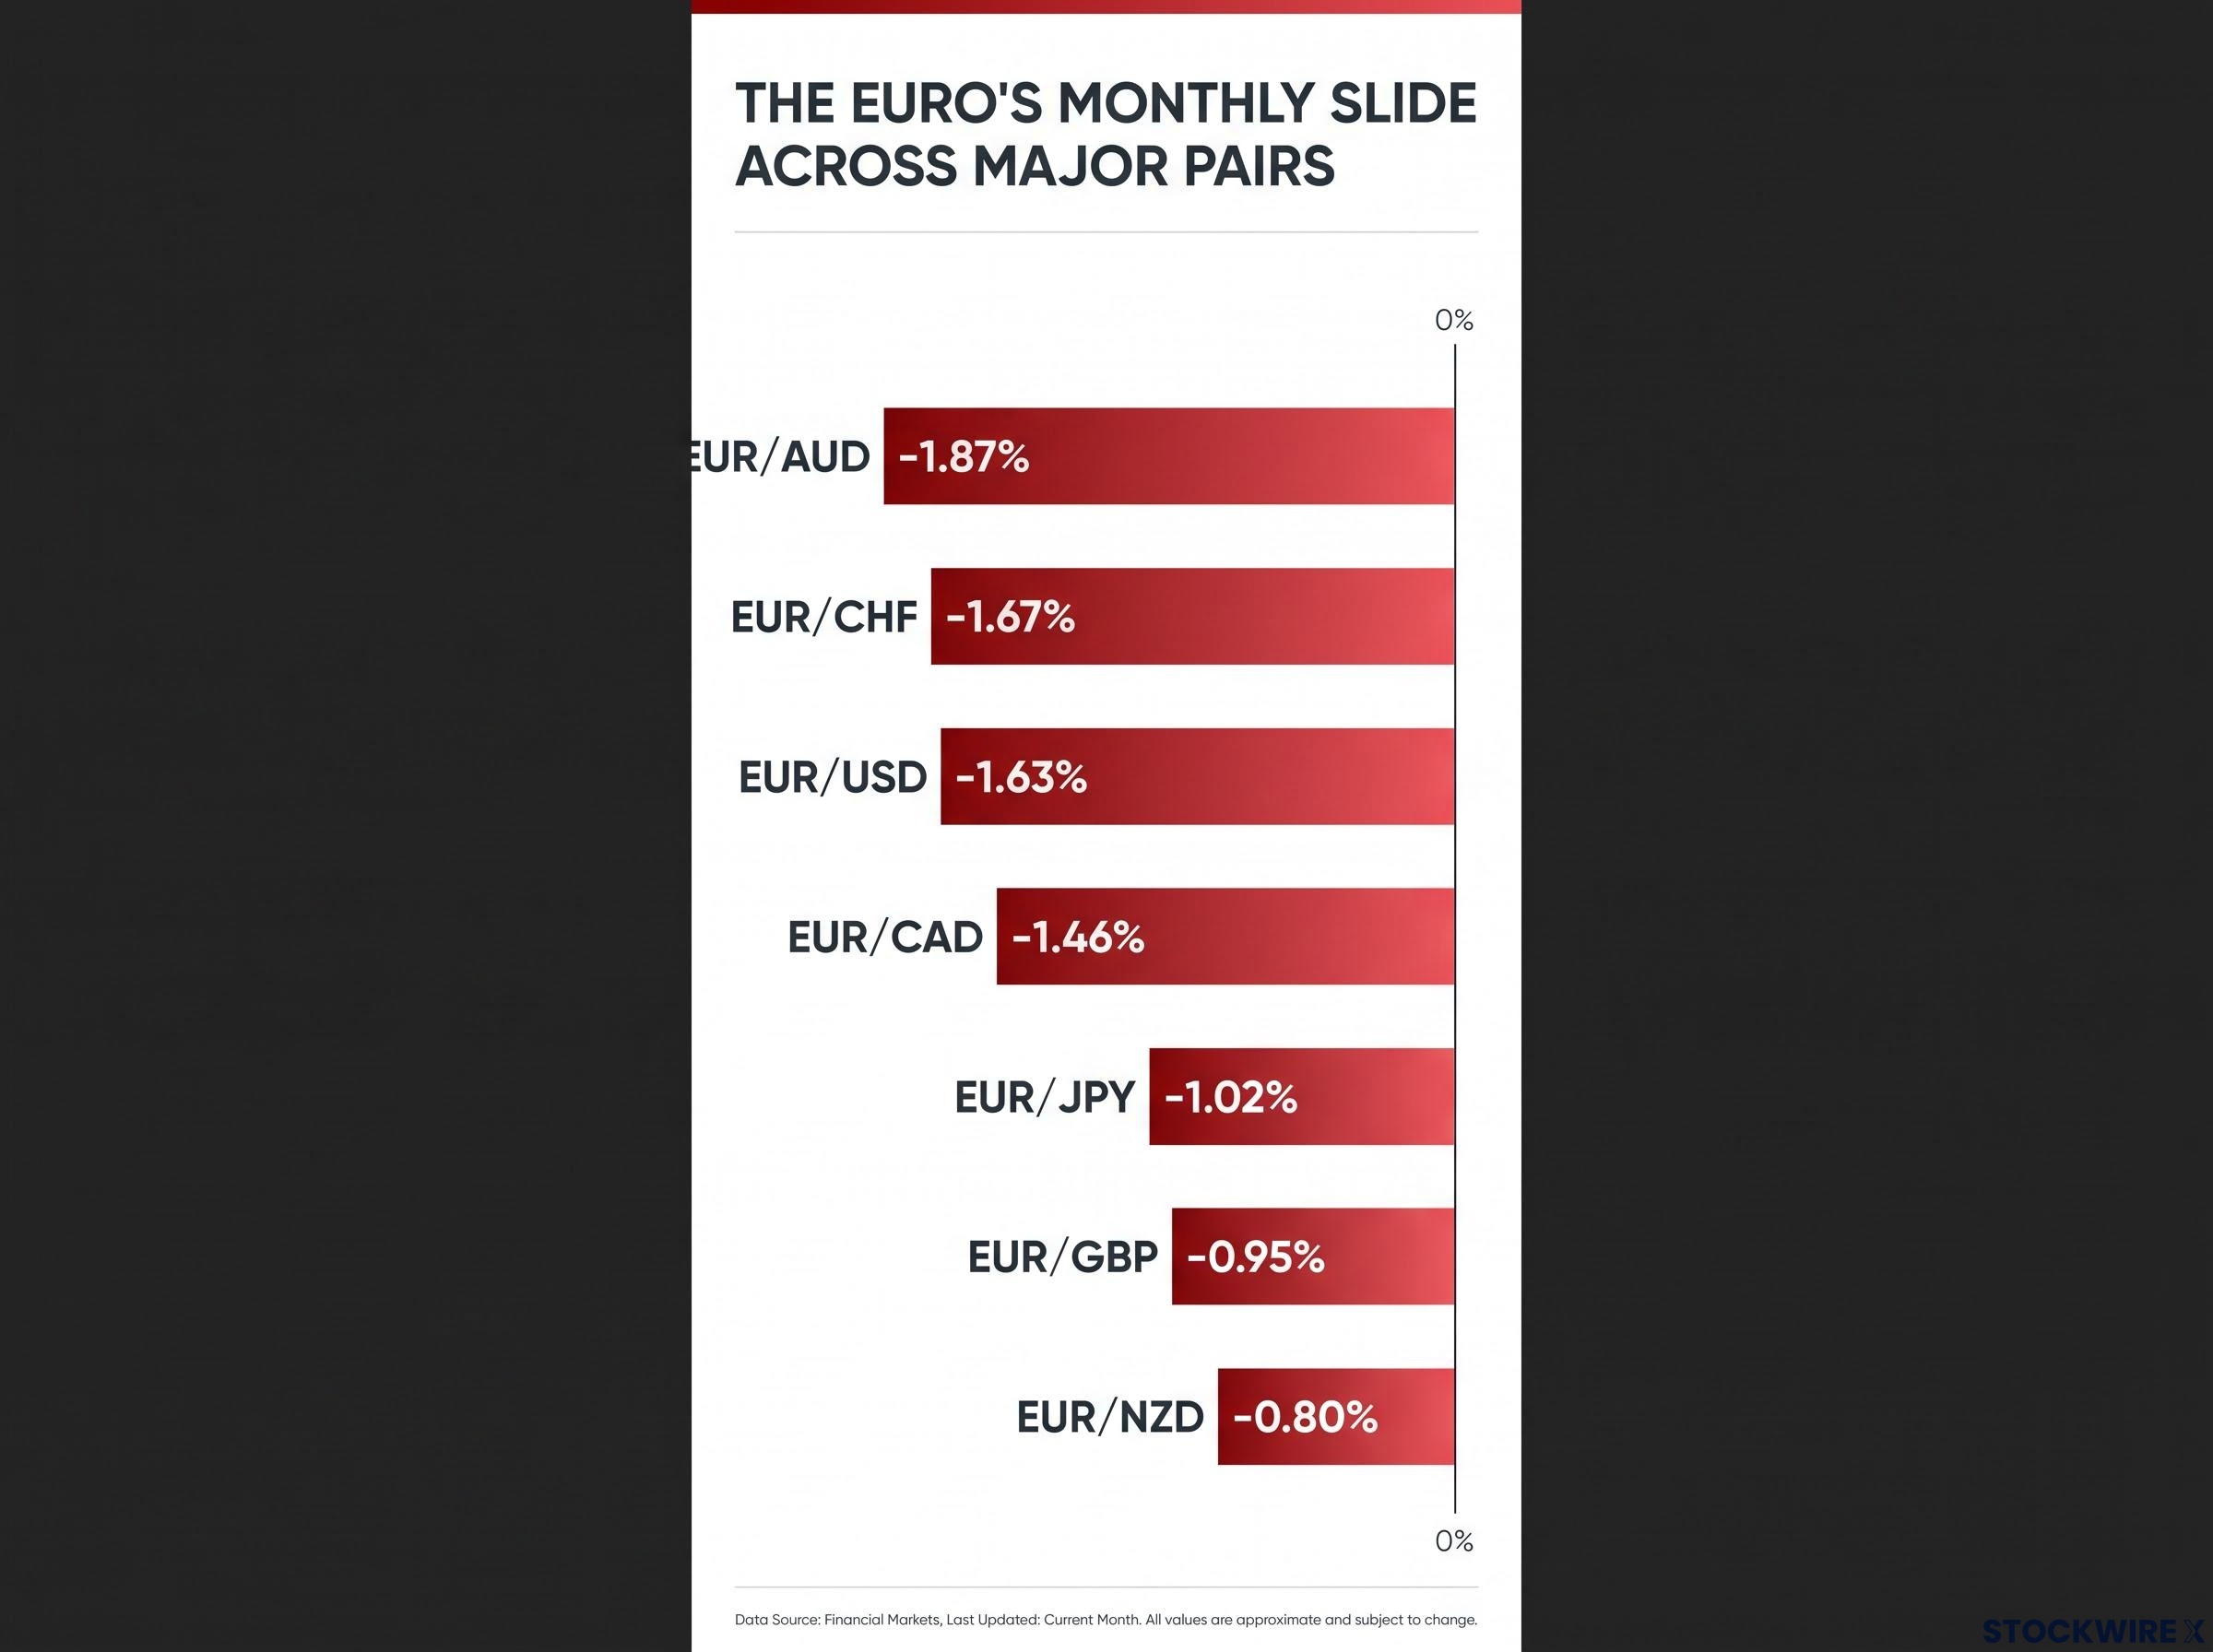
| Pair | Monthly change |
|---|---|
| EUR/USD | -1.63% |
| EUR/GBP | -0.95% |
| EUR/JPY | -1.02% |
| EUR/CAD | -1.46% |
| EUR/AUD | -1.87% |
| EUR/NZD | -0.80% |
| EUR/CHF | -1.67% |
According to FXStreet data, the euro has lost ground against every major currency this month, and its steepest fall was against the Australian dollar, not the US dollar. Something inside the euro area is weighing on it. That something is France:
- Deficit: 5.4% of GDP this year, far above the EU’s 3% reference value.
- Yields: the French 10-year yield has approached 5%, the highest since 2002.
- Rating: Morningstar DBRS kept France at AA but cut its trend to Negative on 13 October.
France also plans a record €340 billion of bond issuance in 2027, with a divided parliament heading toward the 2027 presidential election. The European Central Bank (ECB) projects euro-area deficits of 3.6% in 2026 and 3.7% in 2027.
France’s fiscal crisis, built on 117.6% debt-to-GDP and a minority government that struggles to pass budgets, explains why EUR/CHF fell nearly three times as much as EUR/USD on 2 October.
Contagion risk Reuters reported that the French bond selloff has spread into the broader euro area, adding to the pressure behind the euro’s 17-month low.
The ECB’s message is caution, not rescue. Markets price only an 11.7% chance of an October hike, and no policymaker has suggested support for France. ING judges EUR/USD about 1.5% undervalued on short-term fundamentals, meaning part of the French premium is already priced. The July 2022 inflation shock pushed the euro through parity, but an energy crisis magnified that episode.
When the euro trails the dollar, the Australian dollar and the Swiss franc together, you are looking at two drivers. A soft US print alone may not fully reverse it.
What does the EUR/USD chart show after the break to a 17-month low?
The trend case is strong. According to FXStreet’s AI-assisted technical analysis, selling has run since mid-August, after buyers failed at 1.1700. Price now sits below the 50-day (1.1481), 100-day (1.1479) and 200-day (1.1588) simple moving averages, which track average closing prices over those periods.
- RSI near 26: the relative strength index measures recent momentum, and readings below 30 signal oversold conditions.
- ADX near 53 and rising: the average directional index measures trend strength, and readings above 25 indicate a strong trend.
- MACD below zero: this momentum gauge confirms bearish pressure.
Reported lows differ, from 1.1113 (FXStreet) to 1.1152-1.1153 (CNBC and others), but all mark the same 17-month low zone.
| Level type | Price | Significance |
|---|---|---|
| Resistance | 1.1700 | Mid-August failure point |
| Resistance | 1.1481-1.1588 | Moving-average cluster |
| Resistance | 1.1350 | Second recovery hurdle |
| Resistance | 1.1200 | First test for any rebound |
| Support | 1.1150 | Near current lows |
| Support | 1.1100 | ING’s flagged test level |
| Support | 1.1000 | Next target if 1.1150 breaks |
ING has cut its forecast to 1.13 for Q4 2026 and Q1 2027, while UniCredit sees vulnerability below the week’s low.
ING’s EUR/USD targets of 1.1100 to 1.1120, with 1.1000 as a bearish extension, depend on deeper bond stress and on ECB rate expectations, which are doing more damage than the fiscal premium itself.
Yet StoneX argues the dollar rally looks stretched and EUR/USD oversold. A strong trend paired with oversold momentum tells you the slide can continue, but fresh short positions near the lows carry real reversal risk. Levels matter more than direction here.
What could reverse or extend the move before the October 27-28 FOMC?
The next fortnight is crowded:
- Core PCE: TD Securities projects a 0.36% monthly rise in the Fed’s preferred inflation gauge.
- Fed speakers: any echo of Williams’ patience could cool hike bets.
- 27-28 October FOMC: the Federal Open Market Committee rate decision.
- ECB communication: watch for any shift in tone on France.
- French budget votes and OAT-Bund spreads: the yield gap between French and German bonds.
| Institution | Stance | Key level or call |
|---|---|---|
| ING | Dollar strength | Test of 1.1100; 1.13 forecast |
| UniCredit | Dollar strength | Risk case: headline at 4% |
| MUFG | Dollar strength | Downside risks dominant |
| Citi | Hawkish Fed | October hold, December hike |
| StoneX | Euro rebound | EUR/USD oversold |
| Commerzbank | Euro rebound | Soft data could ease pressure |
Bull case for the dollar
UniCredit’s Roberto Mialich flags headline inflation reaching 4% or core accelerating further as the risk case. Goldman read Governor Christopher Waller’s comments as a hawkish shift. ING, however, cautions that a hotter print may not alone lift October odds above 50%.
Rebound case for the euro
Commerzbank’s Volkmar Baur argues expectations are already elevated, so a downside surprise could support the euro. If the core strength came from one-off items, traders may discount it, and ING flags crowded dollar longs. On France, the ECB’s Transmission Protection Instrument exists, but having it is not the same as France qualifying for it.
EUR/USD now answers to both US data and French politics. One calendar event can swing the pair either way, so position sizing should reflect that fork.
Where the EUR/USD outlook goes from here
Two forces have converged. Hotter core inflation has pushed year-end Fed hike odds near 95%, while French fiscal stress has added a euro-specific risk premium. Oversold readings, though, keep a corrective rebound firmly in play.
Your decision points are concrete. On the downside, watch 1.1150 and then 1.1000. On the upside, a recovery would need to clear 1.1200 and then 1.1350. On the calendar, core PCE and the 27-28 October FOMC are the dates most likely to settle which force wins, with French budget votes as the wildcard.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and forecasts are subject to market conditions and various risk factors.