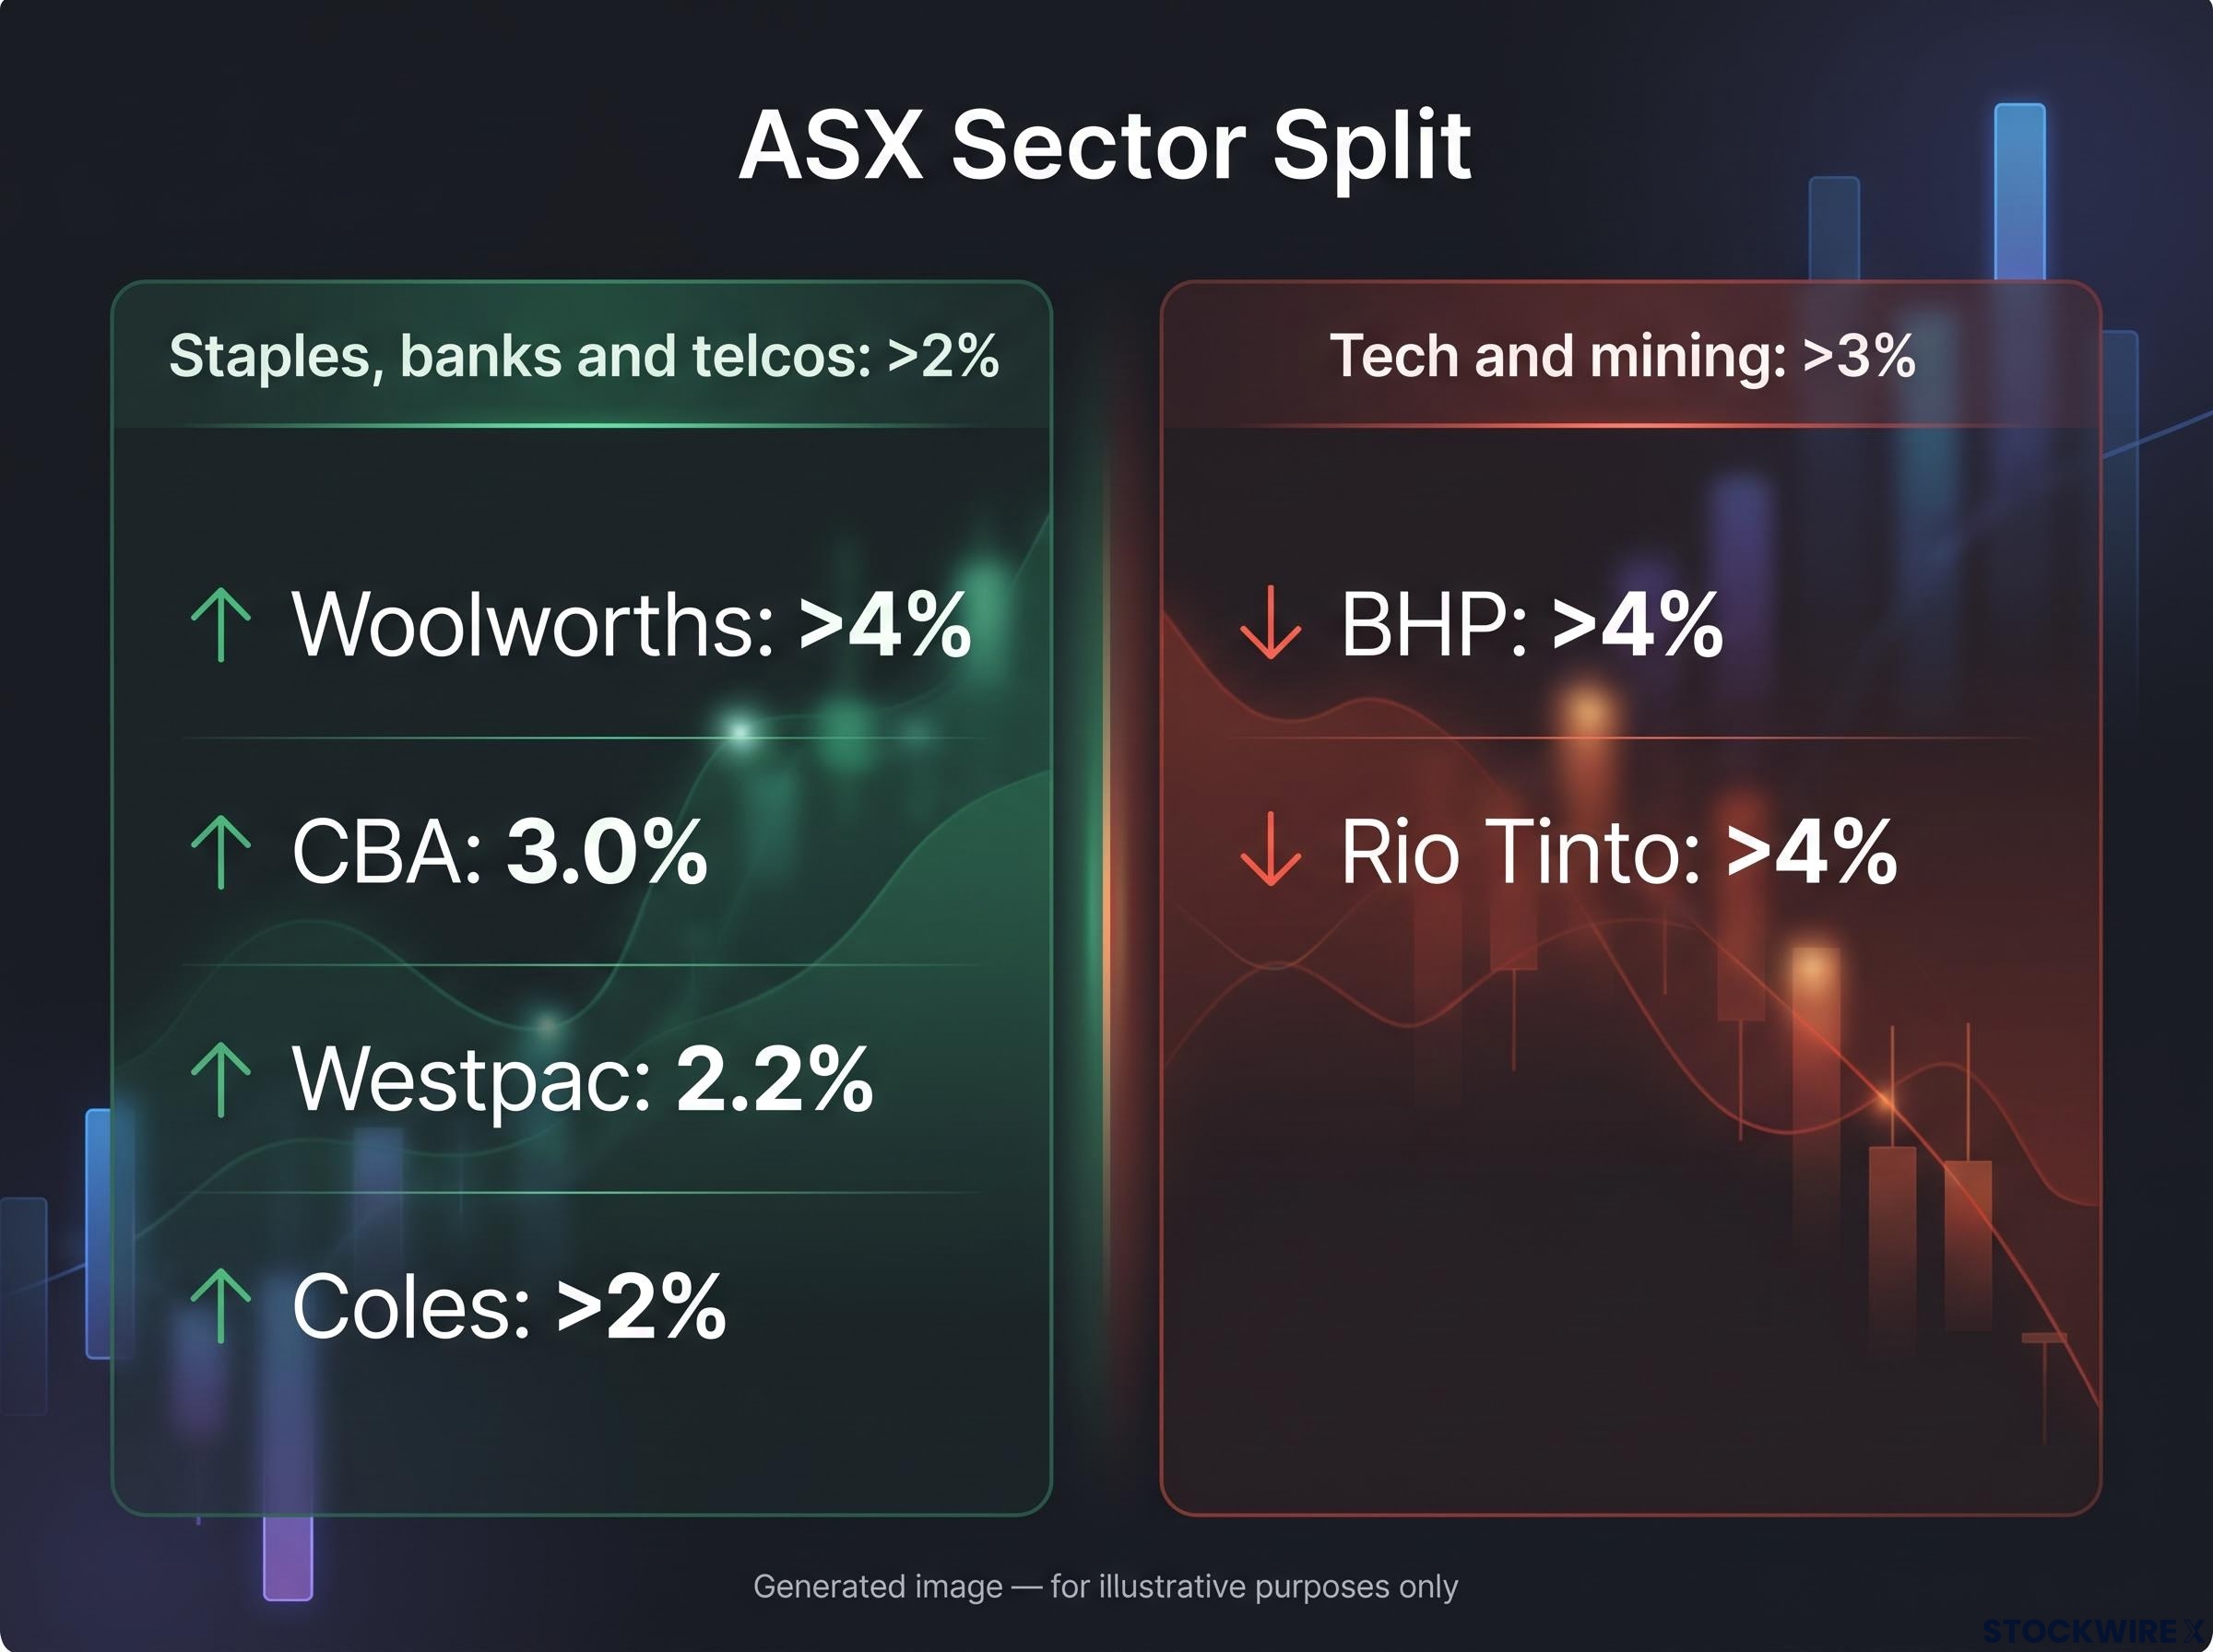
The S&P/ASX 200 spent Thursday absorbing two shocks at once. It sank as much as 86 points (0.99%) early, then clawed back to roughly flat after a weak jobs report. Underneath that calm headline, staples, banks and telcos jumped more than 2% while tech and mining shares fell more than 3%.
Two opposing forces collided. A soft domestic labour market cut bets on another Reserve Bank of Australia (RBA) rate hike, while hot US inflation and an AI-led selloff battered chip stocks across Asia.
All moves cited here are intraday. The ASX 200 closing level was not available at the time of writing.
The sections below explain why a flat index hid one of the sharpest sector splits of the year, and which signals are most likely to decide whether it lasts.
Why did a weak jobs report lift staples, banks and telcos?
The jobs data landed at 11:30 am AEDT, and the index moved within a minute. It went from down 0.75% to down 0.45% almost immediately, then climbed back to breakeven by about 12:50 pm AEDT.
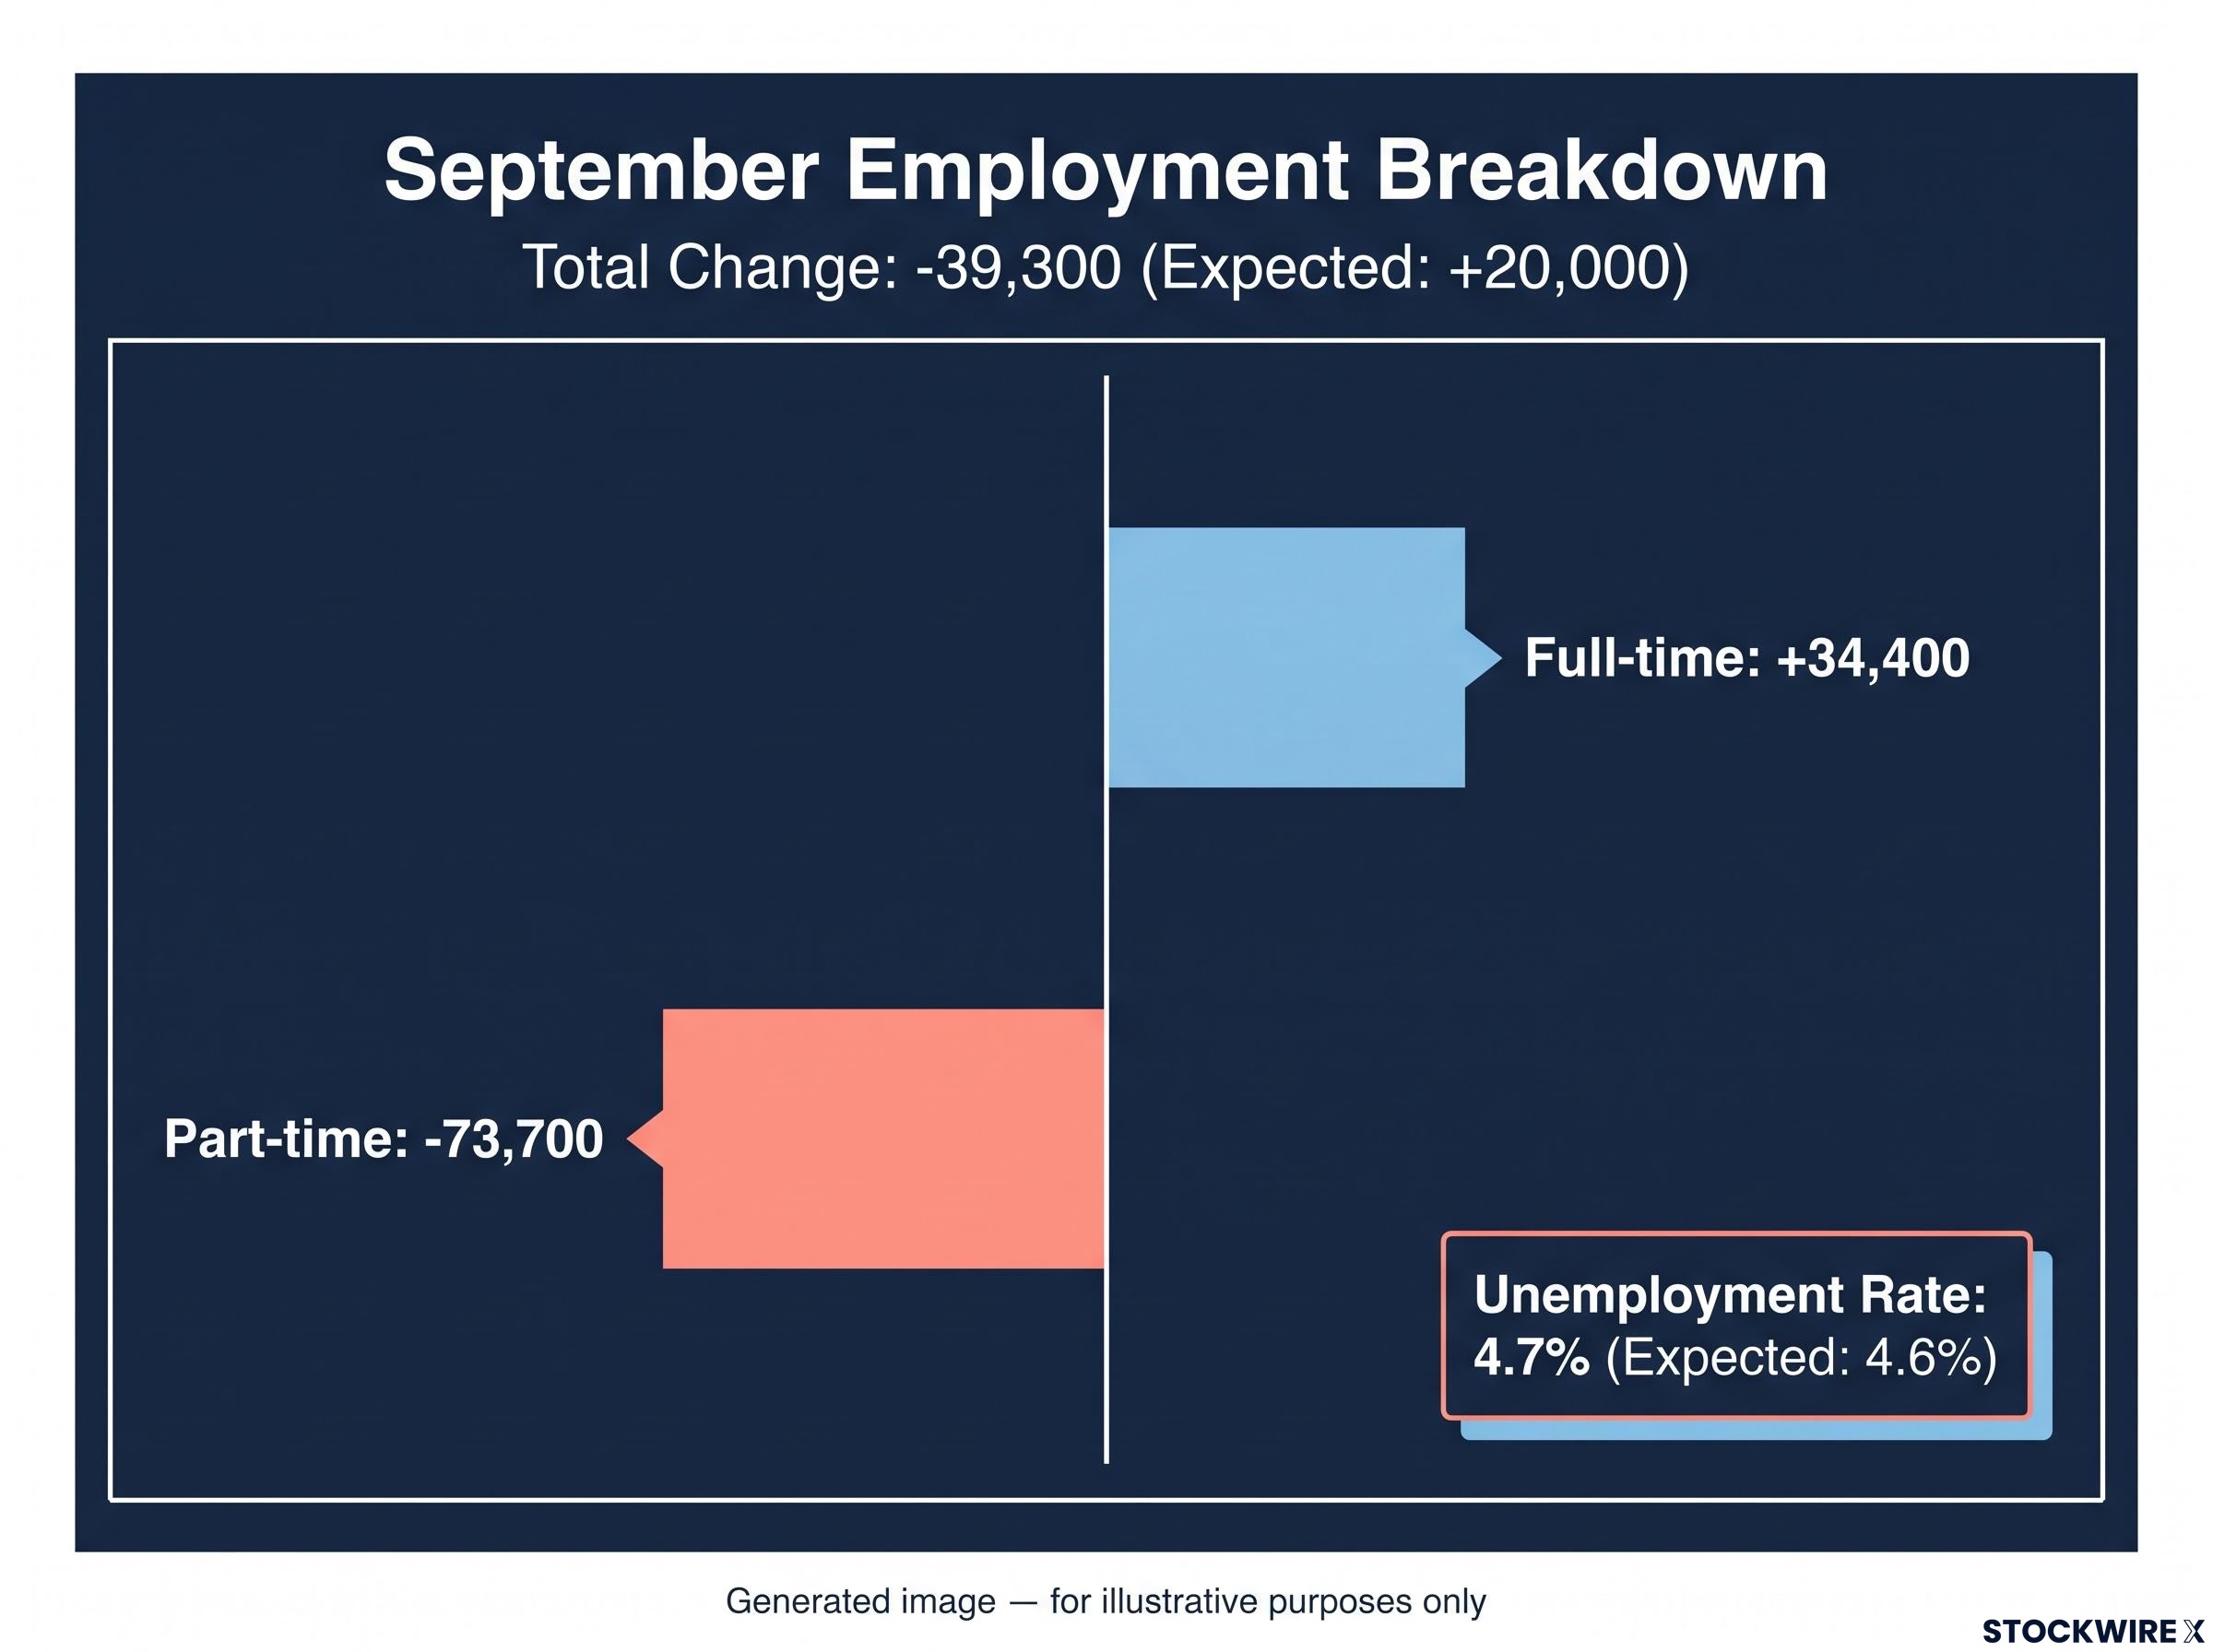
The trigger was a clear miss. The Australian Bureau of Statistics (ABS) reported a loss of 39,300 jobs in September, when Westpac, CBA and ANZ had all forecast gains.
| Measure | Actual | Expected |
|---|---|---|
| Unemployment rate | 4.7% | 4.6% |
| Employment change | -39,300 | About +20,000 |
| Participation rate | 66.8% | 67.0% |
Part-time work drove the fall, down 73,700, while full-time jobs rose 34,400.
Part-time job losses have driven headline weakness before, and earlier episodes showed how a soft print can overstate the breadth of labour market deterioration while full-time hiring holds up.
Traders repriced the RBA almost instantly. The odds of a November hike dropped to about 15%, from just under 50% earlier in October, according to InvestingLive. Reuters put the implied chance of a hold at 4.6% near 90%, and the 3-year government bond yield fell about 12 basis points to 4.80%.
That shift matters because Westpac and ANZ had both carried a November hike as their base case before the release.
The winners were the shares that benefit most from lower rates and steady earnings:
- Woolworths: up more than 4%
- Coles: up more than 2%, near record highs
- CBA: up 3.0%
- Westpac: up 2.2%
The market was not celebrating bad economic news. It was paying for earnings certainty and a lower discount rate, which is the rate investors use to value future profits. If you hold banks or supermarkets, Thursday’s gains rest on rate expectations, not on any improvement in their earnings.
What did hot US inflation and the AI selloff do to tech and miners?
The domestic relief explains only half the screen. The other half was built overnight in New York.
The US trigger
US September consumer price index (CPI) data ran hot. Headline inflation hit 3.7% year on year against 3.6% expected, and core prices rose 0.3% for the month versus 0.2%, reviving fears the Federal Reserve will keep rates higher for longer.
The S&P 500 fell 1.11% to 7,718.94, the Nasdaq dropped 1.88% to 26,692.87 and the Russell 2000 lost 1.9%. The Dow slipped just 0.09% as staples and healthcare held it up.
AI debt added the spark. CoreWeave shares fell about 15.5%, and its 9.75% bonds traded near 81 cents on the dollar, yielding more than 15%. CEO Mike Intrator called the market’s behaviour “irrational”.
Credit as a signal Craig Manchuck of Osterweis Capital Management described CoreWeave as a “bellwether for AI sentiment”.
The Asian and ASX fallout
Asian chipmakers took the hit hardest. Reported figures vary with the timing of each snapshot:
- Kospi: down as much as 7.9% per Market Index (other reports cited 5.7%-6.5% intraday)
- SK Hynix and Samsung: each down more than 9%
- Nikkei 225: down more than 4%
- Taiex: down more than 3%
On the ASX, miners fell more than 3%, with BHP and Rio Tinto down more than 4%. Copper slid 1.6% to US$6.67/lb, iron ore eased 0.4% to US$90.35/t and silver dropped 6%.
Copper is now partly an AI trade, because data centres need large amounts of it. Citadel Securities analysis cited by GuruFocus found Nvidia and Micron alone account for about 36% of S&P 500 Q3 earnings growth, though sources differ on total growth (27.2% versus 29.5%). If you hold miners or tech, you carry exposure to that concentration even without owning a chipmaker.
Semiconductor stocks had already rallied strongly this year and were priced for flawless execution, which helps explain why a single credit scare was enough to trigger such sharp moves across Asian chipmakers.
Is the defensive rotation a safe harbour or a crowded trade?
The logic of the rotation is tidy. Yields fell, defensive earnings look dependable, and stable cash flows become worth more when rates are expected to stay lower.
The catch is why yields fell. They dropped on growth worries, not easing inflation, with the cash rate at 4.60% after September’s hike and December hike pricing still around 31%-40% depending on the snapshot.
Valuations leave little room for error. Coles and Woolworths trade at about 25 times FY26 adjusted earnings, and CBA at about 24 times trailing earnings (the two measures are not directly comparable).
The jobs signal itself is cloudy. CBA warned that changes to the ABS survey sample can make monthly releases noisy, and the drop in participation muddies the read on labour demand. Westpac’s view is that inflation, not jobs alone, will steer the RBA, and that a hike remains justified.
| Interpretation | Reasoning |
|---|---|
| Leverage unwinding | Bond yields above 15% at CoreWeave question how debt-funded AI infrastructure copes with higher rates |
| Overreaction in a valid cycle | Intrator argues backlog covers debt and demand for computing capacity holds |
| Concentration and valuation problem | The AI thesis may hold, but index earnings lean on very few chip firms |
There is a case for the rotation, though. Zacks analysis from 14 October put S&P 500 earnings growth at about 12.7% excluding tech, against about 22% overall (a figure that differs from those above). If AI falters, little else drives growth.
Watch these triggers:
- Australian CPI
- The next US inflation release
- CoreWeave’s bond pricing
- Any RBA commentary on November
Treat Thursday’s move as a bet on yields staying lower, not proof that defensives are cheap or risk-free.
What a flat index hid, and the signals that decide what happens next
Thursday’s near-flat reading masked a genuine split. Rate-sensitive defensives rallied on lower hike odds, while AI-exposed tech and miners sank, and the same weak jobs data that lifted one group doubles as a growth warning for the other.
A similar ASX sector rotation played out earlier this year, when a near-flat index close hid heavy capital movement between rate-sensitive domestic names and globally exposed technology and resources.
Three variables will shape what comes next: RBA pricing into November, US yields and Fed expectations, and credit stress in AI infrastructure. If you are weighing defensive holdings against AI-linked positions, the question is which of those signals you expect to move first, and whether today’s prices already assume the answer.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.