A large pharmaceutical company buys an instrument. The share register waits for news. Twelve months pass, and nothing arrives.
From the outside, that silence reads like stalling. No follow-on order, no press release, no confirmation that the technology cleared whatever internal bar it needed to clear. Investors start to wonder whether the deal is quietly dying.
Here is the problem with that reading: the silence is not stalling. It is structured progress. From the inside, a pharmaceutical evaluation period is not empty at all. It is a sequence of distinct approvals, each run by a different group inside the customer, each measured against different criteria.
Knowing that sequence changes what you can read from every subsequent announcement, and not just for one company. It applies to any supplier selling into a regulated industry.
Once you understand the gates, a follow-on order stops being a headline about instrument count. It becomes a signal about which stage a customer has reached, and each stage carries very different implications for what comes next.
Here is the map the silence does not come with.
Why the caution is the point
Pharmaceutical manufacturing runs under Good Manufacturing Practice (GMP) regulation, a framework that governs how medicines are made. The core principle is simple: every modification to a regulated quality process must be fully justified, rigorously tested, properly documented, and kept under control before it can enter routine production.
That caution is not administrative overhead. It reflects what is at stake in the underlying work.
The specific application here is environmental monitoring, the practice of detecting contamination during medicine production. When errors slip through that process, the consequences reach patients directly. A supplier cannot shortcut the checks, and a customer cannot skip them, because the checks are the mechanism that assures a new technology will not introduce error into the manufacture of medicines.
That is why equipment operating in a GMP environment is formally qualified before anyone relies on it. Qualification is the documented framework regulators and practitioners use to establish that a system performs reliably.
The three qualification stages in plain terms
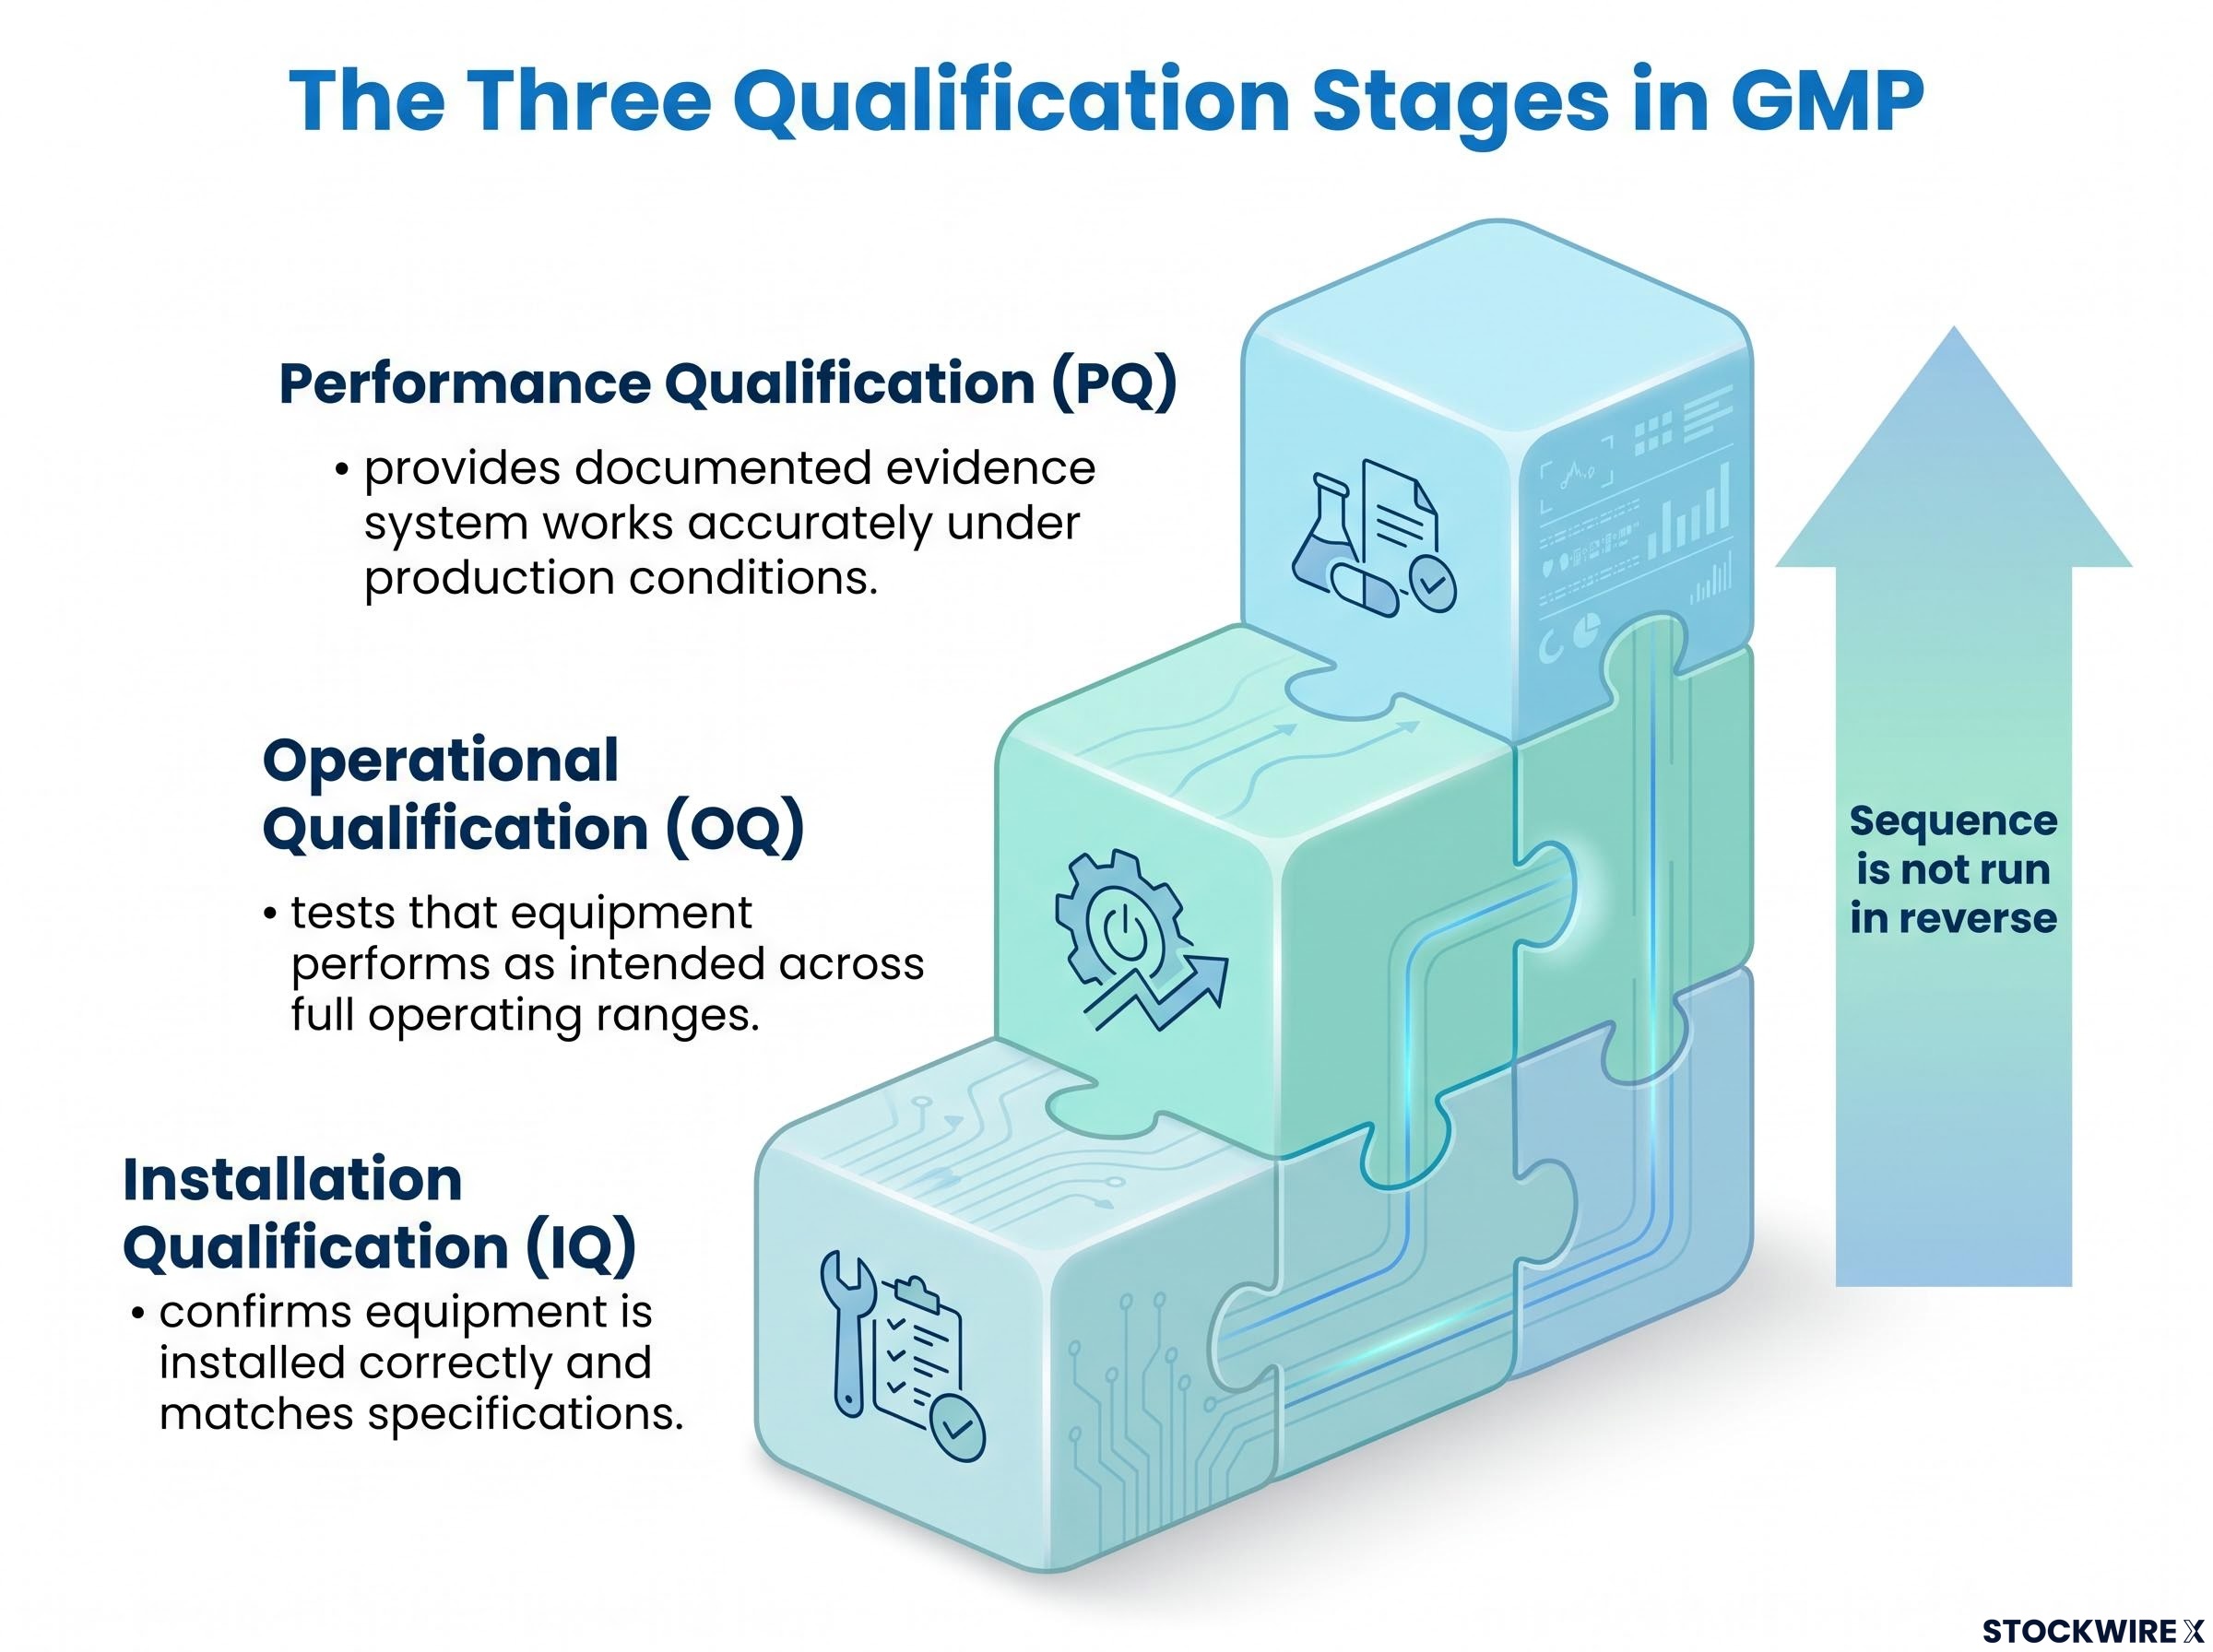
The standard sequence runs across three stages, each establishing something distinct:
- Installation Qualification (IQ) confirms the equipment is installed correctly and matches its specifications, catching hidden defects such as incorrect utilities or misconfigured options before they compromise anything.
- Operational Qualification (OQ) tests that the equipment performs as intended across its full operating ranges, checking alarms, interlocks, and performance against the user requirement specifications.
- Performance Qualification (PQ) provides documented evidence that the system works accurately and reproducibly under actual or simulated production conditions, protecting against operator variability or gradual drift.
The FDA’s process validation guidance defines these stages within its process qualification framework, and PIC/S Annex 15 sets out equivalent expectations under the PIC/S GMP Guide. Annex 15 is widely interpreted as applying to automated quality control laboratory systems, including the colony counters and environmental monitoring automation this discussion concerns.
The FDA process validation guidance defines these qualification stages within a three-stage lifecycle framework, where process design, process qualification, and continued process verification each carry distinct documentation requirements that a regulated manufacturer cannot abbreviate.
The stages can be combined where regulators permit. IQ and OQ are sometimes merged into a single IOQ document, for example. But PQ normally follows only after IQ and OQ complete successfully, and the sequence is not run in reverse.
For an investor, the takeaway is structural. The process is long because the mechanism of assurance requires it to be long, not because any particular customer is hesitating about any particular technology. Read the length as design, not as doubt.
When big ASX news breaks, our subscribers know first
The five gates a technology moves through inside a pharmaceutical customer
Once the qualification logic is clear, the larger adoption sequence follows the same principle: each step is a separate decision, made by a separate group, and each has to close before the next opens.
Large pharmaceutical manufacturers typically move a new technology through roughly five gates. This is a general industry pattern rather than a fixed rule, because every customer runs its own process and its own cadence.
The first gate is centralised evaluation, where a specialist team tests the technology against internal standards and samples, often over many months. The second is formal global validation, the documented GMP process that turns a promising evaluation into something approved for real use. The third is systems integration, where the technology is connected into the customer’s wider data and quality infrastructure. The fourth is routine use at a validated site. The fifth is site-by-site expansion across the manufacturing network.
Passing the technical evaluation at gate one does not constitute production approval. Formal validation under documented procedures, gate two, is what unlocks routine use. Each gate corresponds to real internal work, which is why the public silence between announcements can be long even when progress is continuous.
Novo Nordisk offers the clearest public illustration of the sequence in motion. According to CC5’s ASX announcements, Novo placed its first APAS Independence order in July 2025 after roughly 12 months of evaluation by a centralised team in Denmark, covering both the 90mm and contact plate modules. That was gate one closing.
In September 2026, Novo ordered two more instruments, taking its installed base to three units, all destined for a single Danish site for formal global validation toward routine GMP use.
The Novo Nordisk reorder announcement in September 2026 is the primary source for the gate-two and gate-three details discussed here, including the LIMS integration commission and the formal global validation language CC5 used to characterise the order’s significance.
CC5 described the September 2026 order as the final technology performance milestone Novo Nordisk requires ahead of potential broader deployment.
So gates one and two are complete, the integration work for gate three has been commissioned, and gates four and five remain ahead. No stage beyond that has been reached.
| Gate | What the customer decides | Who typically runs it | What the announcement looks like |
|---|---|---|---|
| 1. Centralised evaluation | Does the technology perform against our standards? | Central specialist assessment team | First instrument order after a long quiet period |
| 2. Formal global validation | Can we approve this for routine GMP use? | Quality and validation function | Follow-on order tied to a validation site |
| 3. Systems integration | Can we connect it to our global data systems? | Quality, IT and data governance teams | Order referencing integration or LIMS work |
| 4. Routine use | Is it running in live production? | Site operations and QC | Deployment update, often understated |
| 5. Site-by-site expansion | Do we roll this out across the network? | Network-level operations leadership | Multi-instrument orders across sites |
When the next follow-on order arrives, the useful question is not how many instruments it contains. It is which gate the order represents, because a gate-two order and a gate-five order tell you entirely different things about what is likely to follow. Some customers expand quickly, others take considerably longer, and some may not expand at all.
Why LIMS integration reshapes the economics of every site that follows
The September 2026 headline most investors saw was the instrument count: two more units, three in total. That is the number that travels.
The detail that sat lower in the announcement is the one that matters more. As part of that order, CC5 said Novo commissioned a bi-directional integration between APAS Independence and Novo’s global Laboratory Information Management System (LIMS).
A LIMS is the central nervous system of a pharmaceutical quality operation, managing samples, results, workflows, and records across the entire quality function, and modern implementations act as a central data hub rather than a passive filing system. Getting a new instrument connected to it is a serious piece of work, which is exactly why connecting to one is consequential.
Here is why the integration reshapes what follows:
- It is built once against the global system. The integration is designed against Novo’s global LIMS rather than a single site’s local configuration, so the engineering effort is not repeated from scratch at every location.
- It changes what APAS becomes. Before integration, an instrument is standalone laboratory equipment. Once embedded in a global quality system, it shifts from a piece of lab equipment into a component the quality function actively relies on.
- It changes the economics of the next site. Validation and integration are the two largest barriers to adding a site. With both addressed centrally, each additional site becomes a smaller decision than the first was.
Current LIMS practice is defined by formal system validation, deep instrument integration, and strict data-integrity controls, including 21 CFR Part 11 and GAMP 5. Direct instrument interfaces exist specifically to prevent data-integrity failures such as backdated entries, shared logins, unsecured raw data, and deleted records.
There is a second-order effect that matters even more for a supplier. Once a technology is embedded in a global quality system, switching platforms is no longer a straightforward instrument swap; it becomes a major GMP and business decision. That asymmetry sits in the supplier’s favour.
For you as an investor, this is the distinction to hold onto. The integration order matters not because of what it costs today but because of what it forecloses tomorrow. A follow-on order that deepens a relationship and one that simply adds capacity are not the same signal, and integration is how you tell them apart.
What integration does not guarantee
The honest qualification is that integration lowers the barrier to expansion. It does not guarantee expansion.
Each additional site remains an independent customer decision, made on the customer’s own schedule. Governance challenges, revalidation burdens, and local implementation work stay real at every site, and none of them disappears because central integration was completed.
Clever Culture Systems as the worked example
The company behind APAS Independence is Clever Culture Systems (CC5), an Adelaide-based developer whose platform applies artificial intelligence and machine learning to the imaging, analysis, and interpretation of microbiology culture plates. That is work traditionally done by hand by microbiologists.
CC5 targets large global pharmaceutical manufacturers deliberately. They are the customers with the capacity to evaluate a technology centrally and then deploy it across many sites, which is precisely the gate sequence described above.
The commercial model matters here. Each instrument placement generates ongoing software, support, and maintenance revenue on top of the initial instrument transaction, so a growing installed base compounds rather than resets each year.
For investors wanting to understand why CC5’s FDA clearance functions as a structural barrier rather than a temporary advantage, our dedicated guide to CC5’s competitive position covers the clearance process, the 0% false negative rate from independent validation testing, and the customer list across the world’s twenty largest pharmaceutical manufacturers.
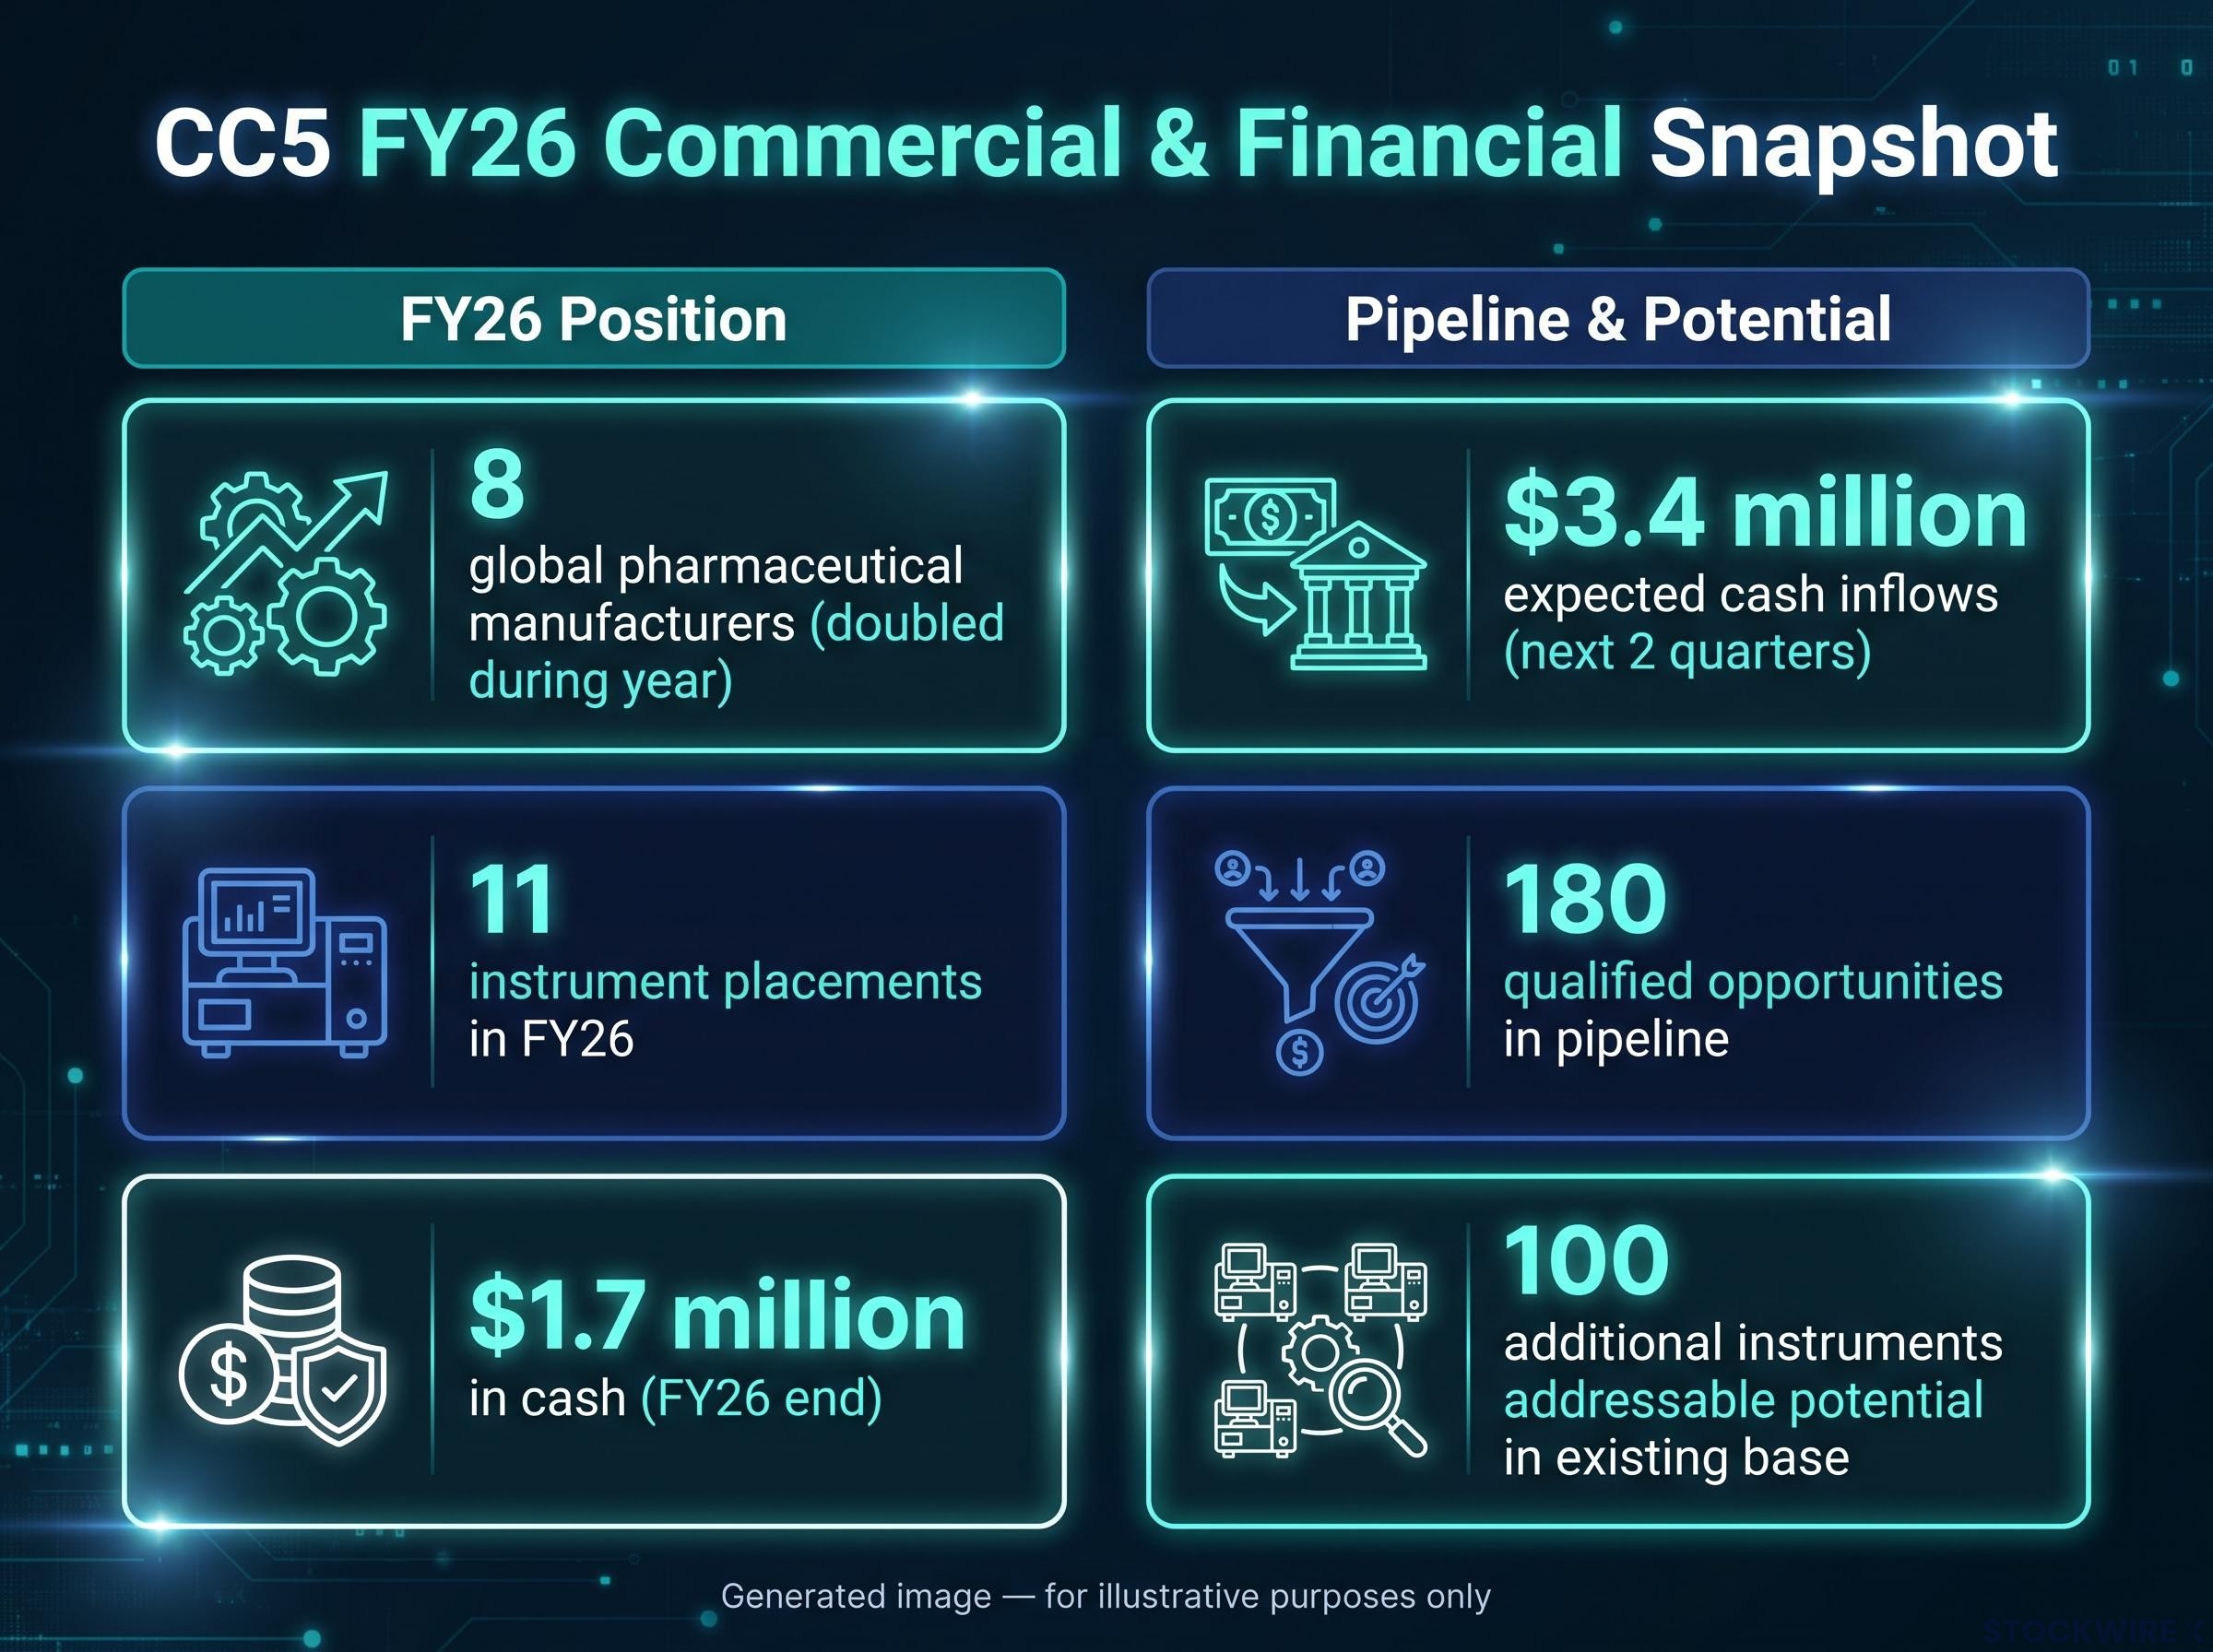
On the FY26 commercial position, CC5 reported that eight global pharmaceutical manufacturers now have APAS installed, meaning its big pharma customer base doubled during the year. It recorded 11 instrument placements across FY26.
The funding position is best read as three facts sitting together, based on CC5’s Q4 FY26 quarterly report:
- CC5 finished FY26 with $1.7 million in cash.
- It expects at least $3.4 million in known or committed cash inflows over the following two quarters.
- In Q4 it drew on a short-term debt facility to support working capital and inventory purchases.
Those three facts belong together for a reason. See only the cash figure and the position looks tight; see only the committed inflows and it looks comfortable; see only the debt draw and it looks strained. All three are needed to form a view on execution timing risk, which is the risk that matters most for a company moving customers through a long gate sequence.
CC5 says its pharmaceutical customer user group, expected to meet three to four times a year, could act as a collective voice to industry and regulators on automation in pharmaceutical quality control.
That user group is easy to overlook, but it illustrates the strategic intent behind concentrating on a small number of large customers rather than chasing volume.
What management expects from FY27, and what the framework does not settle
Management’s forward view is specific. According to CC5’s FY26 reporting and investor materials, management expects FY27 to deliver a step change in sales growth, with the majority of that growth anticipated from existing customers rather than new ones.
The logic behind that expectation was set out by the CEO on an investor call. If several large customers each add two or three instruments, CC5 has said, the aggregate becomes meaningful even though each customer moves on its own cadence.
CC5 also points to the scale of the opportunity within its current base. The company estimates roughly 100 additional instruments of addressable potential within the existing eight-customer base, and reports a pipeline of 180 qualified opportunities. Both figures are company estimates of potential, not confirmed orders, and should be read that way every time they appear.
That is the optimism. The framework built across this article also makes the conditions attached to it visible:
- Reaching formal validation is not the same as routine deployment. Gate two closing does not mean gates four and five are close.
- Progress at one customer is not evidence of equivalent progress at another. Novo Nordisk is the furthest along publicly; other customers sit at earlier or different stages.
- The 100-instrument and 180-opportunity figures describe potential, not orders. They are company estimates of addressable demand.
- Execution timing matters, because the FY27 expectation depends on customers moving through the gate sequence broadly on the timeline CC5 anticipates.
The gap between 180 qualified opportunities and confirmed orders is where execution risk lives. If you carry the pipeline figure in your head without its label attached, you will tend to weight it more heavily than it warrants.
The value of the gate framework here is that it turns the FY27 outlook into something you can watch rather than simply wait on. Instead of waiting to see whether the year lands, you can track which gates each customer clears as the year unfolds.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Financial projections are subject to market conditions and various risk factors, and past performance does not guarantee future results.
Reading the next announcement differently
Come back to where this started: an investor waiting for news from a regulated-industry supplier, twelve months into a silence that feels like stalling.
Those twelve months Novo Nordisk spent evaluating APAS were never a pause. They were gate one, and the September 2026 order confirmed both that it had closed and that gates two and three were now actively in progress. The silence was the work.
That reframes what a follow-on order is for. It is far more useful as evidence of which gate a customer has reached than as a count of instruments, and the LIMS integration is the element most likely to matter over the longer horizon, because of what it does to the economics of every site that follows.
The lesson extends well beyond one company. In regulated industries generally, whether medical devices, diagnostics, or other controlled manufacturing, the silence between orders is where the real work happens. Land-and-expand in these settings is a multi-year operational change, conditional on sustained investment in validation, data governance, and user adoption.
Investors who mis-read pharmaceutical regulatory timelines in one context tend to make the same error across adjacent sectors; the qualification sequence described here and the bioequivalence pathways that govern reformulation companies share the same underlying logic: a defined, documented, non-negotiable process that cannot be shortened by commercial pressure.
Knowing the gate sequence gives you something specific to watch instead of a calendar to count down. That is the tool worth keeping: not a view on one stock, but a lens for reading any supplier selling into a regulated industry.