
Q3 FY26 highlights: YTD revenue receipts up 72% to $6.9 million
In its Q3 FY26 quarterly shareholder update, Volt Group Limited (ASX: VPR) reported Group YTD FY26 Ordinary Revenue receipts of $6.9 million, up 72% on the prior YTD FY25 comparison of $4.0 million. The result includes 4D Delta revenue receipts from the 6 January 2026 acquisition settlement date.
Q3 FY26 Ordinary Revenue receipts totalled $1.8 million, down 3% from $1.85 million in Q3 FY25. Group YTD Net Operating Cashflow, excluding one-off 4D Delta acquisition costs of $0.52 million, reached $2.05 million, up 63% from $1.26 million.
The company also received a $0.4 million ATO R&D Tax Rebate and held cash at bank of $3.53 million as at 30 September 2026.
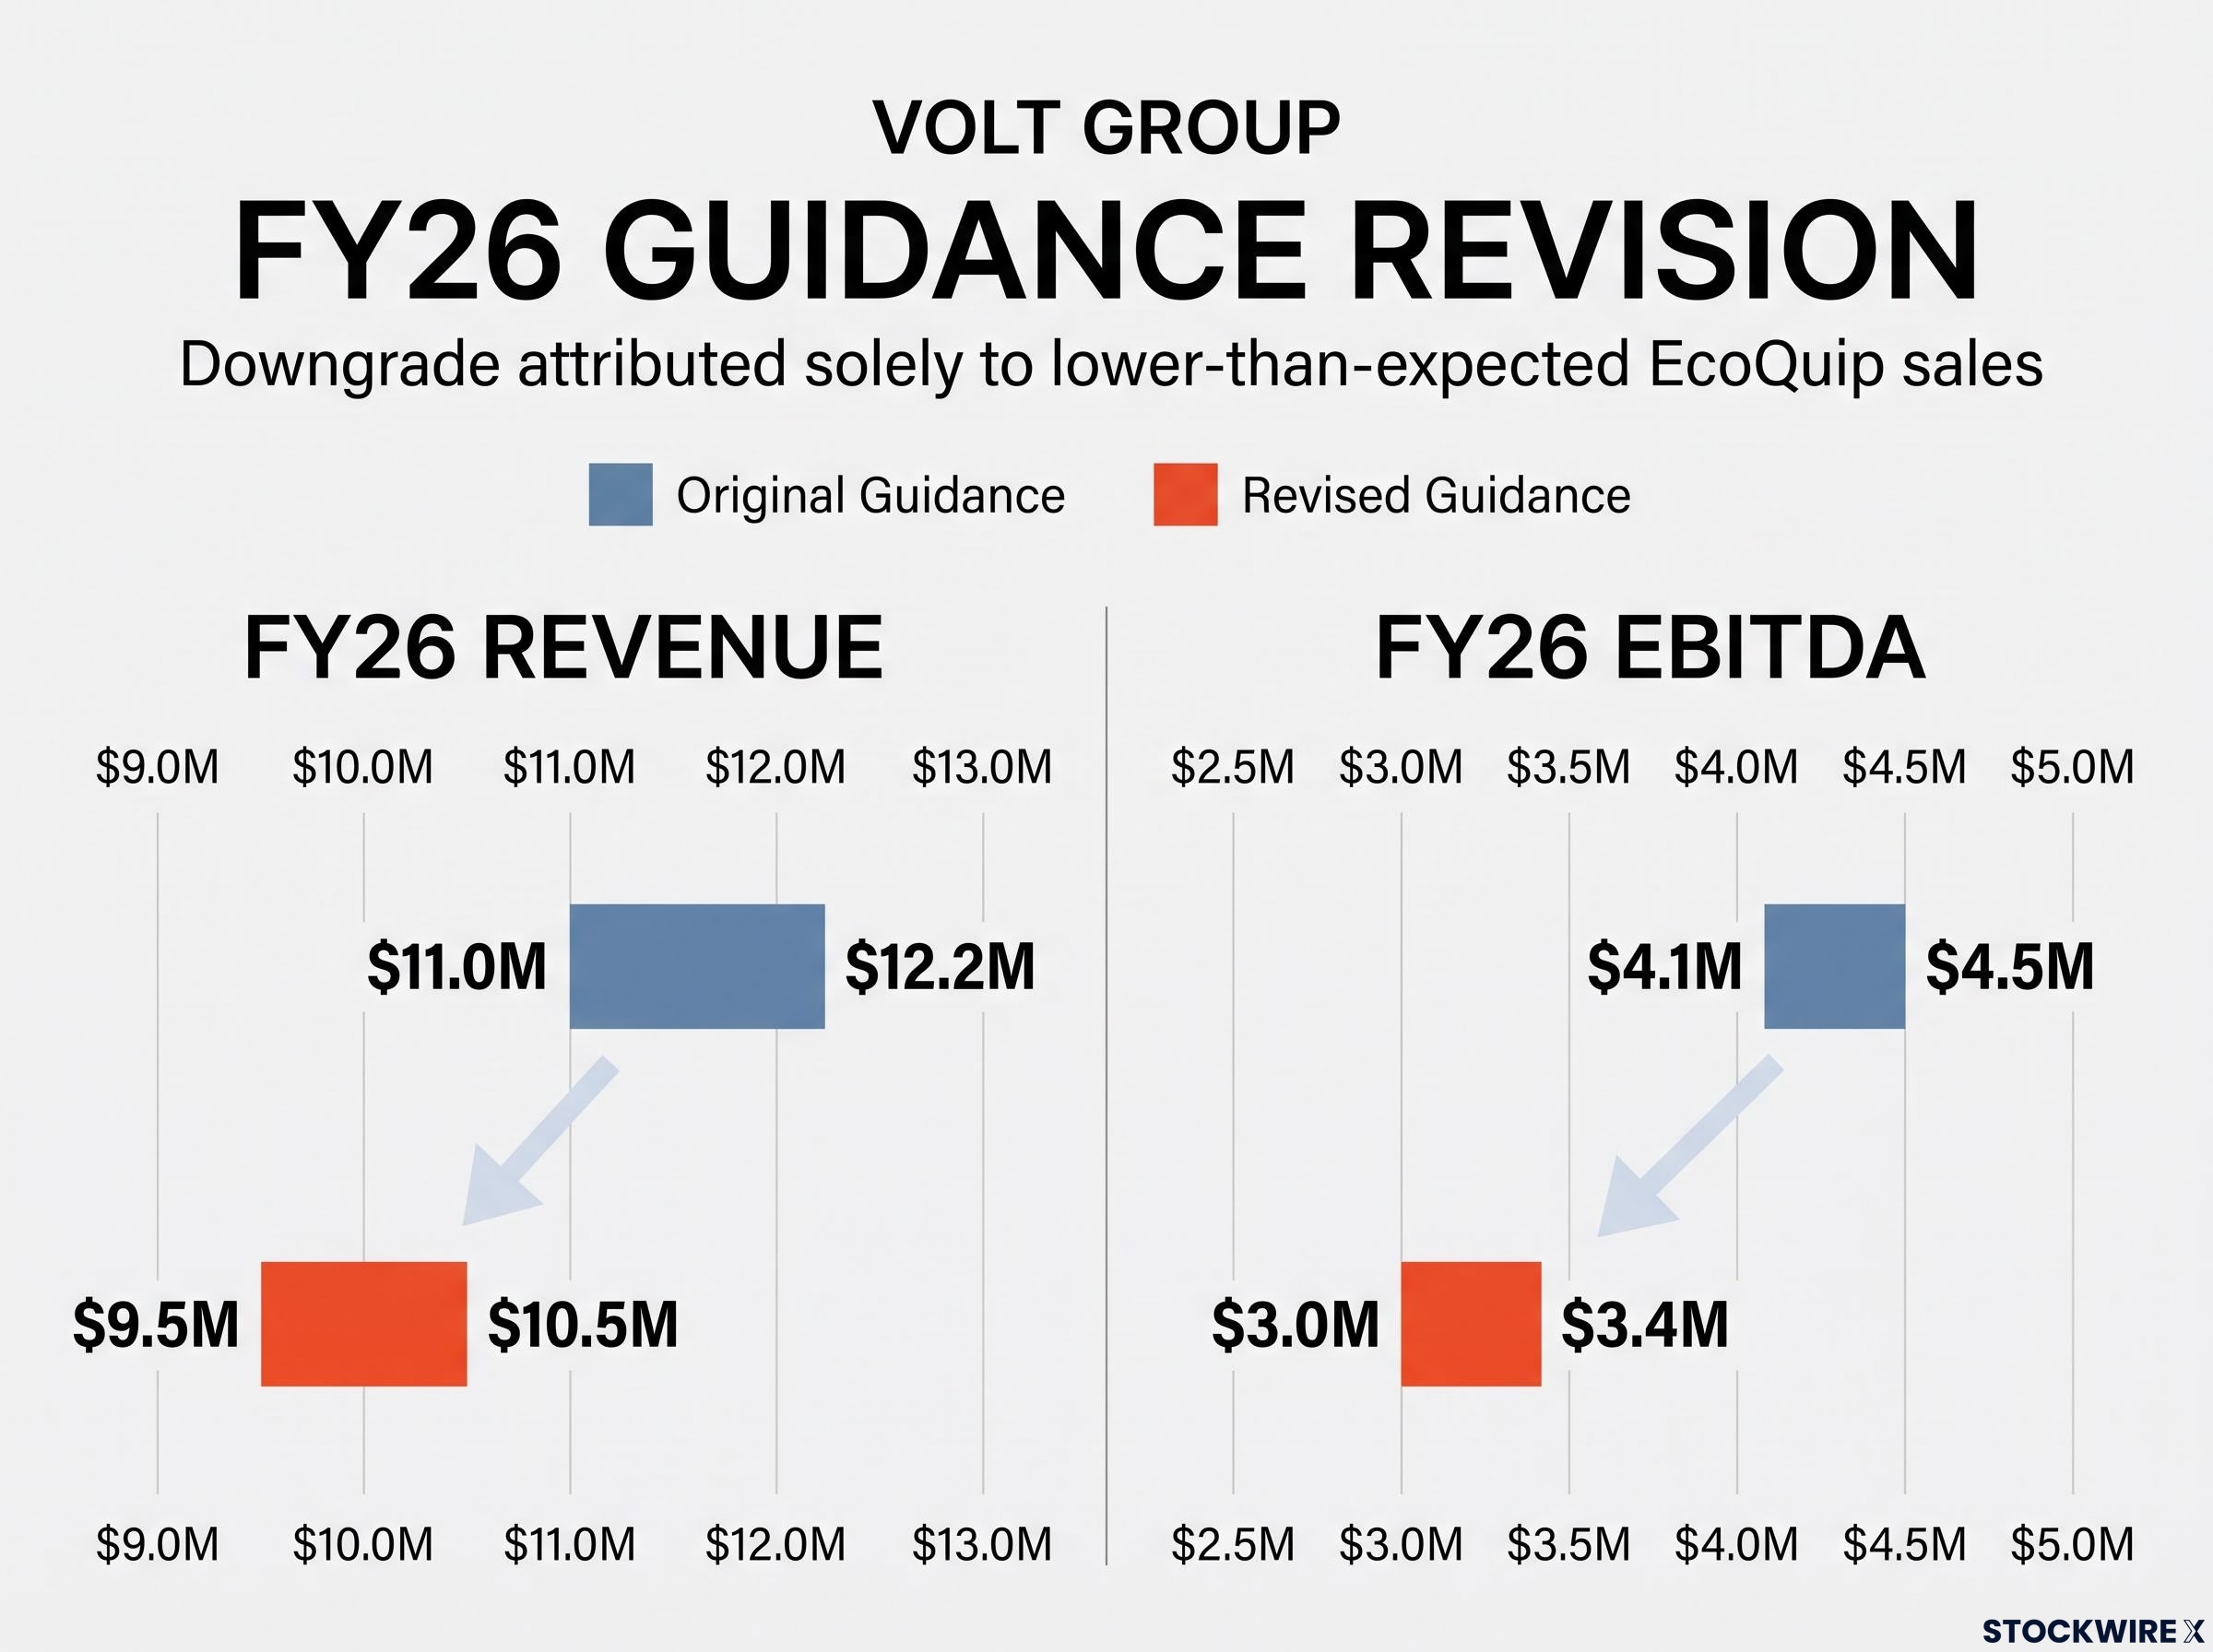
Guidance moved the other way. Volt Group downgraded its FY26 revenue and EBITDA guidance, which it attributed solely to lower-than-expected EcoQuip sales.
| Metric | Original guidance | Revised guidance |
|---|---|---|
| Revenue | **$11.0M to $12.2M** | **$9.5M to $10.5M** |
| EBITDA | **$4.1M to $4.5M** | **$3.0M to $3.4M** |
Executive Chairman Adam Boyd framed the period around the cash result.
Adam Boyd, Executive Chairman
“The Volt Board is pleased to confirm that the Company achieved a record $6.9 million in net Ordinary Revenue receipts and Net Operating Cashflow of $2.05 million (excluding ‘one-off’ 4D Delta acquisition transaction costs of $0.52 million) for the 9-month period to 30 September 2026…”
Mr Boyd said the Wescone and 4D Delta businesses continued to deliver sales and earnings in line with the FY26 Board Approved Budget, while EcoQuip performed below expectations.
When big ASX news breaks, our subscribers know first
Segment performance across 4D Delta, Wescone and EcoQuip
Group YTD Ordinary Revenue receipts excluding the 4D Delta business totalled $3.39 million, down 15% from $4.0 million a year earlier. The segment figures show where that gap sits.
| Segment | Q3 FY26 | Q3 FY25 | YTD FY26 | YTD FY25 |
|---|---|---|---|---|
| 4D Delta | **$0.93M** | n/a | **$3.47M** | n/a |
| Wescone | **$0.50M** | **$1.27M** | **$2.23M** | **$2.30M** |
| EcoQuip | **$0.37M** | **$0.58M** | **$1.16M** | **$1.71M** |
4D Delta tracks to acquisition budget
4D Delta recorded Q3 revenue receipts of $0.93 million and YTD receipts of $3.47 million. The YTD result was in line with acquisition budget forecasts.
The 4D Delta acquisition was pitched as doubling the group revenue base and adding Tier 1 clients such as Rio Tinto, BHP, Alcoa and South32, which is why its budget tracking carries weight for the group result.
Customer assets on its proprietary asset condition monitoring / management platform rose 5% to 927 during Q3 FY26, and are up 21% YTD. The business continued to engage multiple resource sector customers, including multiple iron ore site operations, gold and lithium miners, and potential distribution partners in Europe and the Middle East.
Wescone steady despite BHP offset
Wescone Q3 receipts were $0.50 million, against $1.27 million in Q3 FY25. YTD receipts of $2.23 million compared with $2.30 million, a 3% decline.
Cash receipts were reduced by higher-than-expected BHP Service Exchange crusher returns revenue off-set / payments, which totalled $0.35 million in Q3 FY26. The HY26 Interim Financial Report included a provision for the entire $0.35 million.
The earnings picture behind that provision is set out in the HY26 Interim Financial Report, where half-year revenue rose 122% and the group swung to a profit attributable to members.
Africa Distribution Partner Mineral Innovative Technologies (MIT) continued to build sales momentum during FY26. MIT has ordered two new crushers for delivery during Q4 FY26.
EcoQuip: reliability proven, sales lagging
EcoQuip Q3 receipts were $0.37 million (Q3 FY25: $0.58 million), while YTD receipts of $1.16 million were down 32% from $1.71 million.
Operationally, the deployed 65x MSLT fleet achieved 99% availability during Q3. New Q2 deployments at four Westgold owned and operated gold mines performed reliably through the winter months.
How solar and battery lighting towers cut diesel dependence
A mobile solar lighting tower (MSLT) is a portable lighting and communications unit powered by solar panels and stored battery energy rather than a diesel generator. EcoQuip describes its tower as incorporating a solar / lithium (LFP) battery storage system and an advanced power management, data telemetry and control system.
According to Mr Boyd, the EcoQuip MSLT has significant cost, asset management, safety, emissions and illumination performance competitive advantages compared with alternative generic solar light solutions and traditional diesel fuelled lighting plant. EcoQuip solutions are described as capable of zero emission, high-performance mobile illumination.
Fuel prices are part of the sales case. Mr Boyd said the cost benefit of reliable equipment electrification has been significantly enhanced by the tail winds of high diesel fuel prices.
The company said diesel price inflation and focused effort from its new sales talent has initiated multiple EcoQuip MSLT site trial activities. Management said it looks forward to potential customers experiencing the reduced cost and maintenance requirements of the MSLT and its cloud portal.
For investors, the link is direct: EcoQuip is the segment behind the guidance downgrade, and higher diesel costs strengthen the commercial case for its recovery.
Restructure, new COO and the $3.0 million EcoQuip capital commitment
The Board initiated a management restructure of EcoQuip in June 2026 to accelerate its transition from its technology development history to a commercially focused operation. The new operational management and sales talent were appointed in July 2026, and the restructure is now complete.
Byron Hoy joined as Chief Operating Officer in October. He will lead the sales growth strategy across EcoQuip, 4D Delta and Wescone, and the company described his career as including a multi-decade history of product and global resource sector sales success.
In September 2026, the Board approved a $3.0 million Capital Investment. It covers the manufacture of 50x MSLTs, 50x MSLT refurbishments and two R&D projects, which are expected to enhance MSLT mechanical, illumination and reliability specifications.
The refurbishment of ~50x returned MSLTs has advanced to more than 50% complete. Together, the new and refurbished units will give the sales team 100x EcoQuip MSLTs for deployment over the period ending July / August 2027.
Mr Boyd said the commitment reflects the Board’s view of EcoQuip’s growth potential, despite its 2026 sales performance.
Cashflow and reporting
Cash payments for Q3 FY26 totalled $2.03 million. Net cashflow from operations was $0.2 million, investing activities were ($0.3) million and financing activities were nil.
The ASX has removed Volt Group’s classification as a commitment test entity, following consistent positive net operating cashflows over several years. The company is no longer required to lodge an Appendix 4C, but said it will continue to provide quarterly updates on activities and cashflow as a matter of good governance.
What happens next for Volt Group
The update set out several milestones, with timing as stated by the company:
- First 20x new MSLTs: planned assembly completion by 31 March 2027.
- $3.0 million Capital Investment programme (50x MSLTs, 50x refurbishments and two R&D projects): completion during the period ending 31 July 2027, with new MSLTs completed in 3 Tranches.
- 100x MSLTs for EcoQuip deployment: available over the period ending July / August 2027.
- MIT’s two new Wescone W300 crushers: scheduled for delivery in Q4 FY26.
- EcoQuip MSLT site trials: expected to start shortly, with vendor registrations with potential customers advanced.
The 4D Delta team also continued implementing its recently completed Advanced Data Processing software upgrade, including a post processing QA/QC review to validate software performance and efficiency benefits.
Don’t Miss the Next ASX Utilities Winner
Get FREE breaking ASX news in your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors already staying ahead of the market with Big News Blast. Click the “Free Alerts” button to receive real-time alerts the moment market-moving announcements break.