
Q3 2026 highlights: EBITDA already beats all of FY2025
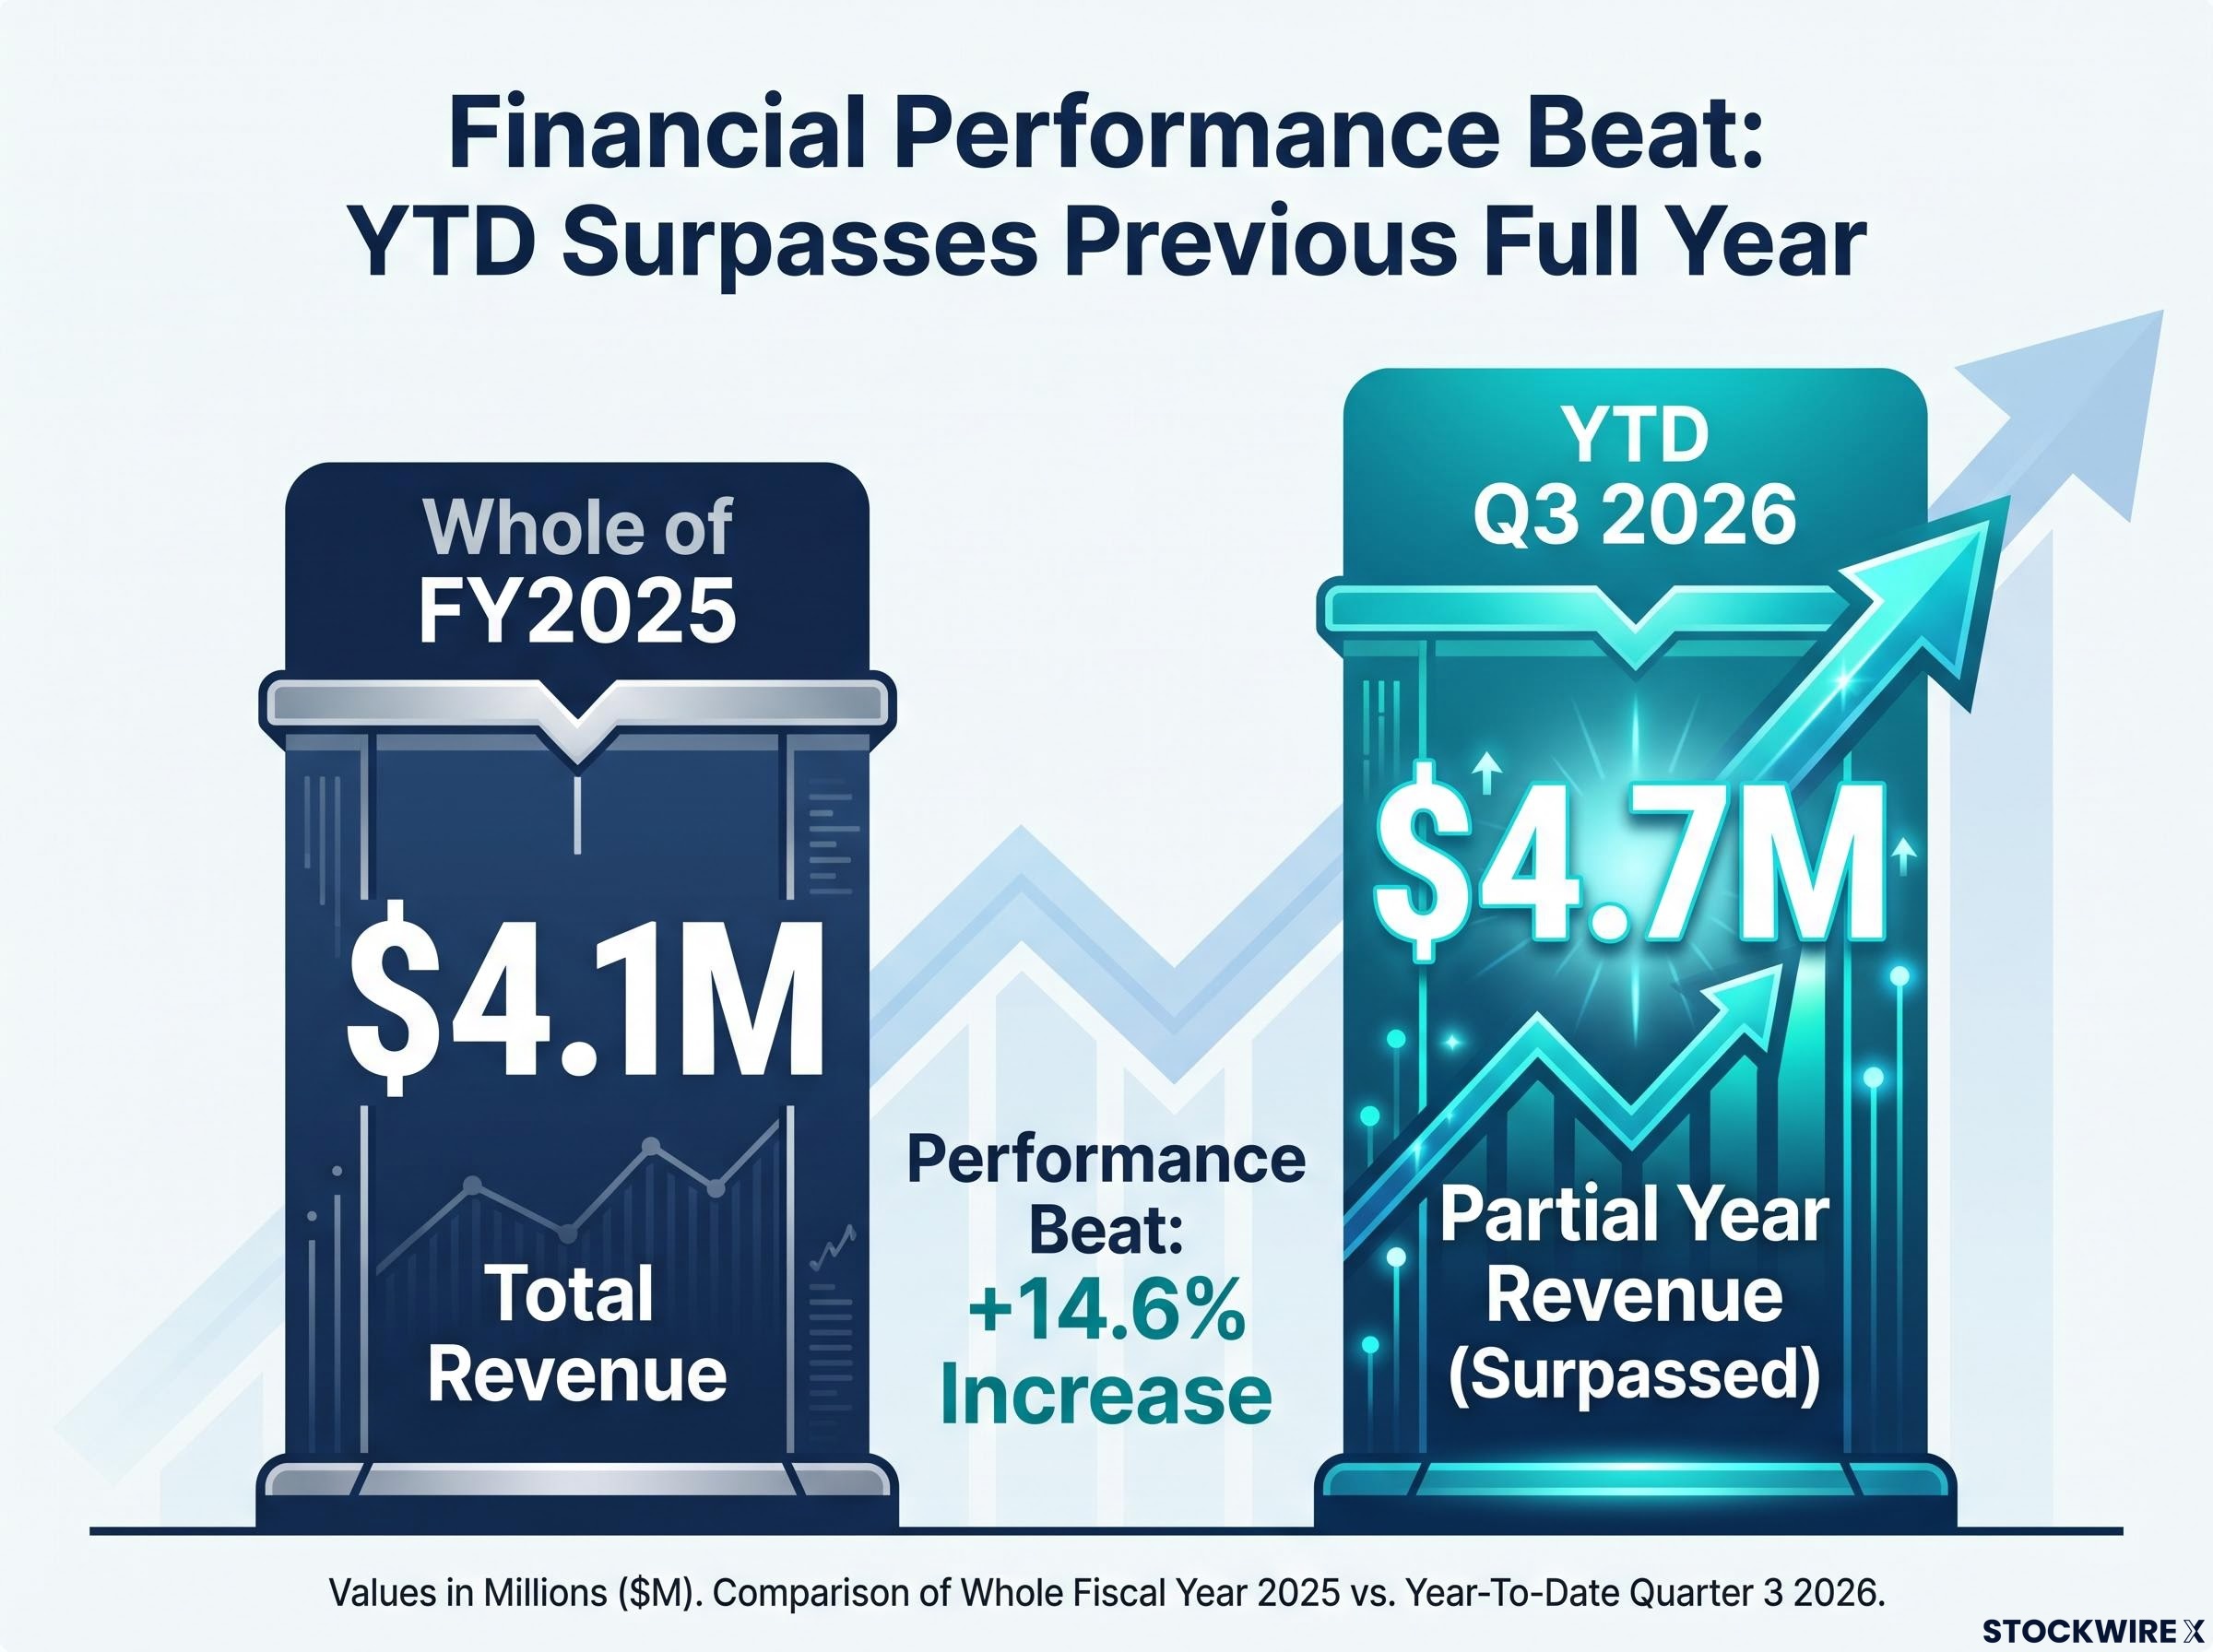
In its Q3 2026 investor presentation, Fluence Corporation outlined year-to-date (YTD) EBITDA of $4.7M, already above the $4.1M recorded for the whole of FY2025. Management also indicated that positive EBITDA is expected in Q4 2026, with the water treatment group’s results shown as subject to audit.
The company highlighted the following figures for the period:
- YTD Q3 2026 revenue of $58.0M, up 11.3% on YTD Q3 2025
- SPS plus Recurring revenue up 38.5% year on year ($12.5M), and up 44.6% in Q3 2026
- Gross margin of 35.2%, an increase of 6.2 percentage points on YTD Q3 2025
- Q3 2026 EBITDA of $1.3M, the 8th straight positive quarter since Q4 2024
- Cash of $6.7M, plus $4.0M in security deposits
EBITDA excludes the impact of Other Gains and Losses, which include FX gains and losses, gains and losses related to various legacy balance sheet items, restructuring, and other non-recurring items.
Q3 operating cash outflow was $4.3M, which management attributed primarily to the timing of 2 large receipts (over $5.5M) for IVC 2025 O&M fees and Qurayyah WTP, both expected imminently. Q4 2026 operating cashflow is expected to be positive, supported by IVC Addendum milestone 8 and other large customer receipts.
“Management continues to expect double-digit revenue growth in FY2026 across its core business units along with another year of significant EBITDA growth”
Business unit performance
The presentation set out revenue and EBITDA by business unit for YTD Q3 2025 and YTD Q3 2026, in US$ millions.
| Business unit | YTD Q3 2025 EBITDA | YTD Q3 2026 EBITDA | YTD Q3 2026 revenue | Revenue variance |
|---|---|---|---|---|
| Municipal Water & Wastewater | $1.2 | $0.5 | $9.4 | $1.8 |
| Industrial Wastewater & Biogas | $0.8 | $1.6 | $12.1 | $3.6 |
| Industrial Water & Reuse | $2.2 | $1.2 | $12.0 | $0.1 |
| SEA & China | ($0.4) | $0.3 | $5.9 | $1.8 |
| BOO | $0.4 | $0.5 | $1.9 | ($0.1) |
| IVC | $2.6 | $6.5 | $17.8 | ($1.7) |
| Corporate | ($5.4) | ($5.9) | ($1.1) | $0.4 |
| Total | $1.4 | $4.7 | $58.0 | $5.9 |
Industrial Wastewater & Biogas posted revenue of $12.1M and EBITDA of $1.6M, while SEA & China moved from an EBITDA of ($0.4M) to $0.3M. IVC delivered EBITDA of $6.5M.
Municipal Water & Wastewater EBITDA was $0.5M against $1.2M a year earlier, and Industrial Water & Reuse EBITDA was $1.2M against $2.2M.
When big ASX news breaks, our subscribers know first
Orders, backlog and the Q4 2026 setup
Q3 2026 new orders were $8.0M, taking YTD orders to $31.6M. Trailing twelve month (TTM) orders of $56.1M remain 14% above Q3 2025.
Repeat business is a feature of the order book, with two Vietnam desalination contracts on Phu Quoc Island worth US$3.7M marking the 4th and 5th deals with the same regional partner in just over a year.
Management said several larger awards slipped on customer investment timing, and most are delayed rather than lost. Q4 2026 is forecast to be the strongest order bookings quarter of the year.
Backlog stood at $47.1M at Q3 2026, down from $56.6M in Q2 2026 because of strong revenue recognition, and not replaced as several larger order bookings were delayed. The presentation described this as sufficient work to deliver strong growth in FY2026.
The company listed several notable orders from Q3 and October 2026:
- Qurayyah ETP (Saudi Arabia): $2.3M NIROBOX™ effluent treatment plant (repeat customer)
- IVC O&M maintenance services: $1.3M
- iTest (SEA & China): $2.0M Aspiral MABR WWTPs (repeat customer)
- Red Bluffs (IWR USA): $0.6M BWRO, the 2nd order in the USA in successive quarters
- Climax Molybdenum (IWB USA): $0.2M WWTP
- South Platte (MWW USA): Aspiral MABR pilot, described as a key strategic win in Colorado
Ivory Coast project and the shift to recurring revenue
The company described the Ivory Coast legacy CES project as nearing completion. Main Works are valued at €164M and Addendum Works at €48M.
Provisional Acceptance on the Main Works was granted on 27 December 2024, and all Main Works payments have been made. As of the end of Q3 2026, seven milestone payments totalling €42.4M, approximately 87.6% of the project, had been collected on the Addendum Works.
On the O&M contract, management completed a week of in-person negotiation sessions in September and resolved a significant amount of the remaining open issues. Contract pricing negotiation is ongoing.
The H1 2026 investor presentation described the Ivory Coast O&M negotiation as slow, with Fluence still positioning itself for the award and targeting a Q3 2026 signing date.
What SPS and recurring revenue mean for investors
SPS stands for Smart Product Solutions, which are modular, decentralised units such as NIROBOX™ and Aspiral™. Recurring Revenue (RR) covers items such as Treatment-as-a-Service and O&M.
SPS is now 57% of revenue compared with 29% in FY2022, while RR is 18% of total revenue. The presentation showed illustrative gross margins that rise as the mix moves away from large projects:
| Product line | Illustrative GM% |
|---|---|
| Large Projects | 15% |
| Smart Product Solutions | 25% |
| Proprietary Smart Product Solutions | 35% |
| Waste to Energy | 30% |
| Recurring Revenue | 40% |
These margins are illustrative figures from the presentation, not reported results.
Strategy and margin outlook
Ivory Coast accounted for 58% of revenue in 2022 and 30% on a TTM Q3 2026 basis, with a medium-term target of 10%. North America & Caribbean stands at 8% of TTM revenue against a medium-term target of 30%, and Municipal Water & Wastewater at 3% against 29%.
SG&A and R&D have been reduced by 25% since FY2022. Management is targeting double-digit EBITDA margins in the next 2-3 years, from a TTM Q3 2026 EBITDA margin of 8.8% on TTM revenue of $84M.
Growth levers outlined include:
- Build-out of the sales team and rep network
- Growth in water services revenue
- Opportunistic tuck-in M&A that prioritises O&M, service and strong recurring revenue businesses
On the market, the presentation cited a global water and wastewater treatment market expected to reach $957B by 2032 at a CAGR of 5.4%, and a US EPA assessed need to spend more than $200B on municipal upgrades over the next 20 years.
What happens next for Fluence
The presentation points to the following milestones:
- Q4 2026: Strongest new order bookings quarter of the year forecast, as delayed awards are expected to close.
- Q4 2026: Positive operating cashflow expected, supported by IVC Addendum milestone 8 and other large customer receipts. Two large receipts (over $5.5M) for IVC 2025 O&M fees and Qurayyah WTP are expected imminently.
- Q4 2026: Positive EBITDA expected.
- By year-end: Remaining bridge and swamp stabilisation works on the Ivory Coast Addendum scheduled for completion.
- Q1 2027: Final Acceptance on the Ivory Coast Main Works scheduled.
- Ongoing: O&M contract pricing negotiation continues.
Don’t Miss the Next Water Technology Winner
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, complete with in-depth analysis. Click the “Free Alerts” button at Big News Blast to receive real-time alerts the moment market-moving news breaks, and stay ahead of the market.