

IKE subscription revenue up 22% as exit run rate hits ~NZ$22M
IKE (ikeGPS Group Limited) (NZX: IKE | ASX: IKE) reported Platform Subscription Revenue of ~NZ$11M for the September year to date, up 22% vs the prior calendar period (pcp), in its update for the six-month period to 30 September 2026. Annualized Exit Run Rate (ERR) of subscription revenue reached ~NZ$22M, up 13% vs pcp.
The 2Q / 1H FY27 performance update, released on 23 October 2026, showed ~85% of total revenue from recurring subscriptions, compared with 69% in the pcp. The company reported no debt as at 30 September 2026. All figures are in NZD.
The update also reset expectations on full-year growth. Management said FY27 subscription revenue growth is strong but will land below the ~35% previously indicated, with the updated forecast to be confirmed at the end of November.
When big ASX news breaks, our subscribers know first
Half-year financials: margins expand, cash ahead of plan
Total revenue was approximately flat, while gross margin improved as the revenue mix moved toward subscriptions.
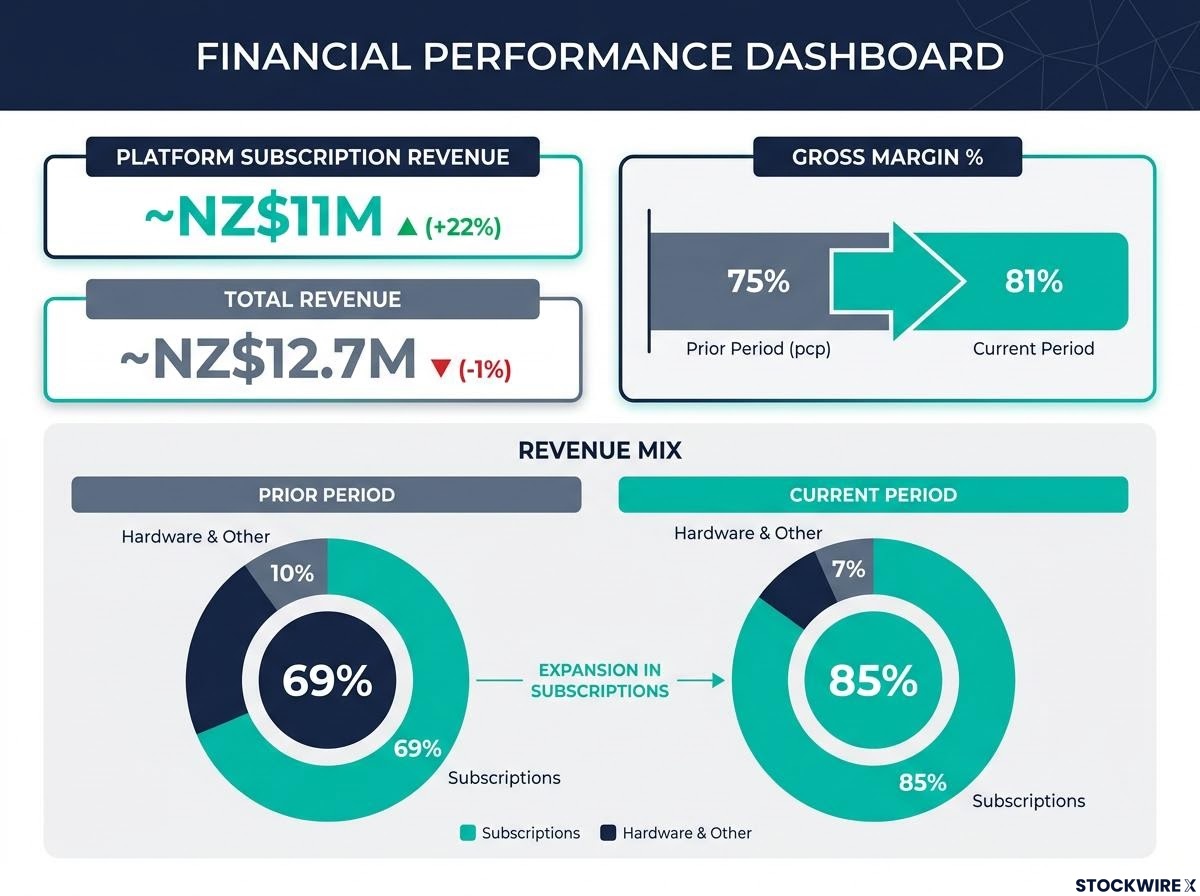
Key metrics
| Metric | Sep YTD FY27 | vs pcp |
|---|---|---|
| Platform Subscription Revenue | **~NZ$11M** | **+22%** |
| Total Revenue | **~NZ$12.7M** | **-1%** (approximately flat) |
| Gross Margin | **~NZ$10.2M** | **+7%** |
| Gross margin percentage | **81%** | **75%** pcp |
| Seat count (30 September) | n/a | **+11%** |
Cash and balance sheet
IKE held total cash and deposits of ~NZ$27.4M and net receivables of ~NZ$3.9M, with no debt, as at 30 September 2026.
Cash was ahead of the internal plan. The company noted that the ending balance reflects payment timing of a large receivable and 2Q being a seasonally higher spend quarter.
Why total revenue was flat
Professional Services Revenue (formerly Platform Transaction Revenue) fell 61% vs pcp. The company described this as one-off, lower margin work, and said total revenue reflected “some interim softness” in that category.
The softness follows a 35% decline in Platform Transaction Revenue in the FY26 subscription results, where U.S. federal policy volatility around rural fibre funding was flagged as a timing headwind expected to persist into early FY27.
Management said September revenue was strong and Q3 will be strong due to a growing backlog. Non-recurring Hardware & Other Revenue dropped to 7% of revenue from 10% in the pcp, while subscriptions rose to 85%, alongside the gross margin rise from 75% to 81%.
Understanding exit run rate and recurring revenue
Annualized Exit Run Rate (ERR) of subscription revenue is the annualised value of subscription revenue at the end of a period. For several major subscription contracts, the associated subscription revenue is recognised over the subsequent 12-month period from execution.
This matters because contract timing can lag headline growth. A contract signed late in a period adds to the run rate but contributes little recognised revenue until later periods.
CEO and Managing Director Glenn Milnes pointed to subscription gross margins of ~95%, an NPS (Net Promoter Score, a customer satisfaction measure) of 91, and a balance sheet with no debt. The update also set out three-year Compound Annual Growth Rates (CAGR):
- Annualized Exit Run Rate: +29%
- Platform subscription revenue: +28%
- Seat count: +31%
Guidance in context
Management expects IKE’s exit run rate of platform subscription revenue at 31 March 2027 to grow >30% versus the pcp.
Mr Milnes attributed the lower full-year outlook to the timing of closing and recognising several major subscription contracts. He said the company has customer contracts in place and visibility into a strong sales pipeline.
Glenn Milnes, CEO & Managing Director
“It does not reflect demand, customer losses, nor churn…”
Three new subscription products on track for 2H FY27
IKE said three new subscription products funded in FY26 are on track:
- IKE PoleForeman, Secondary Voltage Analysis (Module 1): extends IKE into the electrical delivery side of distribution-grid management and replaces legacy and unsupported tools.
- IKE PoleForeman 2.0 for the communications industry: opens an additive addressable market in the U.S. fibre-infrastructure segment.
- IKE AI Make-Ready Engineering platform (Module 2): automates and accelerates a historically manual, time-intensive workflow.
Each product was shaped by direct engagement with IKE’s Customer Council of leading North American electric utilities. They are targeted to be in market in 2H FY27 and are expected to deliver material recurring subscription revenue from FY28.
The products will be demonstrated at the next investor call in November. Management also said electrification macro-market tailwinds across North America remain highly supportive and are strengthening.
The key near-term catalyst is the end-of-November update, when IKE has said the full-year subscription growth forecast will be confirmed.
Don’t Miss the Next Tech Breakout on the ASX
Join 20,000+ investors receiving FREE breaking ASX news within minutes of release, complete with in-depth analysis already done. Click the “Free Alerts” button at Big News Blast to get tech announcements in your inbox the moment they break, and stay ahead of the market.