
Warburg Pincus proposal lifts Ingenia bid to $5.55 cash per stapled security
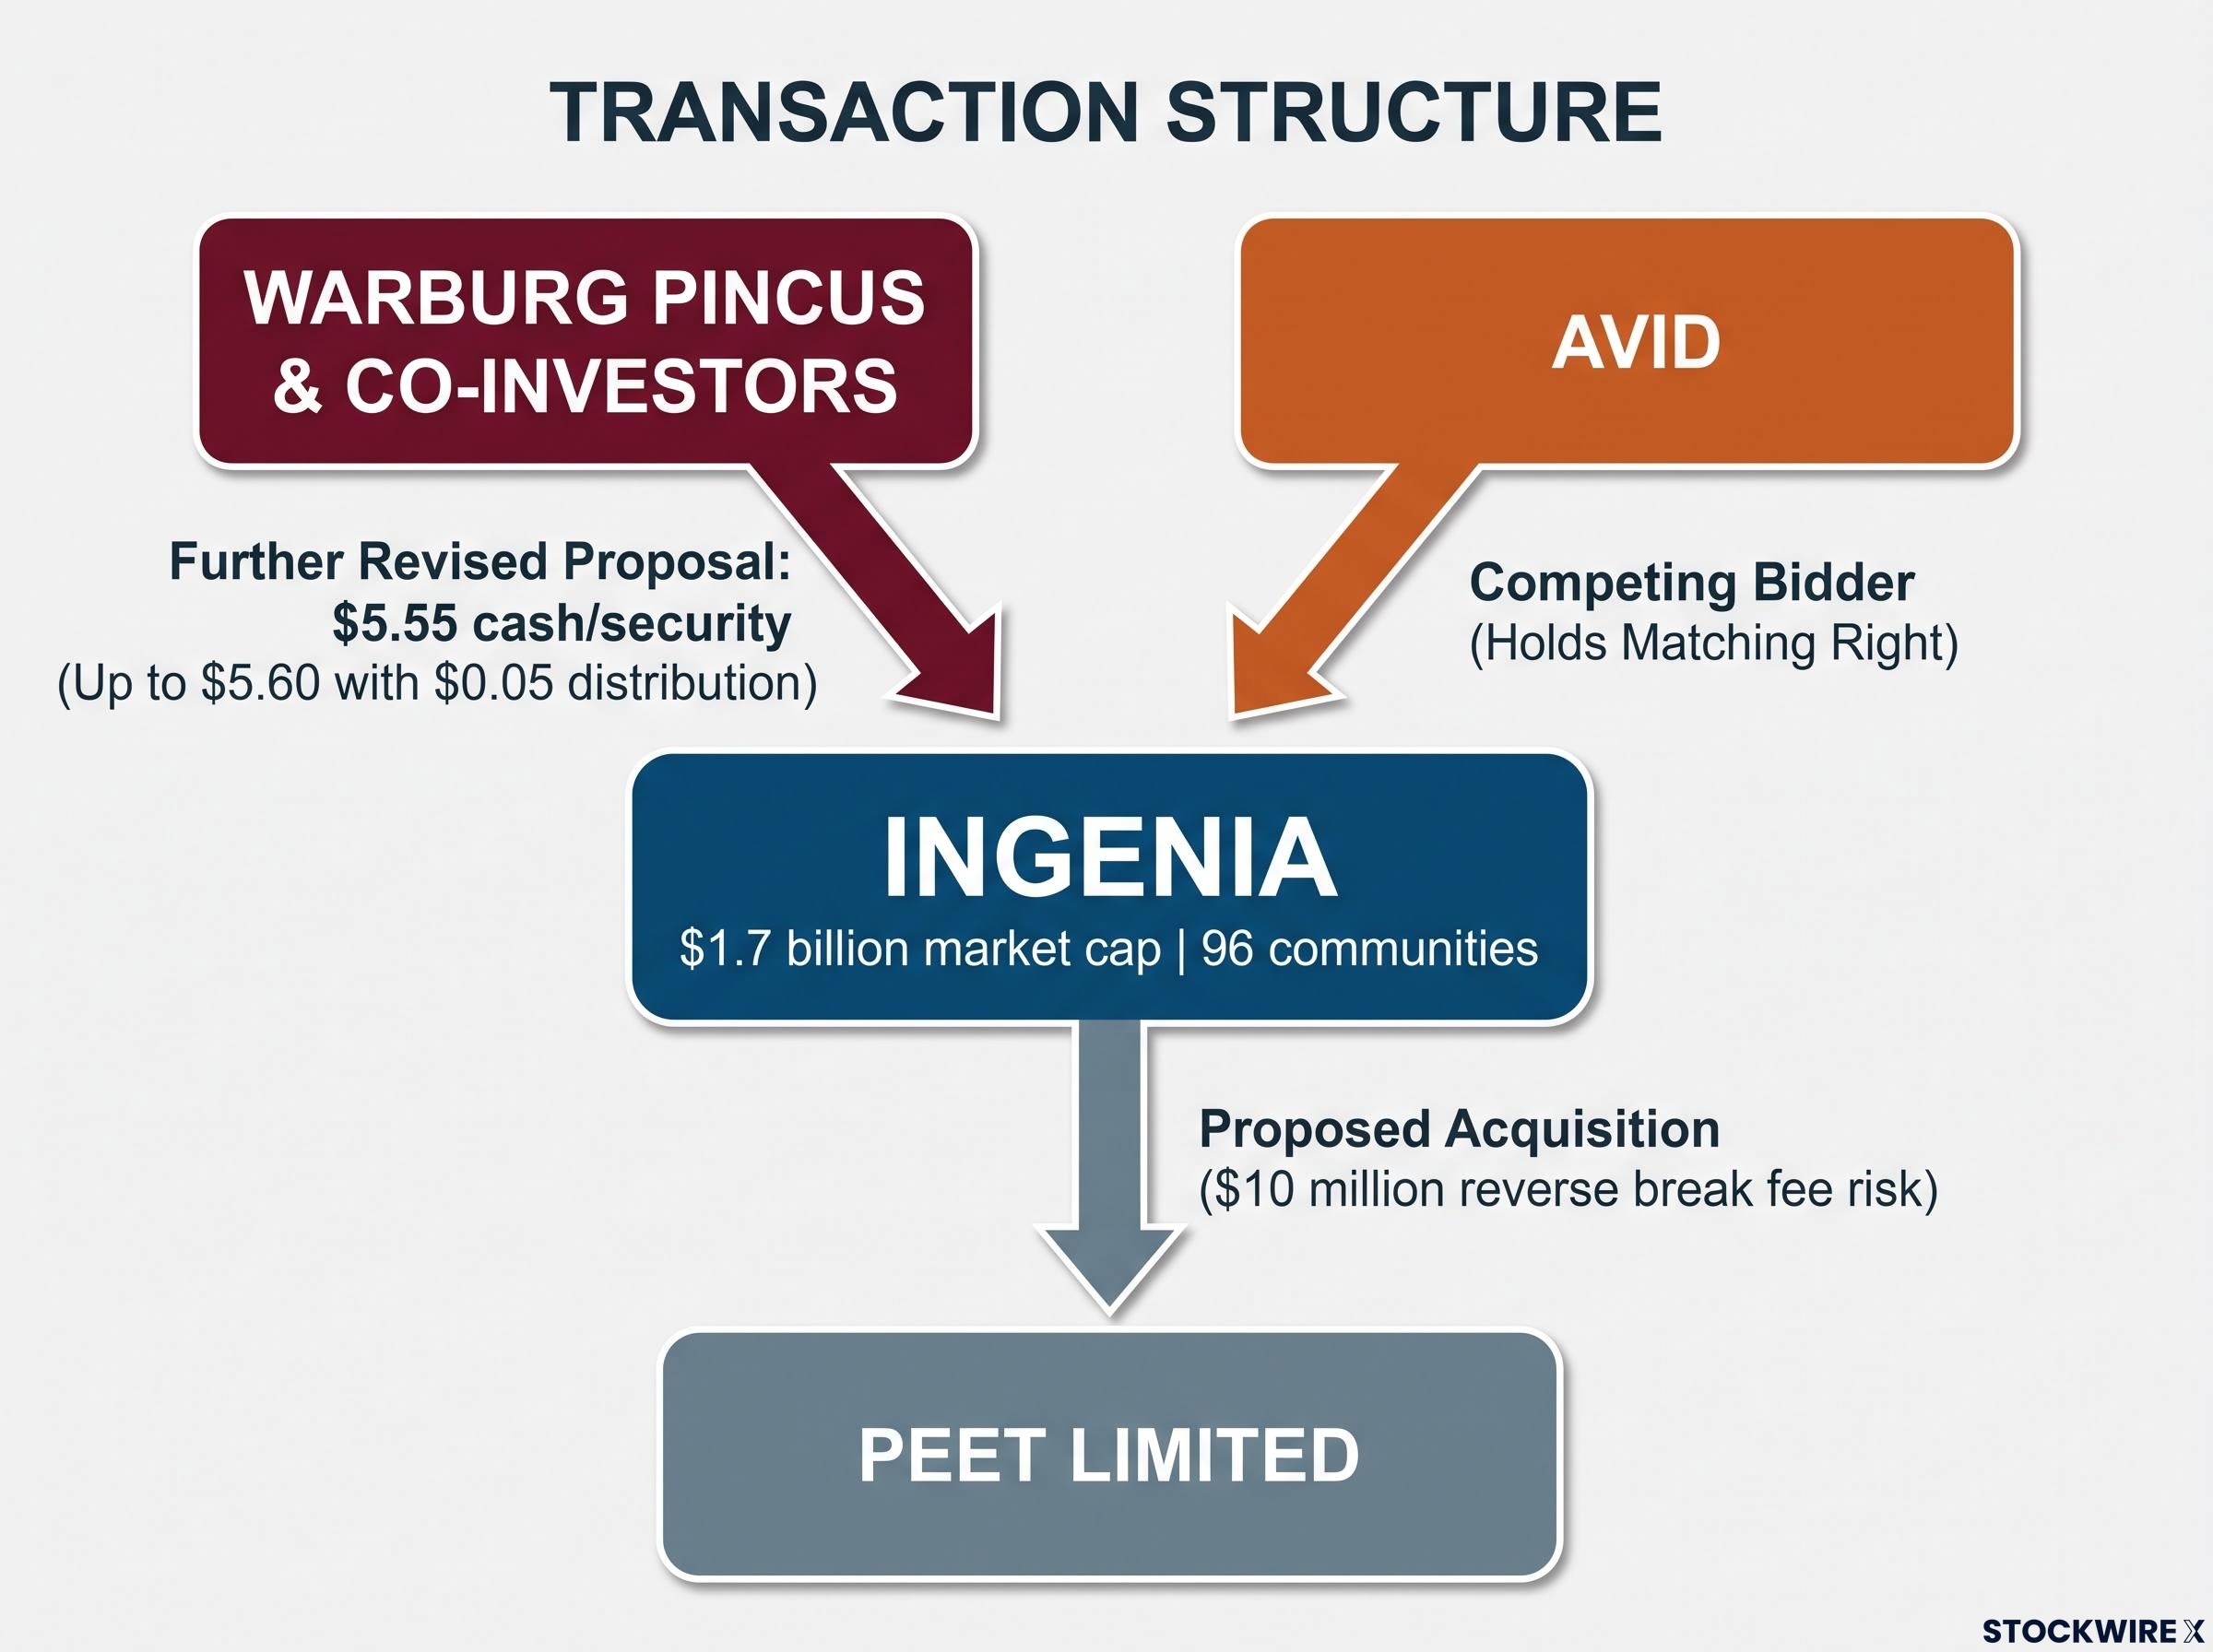
Ingenia Communities Group (ASX:INA) has received a further revised, non-binding indicative proposal dated 6 November 2026 from Warburg Pincus LLC and/or its affiliates, together with co-investors Discovery Parks Holdings Pty Ltd and LDR Capital Pty Ltd (Proposed Co-Investors). The Warburg Pincus proposal is priced at $5.55 cash per stapled security to acquire 100% of Ingenia’s stapled securities.
The structure is an inter-conditional scheme of arrangement and trust schemes. Warburg Pincus proposes that the price will not be reduced by a Permitted Distribution of up to $0.05 cash per stapled security for the half year ending 31 December 2026, so securityholders would receive a total of up to $5.60 cash per stapled security.
The price is a $0.10 per stapled security increase on the Revised AVID Proposal, announced on 2 November 2026. A contested process of this kind puts competing bidders in direct price comparison, which is relevant to securityholders weighing outcomes.
How the bidding contest reached this point
The announcement sets out the sequence of events leading to the Further Revised WP Proposal:
- AVID Property Group Holdings Pty Ltd (AVID) made a revised proposal by exercising its matching right under the AVID Process Deed, announced on 2 November 2026.
- Warburg Pincus submitted an amended proposal, received on 3 November 2026.
- The Ingenia Board determined on 4 November 2026 that the amended proposal was not, and could not reasonably be considered to become, a ‘Superior Proposal’ under the AVID Process Deed.
- Warburg Pincus lodged the Further Revised WP Proposal on 6 November 2026.
When big ASX news breaks, our subscribers know first
Conditions attached to the Further Revised WP Proposal
The Further Revised WP Proposal is subject to a set of new conditions, summarised below.
| Condition | What it requires | Timing |
|---|---|---|
| WP Process Deed | Ingenia enters a process deed with Warburg Pincus on previously negotiated terms, with an additional exception letting a competing bidder retain due diligence access for 4 days after a matching proposal is made, and an extended exclusivity end date | Exclusivity end date of 14 December 2026 |
| Board confirmation | The Ingenia Board promptly considers the proposal and confirms in writing the application of the fiduciary out and that it is a ‘Superior Proposal’ for the purposes of the AVID Process Deed | Promptly |
| Due diligence and matching right notice | Ingenia gives Warburg Pincus and the Proposed Co-Investors immediate due diligence access, gives AVID a matching right notice and takes all steps required to commence the matching right process | By no later than the end of 6 November 2026 |
| Exclusive due diligence access | Warburg Pincus is granted exclusive due diligence access under the WP Process Deed | By no later than Tuesday, 10 November 2026 |
| AVID Process Deed termination | Subject to AVID’s matching right, Ingenia terminates the AVID Process Deed, ceases discussions with AVID and enters the WP Process Deed | n/a |
The conditions of Warburg Pincus’ earlier proposals also continue to apply:
- Satisfactory completion of due diligence
- Warburg Pincus securing binding debt finance commitments and final investment committee approval
- Negotiation of a binding scheme implementation deed on customary terms
- FIRB and ACCC approval
- Ingenia terminating the scheme implementation deed with Peet Limited (Peet) dated 26 August 2026 (Peet SID)
Where the Peet transaction stands
The Ingenia Board has not determined that the Further Revised WP Proposal constitutes a ‘Bidder Superior Proposal’ under the Peet SID. Accordingly, it is not currently a ‘Bidder Superior Proposal’ for the purposes of the Peet SID, and the Board has not indicated that it intends to recommend it to securityholders.
Ingenia continues to comply with its obligations under the Peet SID and to work with Peet towards implementation of Ingenia’s proposed acquisition of Peet. Under the Peet SID, Ingenia is entitled to terminate before 8.00am on the Second Court Date if the Board determines a Bidder Competing Proposal constitutes a Bidder Superior Proposal, subject to the conditions set out in that deed. In that event, Ingenia would be liable to pay a $10 million reverse break fee to Peet.
What a matching right and fiduciary out mean for securityholders
A matching right gives an existing bidder the chance to respond to a rival offer before the target company switches sides. Here, AVID holds that right under the AVID Process Deed, and Ingenia is required to give AVID a matching right notice under the Warburg Pincus conditions.
A fiduciary out lets a board step away from a deal commitment where continuing would breach its duties to securityholders. The Board is meeting to consider whether the fiduciary out in the AVID Process Deed applies, which sits alongside the matching right in shaping how competing bids are weighed.
Key terms at a glance:
- Process Deed: an agreement setting out how a company deals with a bidder, including access and exclusivity arrangements.
- Matching right: the right of an existing bidder to respond to a rival proposal.
- Fiduciary out: a provision allowing a board to act differently where required by its duties.
- Reverse break fee: a fee payable by the target, here a $10 million fee Ingenia would owe Peet if the Peet SID were terminated in the circumstances described.
Readers interested in the deal at the centre of this reverse break fee can use our full explainer on Ingenia’s Peet acquisition, which sets out the cash and scrip terms, the Flagstone joint venture and the land lease conversion pipeline behind the strategic case.
What happens next for Ingenia securityholders
The announcement states the following upcoming steps:
- The Ingenia Board meets on 6 November 2026 (“later today”) to consider the Further Revised WP Proposal, including whether the fiduciary out in the AVID Process Deed applies and whether to commence the matching right process.
- Ingenia is to give AVID a matching right notice by the end of 6 November 2026, a Warburg Pincus condition.
- Warburg Pincus is to be granted exclusive due diligence access by no later than Tuesday, 10 November 2026, also a condition.
- The exclusivity end date under the proposed WP Process Deed is 14 December 2026.
There is no certainty that the Further Revised WP Proposal or the Revised AVID Proposal will result in a formal binding offer for Ingenia, or that any transaction will eventuate. Securityholders do not need to take any action, and Ingenia will keep them informed in accordance with its continuous disclosure obligations.
Ingenia is included in the S&P/ASX 200 and has a market capitalisation of $1.7 billion, with 96 communities and development sites across its Ingenia Lifestyle, Ingenia Gardens, Ingenia Holidays and Ingenia Rental businesses.
Get Real Estate News Before the Market Moves
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to be first to know when the next market-moving property story breaks.