
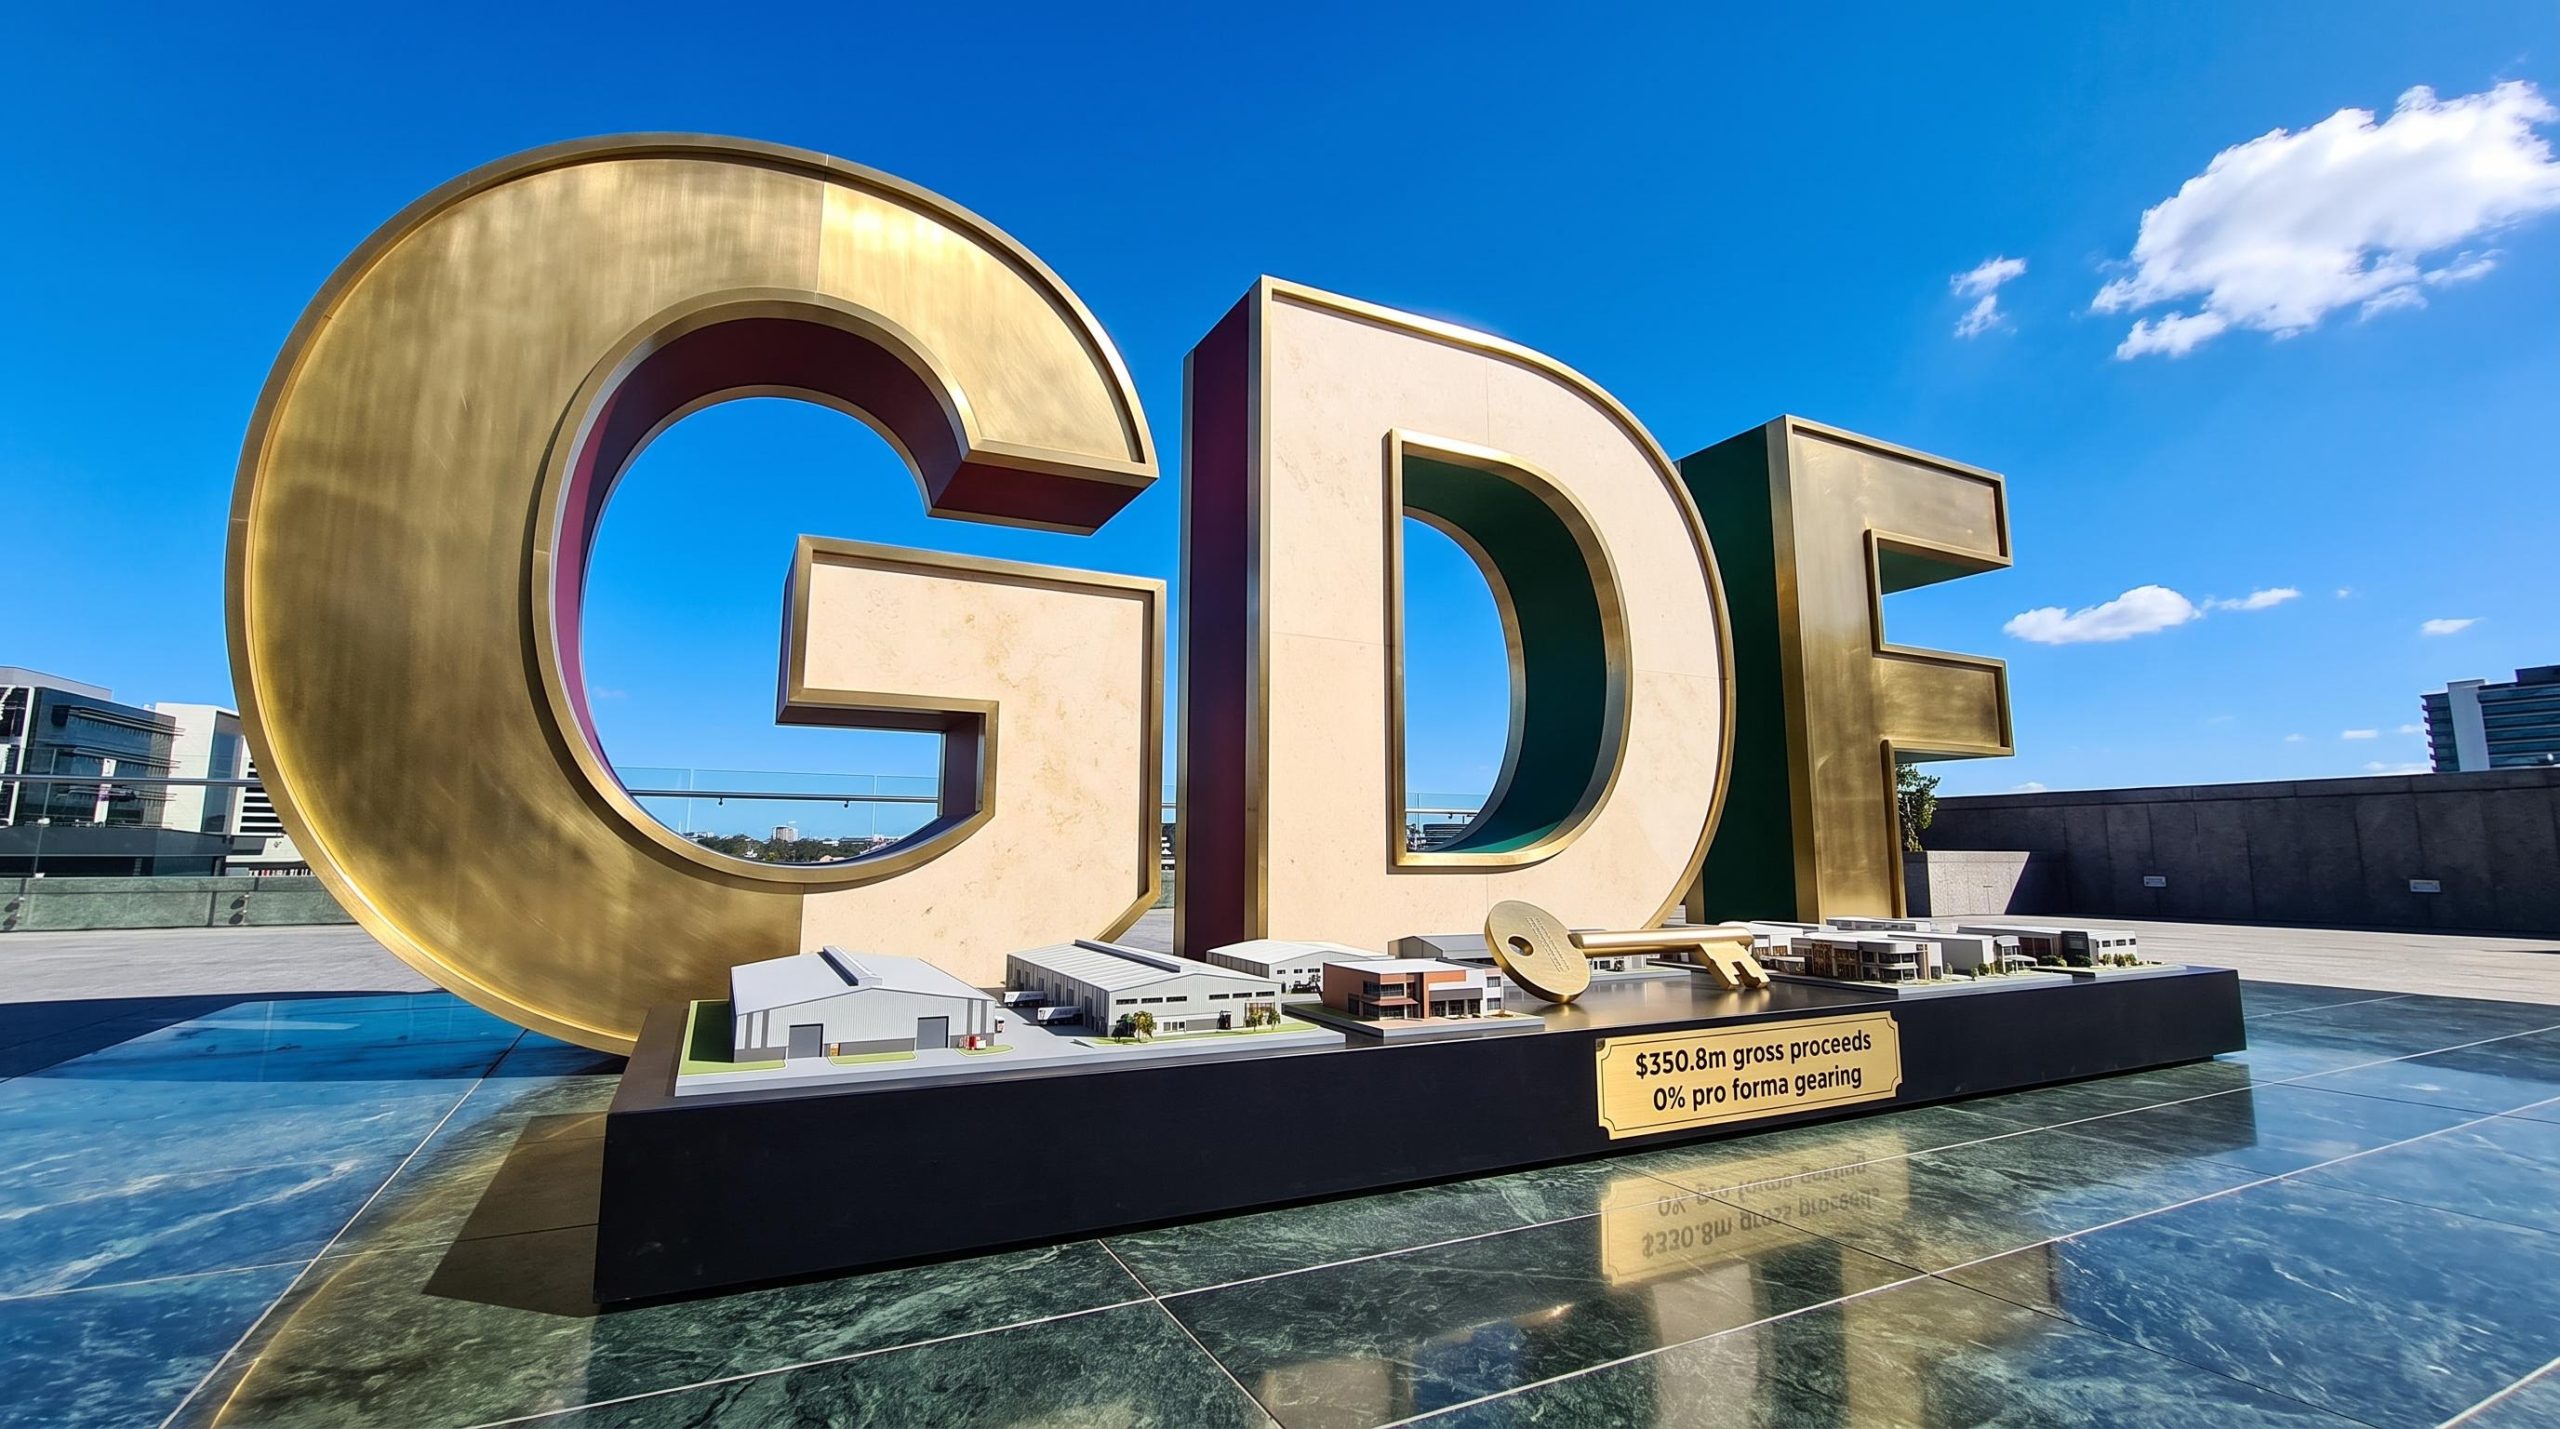
Garda sells seven properties to Charter Hall fund for $300.0 million
Garda Property Group has executed contracts to sell its seven remaining investment properties to a Charter Hall managed fund (Charter Hall fund) for $300.0 million. Together with the previously announced Heathwood and Pinkenba sales of $50.8 million, the transactions cover all nine of its investment properties.
Gross sale proceeds total $350.8 million, with settlement of all nine properties expected between November 2026 and March 2027. The proceeds are expected to repay all existing debt and leave $176.6 million of cash to invest.
The sales follow closely the Pinkenba and Heathwood announcements on 28 and 29 September, respectively (together, the Transactions). One caveat applies to the Charter Hall fund contracts: the Morningside property is still subject to due diligence.
Matthew Madsen, Executive Chairman
“…These decisive Transactions monetise the value of our property portfolio, repay all Group debt and result in an ungeared balance-sheet holding substantial cash for future investment.”
Key figures from the announcement:
- $350.8M gross proceeds across all nine investment properties
- 0% anticipated pro forma gearing
- $176.6M of cash to invest
When big ASX news breaks, our subscribers know first
Sale terms and settlement timetable
Property-by-property breakdown
The table below reproduces the purchasers, gross proceeds, carrying values and expected settlement dates as presented in the announcement. The two Acacia Ridge properties show a combined gross proceeds figure of $68.5m.
| Property | Purchaser | Gross proceeds $m | Carrying value $m | Expected settlement |
|---|---|---|---|---|
| Heathwood | The Landrich Trust | 17.5 | 16.4 | 20 Nov 2026 |
| Acacia Ridge – 38 Peterkin | Charter Hall fund | 68.5 | 43.4 | 20 Nov 2026 |
| Acacia Ridge – 69 Peterkin | Charter Hall fund | 24.1 | 20 Nov 2026 | |
| Berrinba | Charter Hall fund | 17.1 | 17.5 | 20 Nov 2026 |
| Richlands | Charter Hall fund | 37.9 | 38.8 | 20 Nov 2026 |
| Wacol – Volvo | Charter Hall fund | 51.8 | 52.0 | 20 Nov 2026 |
| Wacol – Pinnacle West | Charter Hall fund | 44.0 | 48.5 | 20 Nov 2026 |
| Pinkenba | 2MB Co Pty Ltd | 33.3 | 34.0 | 22 Jan 2027 |
| Morningside (subject to due diligence) | Charter Hall fund | 80.7 | 81.1 | ~Mar 2027 |
| Total | 350.8 | 355.9 |
The Heathwood buyer is The Landrich Trust, and the Pinkenba buyer is 2MB Co Pty Ltd. Both sales were announced before the Charter Hall fund contracts.
Settlement status
Six Charter Hall fund properties settle on 20 November 2026, alongside Heathwood. Pinkenba is expected to settle on 22 January 2027.
Morningside, at $80.7m, is the only property that remains subject to due diligence. Its settlement is expected around March 2027.
Garda describes the portfolio sale as a nominal 1.4% discount to underlying carrying value and net tangible assets (NTA). Total gross proceeds of $350.8m compare with a total carrying value of $355.9m.
June’s independent valuations lifted the Brisbane industrial portfolio by $8.253 million, or 2.5%, with Morningside and Acacia Ridge the strongest contributors on rental growth.
Debt-free balance sheet and the pivot to lending
Use of proceeds
Based on the settlement profile and estimated transaction adjustments, Garda anticipates the following outcomes:
- Repayment in full of the syndicated debt facility, currently drawn to $185.3 million.
- Pro forma gearing of 0%.
- Approximately $176.6 million of surplus cash.
- Investable capital of approximately $321.0 million, comprising $144.4 million of existing loan receivable assets and $176.6 million of new lending capacity.
- NTA per security of $1.56, representing a 52% premium to the ASX close price of $1.025 per security on 20 October 2026.
The announcement also states that Garda’s securities are trading at a 38% discount to NTA per security. The announcement presents this figure alongside the 52% premium without further reconciliation, so each is reported here as the source states it.
The surplus investable capital is likely to be allocated to lending activities for the foreseeable future, in line with previously announced investment priorities.
Garda’s FY26 results showed lending already contributing 49% of group revenue, with the loan book nearly doubling to $134.1 million across 18 facilities.
Why a REIT shifts from property ownership to real estate lending
A real estate investment trust (REIT) earns income from property it owns or from loans secured against property. The choice between the two depends partly on how property values and funding costs are moving.
A capitalisation rate is the income a property earns relative to its value. Garda says the spreads between industrial property capitalisation rates, government bond yields and funding costs have narrowed. Narrower spreads leave less cushion if property values fall, which increases asset valuation risks, particularly if strong market rental growth is not achieved.
By contrast, Garda says the returns and security profile available from prudent lending activities remain attractive. This is the reasoning the company gives for favouring lending at this point.
Strategic attractions
Garda lists four further attractions of the strategy:
- Balance sheet: debt repayment coupled with surplus cash proceeds provides a strong capital deployment platform.
- Lending-led deployment: real estate lending is expected to become the primary destination for available capital.
- Disciplined optionality: Garda will retain the capability to own or develop property where prospective returns exceed applicable risk and cost-of-capital hurdles.
- Per-security focus: continued focus on long term value per security while seeking to generate increasing distributions.
Mr Madsen set out the allocation approach in the announcement:
Matthew Madsen, Executive Chairman
“Garda is an allocator of capital into real estate, unrestrained by financial characteristics (ownership or lending)…”
He added that real estate lending is expected to be the primary deployment focus in the medium term. He also said “…we fully anticipate future ownership of real property at a time where the prospective returns are compelling for the risk assumed and cost of capital.”
FY27 guidance upgraded: distributions up 39%
Garda has upgraded its FY27 funds from operations (FFO) guidance by 19%, from 10.5 cents to 12.5 cents per security. Distribution guidance rises by 39%, from 9.0 cents to 12.5 cents per security.
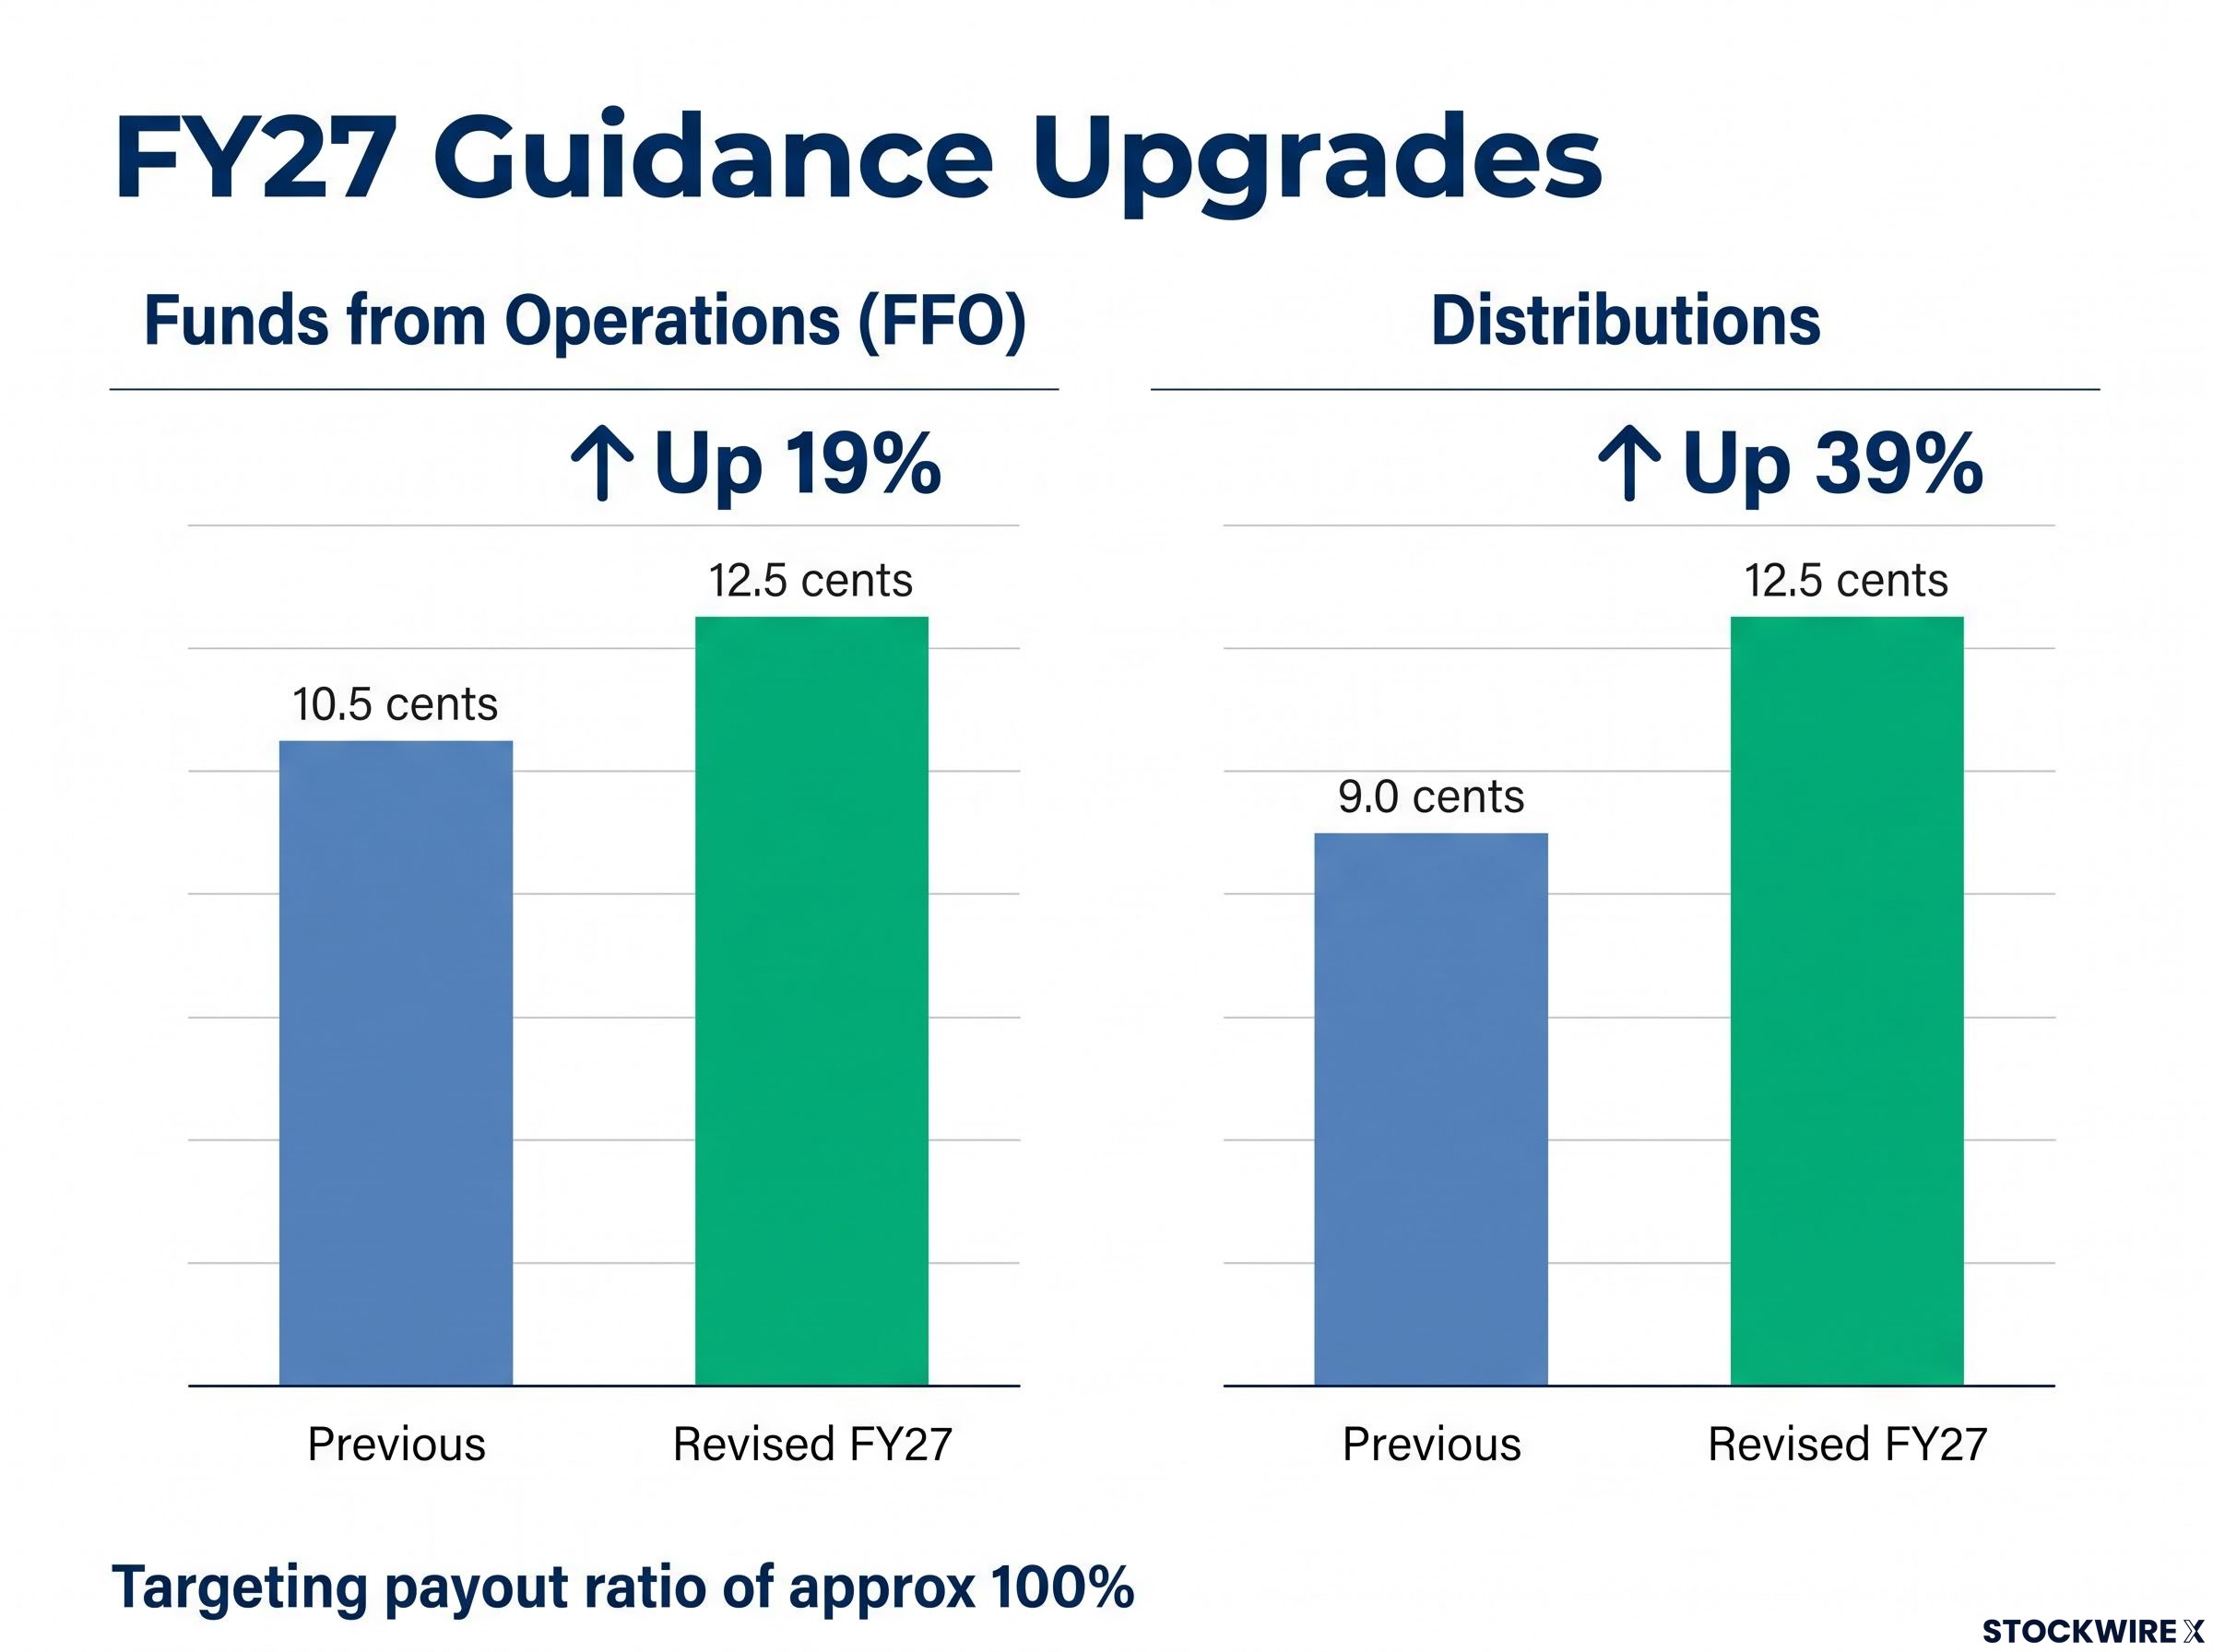
Distributions will no longer include tax-advantaged income from property tax depreciation benefits. Garda intends to distribute substantially all of its FFO, targeting a payout ratio of approximately 100% to minimise the taxation of retained earnings within the trust.
Guidance remains subject to the assumptions and qualifications previously disclosed by Garda. It also depends on the Transactions completing broadly in line with the anticipated timetable.
Regulatory position and financial effect
The Transactions will together constitute a significant change to the scale of Garda’s activities for the purpose of ASX Listing Rule 11.1. Garda has received in-principle advice from the ASX that, based on the information provided, the Transactions do not require securityholder approval under ASX Listing Rules 11.1.2 or 11.2.
The ASX will also not exercise its discretion under Listing Rule 11.1.3 to require Garda to meet the requirements in Chapters 1 and 2 of the Listing Rules as if it were applying for admission to the official list.
Appendix A sets out the expected effect of the Transactions against Garda’s FY26 audited figures:
- Total consolidated assets: down 32.9%, from $500.6m to $336.0m
- Total equity interests: down 1.0%
- Annual revenue: down 57.3%
- EBITDA: down 41.0%
- Annual profit before tax: down 67.5%
- Total securities on issue: unchanged at 217,573,022
The reductions in revenue, EBITDA and profit before tax reflect the removal of rental income from the sold portfolio. Garda’s guidance, as described above, anticipates distributions rising nonetheless, with lending expected to become the primary destination for available capital.
Don’t Miss the Next Real Estate Move Before the Market Does
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to receive real-time alerts the moment market-moving news breaks.