

A tough year, a clear recovery — SBZ sets the record straight on FY26
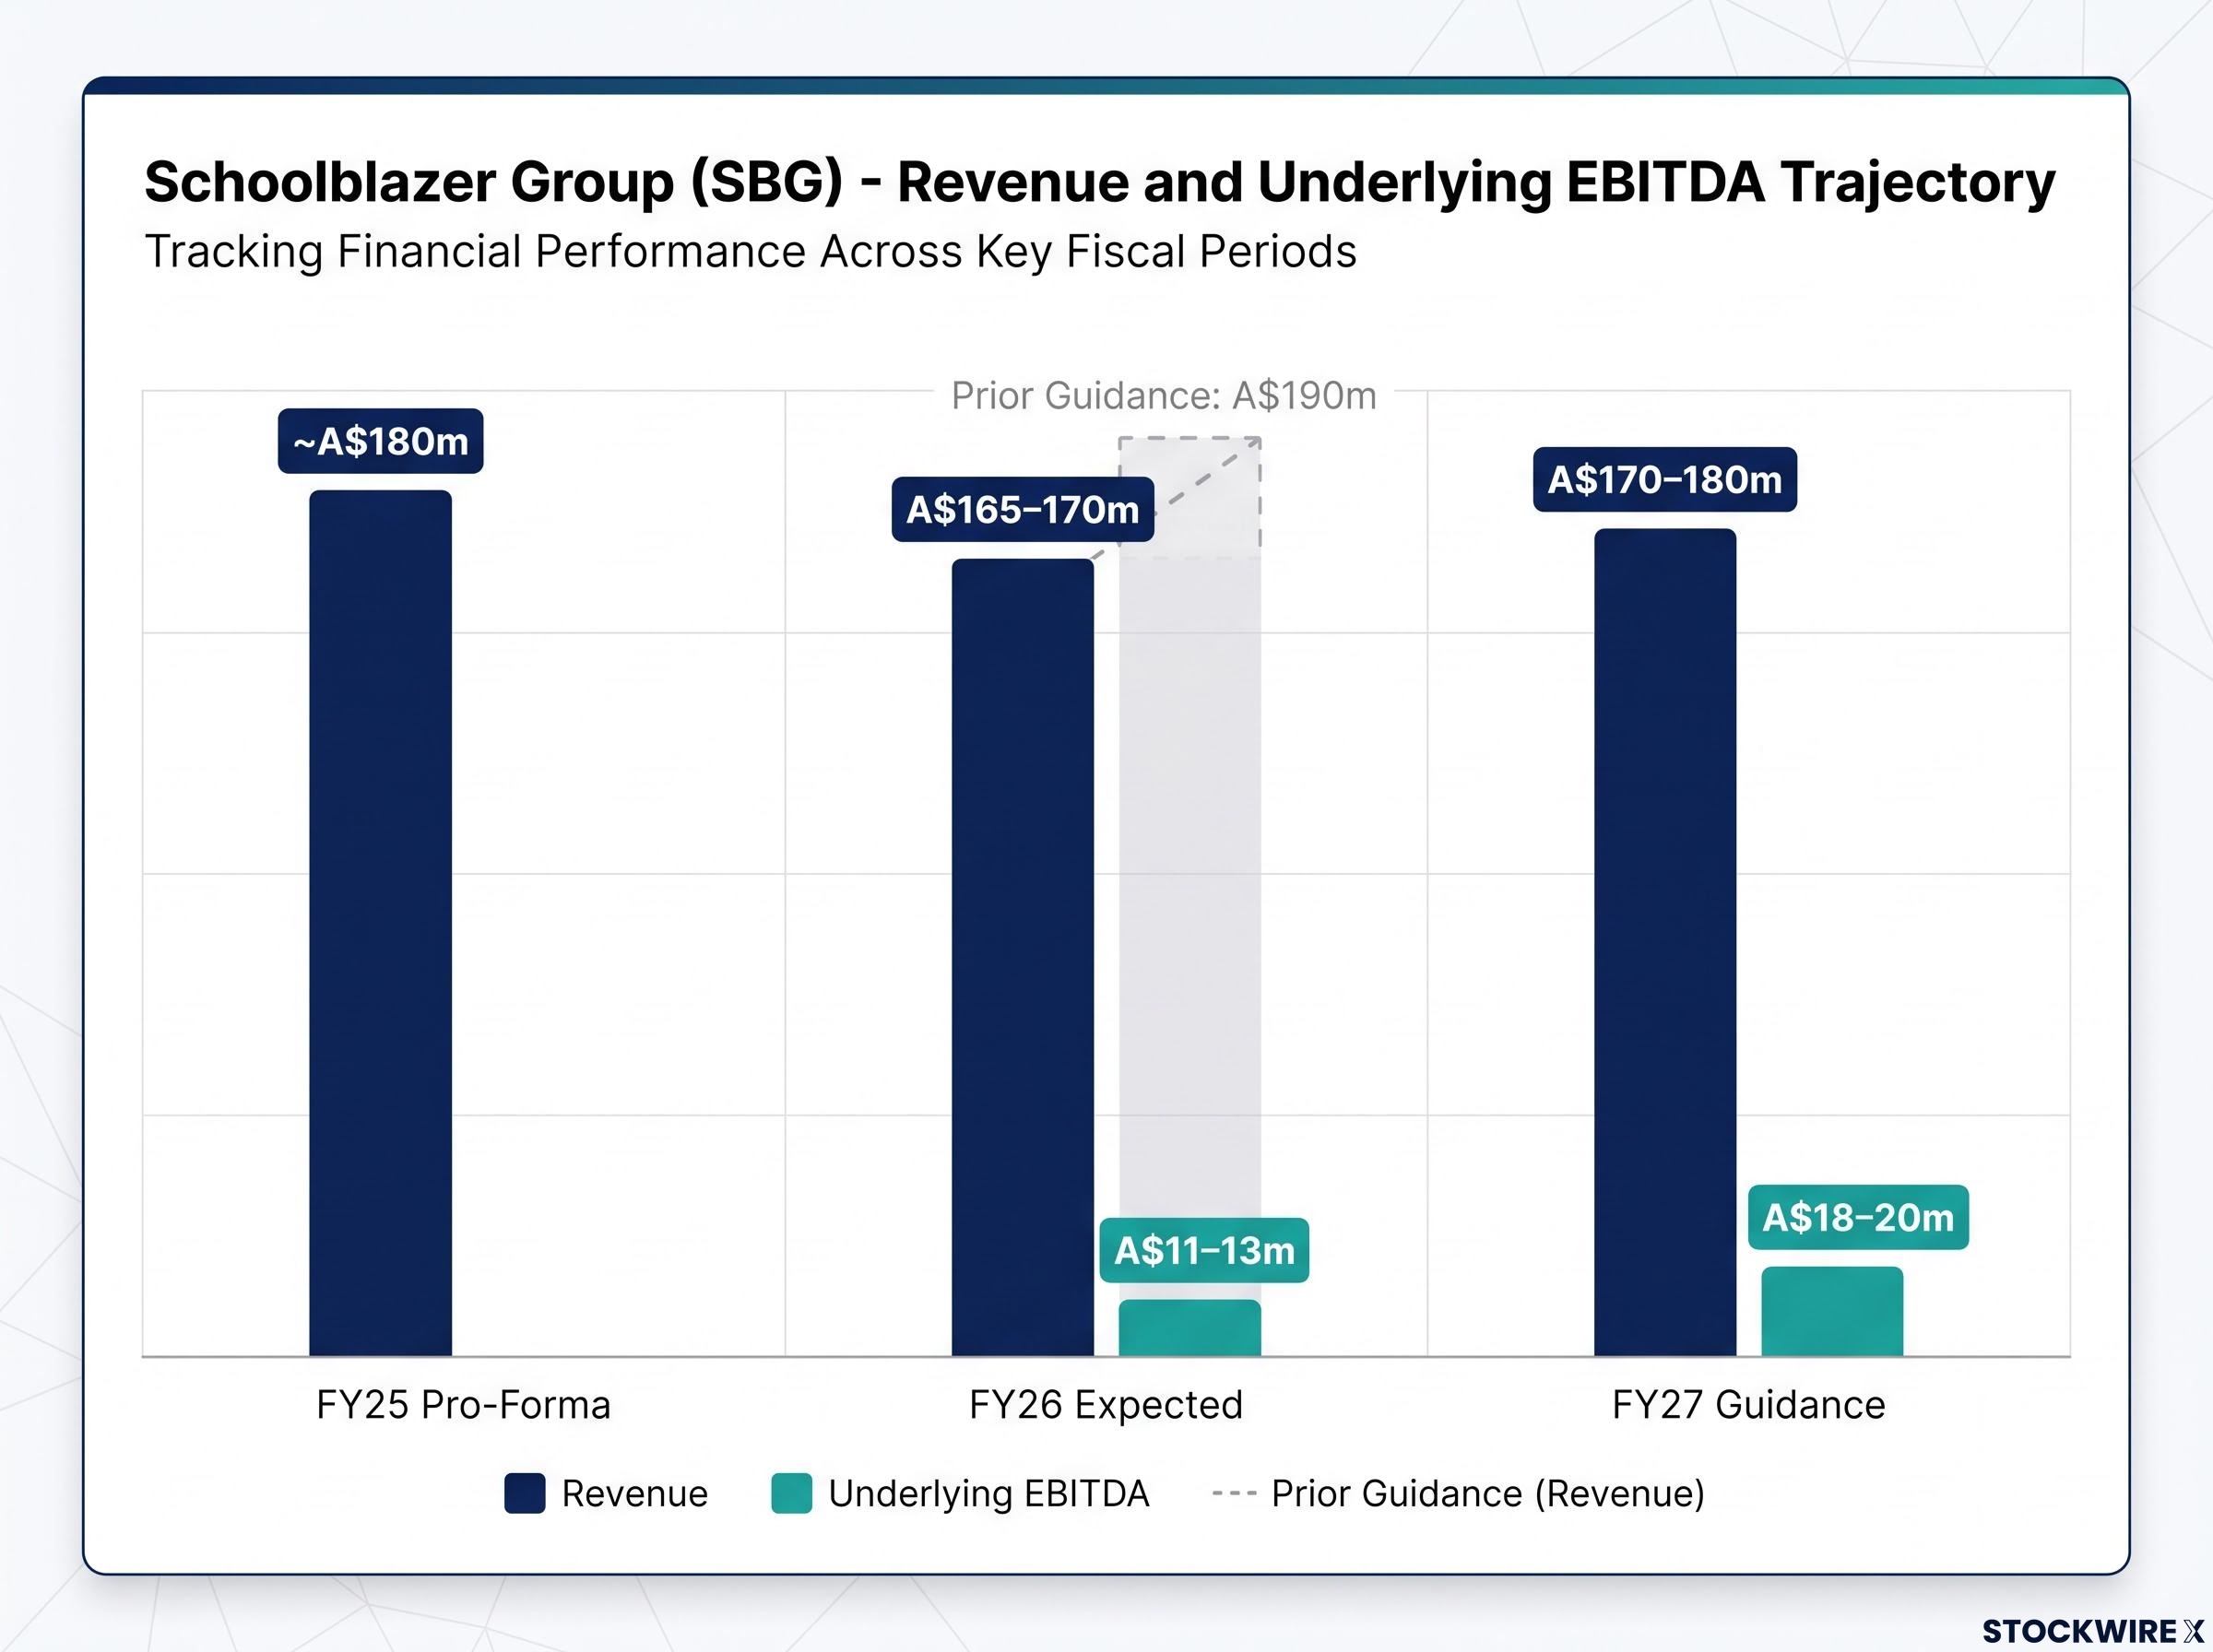
Schoolblazer Limited (ASX: SBZ) has released a preliminary FY26 trading update for its wholly owned operating business, Schoolblazer Group (SBG), ahead of full audited results expected in late November 2026. Revenue is expected to land at A$165–170m on a constant-currency basis, falling short of prior guidance of A$190m and the pro-forma FY25 result of approximately A$180m.
Underlying EBITDA for FY26 is expected in the range of A$11–13m on a constant-currency basis. The company attributed the earnings impact to a revenue shortfall concentrated in Q4, the critical back-to-school period, which amplified the effect on an otherwise fixed cost base. Gross margins, however, remained strong throughout the year.
All FY26 figures are preliminary and unaudited, with numbers reported at FY25 foreign exchange rates. Results remain subject to completion of September trading, year-end close procedures, and audit review.
When big ASX news breaks, our subscribers know first
What went wrong in FY26 — and why it was largely external
SBG identified five distinct headwinds that drove the weaker-than-expected result, with the bulk of the damage concentrated in wholesale channels, which were down 13% year-to-date:
- UK independent sector: VAT imposed on school fees had a more pronounced impact than expected on enrolments
- UK public sector: Regulatory changes limiting the number of branded uniforms led to weak wholesale demand from other retailers, although SBG’s own direct retail business performed strongly
- Middle East disruption: Ongoing regional conflict caused delays in pupils returning to school
- Regulatory change in China: Simplified school-uniform rules reduced branded product demand
- Operational factors: The Australian ERP go-live temporarily affected fulfilment during the second half; this has since been resolved and operational benefits are emerging
Revenue from direct-to-consumer channels held up by comparison, rising 1% year-to-date, though this was below the faster growth rate the company had anticipated.
The FY26 Underlying EBITDA figure excludes approximately A$2.5m in non-recurring costs, largely relating to the Australian ERP implementation and banking refinance transaction costs. It also includes approximately A$1.3m in establishment costs for the Schoolblazer Australia/NZ business, ahead of five new schools commencing in FY27.
Understanding Schoolblazer’s direct-to-consumer model — and why it matters for recovery
SBG operates through two distinct sales channels, and the balance between them is central to the company’s margin recovery story.
In its direct-to-consumer model, SBG sells and delivers uniforms directly to families via its own e-commerce platform under school contracts. This channel carries higher margins and offers greater revenue stability, as orders flow through SBG’s own systems rather than intermediary retailers.
In its wholesale model, SBG supplies other retailers who then sell uniforms to families. This channel generates lower margins and is more exposed to retailer decisions and regulatory changes, as clearly demonstrated by the UK public sector disruption in FY26.
The ongoing industry shift away from wholesale toward contracted direct retail is structurally positive for SBG’s margin profile. Tim James’ appointment as Acting Managing Director is directly linked to accelerating this transition, with the announcement noting that recent industry disruption is hastening the anticipated market shift.
FY27 guidance and the path back to earnings growth
SBG has provided FY27 guidance of A$170–180m revenue and A$18–20m Underlying EBITDA. Importantly, the company stated that improvement on FY26 is not reliant on material revenue recovery, with three identifiable pillars underpinning the uplift:
- Accelerated cost savings: Approximately A$4m of FY27 integration and efficiency benefits (approximately A$5m annualised), with a meaningful portion already confirmed or in execution
- Contract wins and pipeline: 29 contracts won in FY26, with 11 already secured for FY27, supported by a strong pipeline of new school partnerships
- Higher-margin channel mix: Growth weighted toward contracted direct-to-consumer channels, which carry higher margins and greater revenue stability than legacy wholesale
SBG’s previous FY27 EBITDA target of A$25m (at A$200m revenue) remains the target underlying profitability for the business at that revenue level. Delivery of this target is now anticipated for FY28, depending on FY27 achievements.
Tim James steps up as Acting Managing Director
Tim James, co-founder of Schoolblazer, SBZ Director, and major shareholder, has stepped into the role of Acting Managing Director. The announcement cited his extensive experience as vital in capitalising on the accelerating shift away from wholesale channels and driving the cost programme forward. No direct attributed quote from Tim James or Chairman Sandy Beard was included in the announcement.
Balance sheet and cash position
Despite the earnings miss, SBG’s balance sheet position improved materially through the second half. The group generated approximately A$20m in operating cash flow before interest between 31 March and 18 September 2026, driven by inventory efficiency. Net bank debt reduced by approximately A$10m over the same period.
As at 18 September 2026, SBG held approximately A$32m in cash, with A$28m in drawn trade finance facilities. Given the weaker-than-expected earnings result and rising interest rates, SBG expects to apply some of its cash balance to reduce its A$45m term debt and lower core leverage.
The A$45m term debt and seasonal trade finance facility now sitting on SBG’s balance sheet reflect the Westpac facility settlement completed in late June 2026, which discharged all legacy banking arrangements and ring-fenced the debt entirely within the Schoolblazer Group subsidiary.
Separately, Schoolblazer Limited at the parent level holds a A$16m loan maturing November 2027, against approximately A$15m of investment assets. The company is evaluating a range of capital management initiatives to strengthen the balance sheet, with indicated support from members of the Board and senior executives.
| Metric | FY25 Pro-Forma | FY26 Expected | FY27 Guidance | Notes |
|---|---|---|---|---|
| Revenue (constant-currency) | ~A$180m | A$165–170m | A$170–180m | FY26 vs prior guidance of A$190m |
| Underlying EBITDA | N/A | A$11–13m | A$18–20m | Constant-currency; FY26 preliminary and unaudited |
| Net bank debt reduction (H2 FY26) | N/A | ~A$10m reduction | N/A | Between 31 March and 18 September 2026 |
| Operating cash flow (H2 FY26) | N/A | ~A$20m | N/A | Before interest; driven by inventory efficiency |
Statutory results — what to expect in November
FY26 marks the first year of consolidated statutory accounting following the SBG business combination. The company expects to report a material statutory loss, subject to audit, driven by non-cash acquisition accounting adjustments and intangible impairments. This is a non-cash outcome and does not reflect underlying trading performance.
Reported results will also reflect a negative translation impact from the strengthening of the Australian dollar against the British pound and New Zealand dollar, again a non-cash reporting effect. Full-year FY26 audited results are expected to be released in late November 2026.
Don’t Miss the Next Consumer Sector Recovery Play
Big News Blast delivers breaking ASX news directly to your inbox within minutes of release, complete with in-depth analysis already done for you. Join 20,000+ active subscribers receiving FREE alerts the moment market-moving announcements hit. Click the “Free Alerts” button at StockWire X to stay ahead of the market.