
Macquarie Group 1H27 result: $A2,478m profit, up 50% on 1H26
In its investor presentation for the half year ended 30 September 2026 (1H27), dated 6 November 2026, Macquarie Group outlined profit attributable to MGL shareholders of $A2,478m. That was up 50% on 1H26 and down 22% on 2H26.
The 2H26 base is a demanding one, since the record FY26 second half was powered by a 93% surge on the first half, with all four operating groups posting double-digit growth.
Management detailed a 1H27 interim ordinary dividend of $A3.25 per share (35% franked), up from $A2.80 in 1H26.
| Metric | 1H27 | 1H26 | 2H26 | Change on 1H26 |
|---|---|---|---|---|
| Net operating income | $A9,568m | $A8,691m | $A10,786m | up 10% |
| Operating profit before income tax | $A3,251m | $A2,452m | $A4,277m | up 33% |
| Basic earnings per share | $A6.52 | $A4.37 | $A8.41 | up 49% |
| Annualised return on equity | 13.8% | 9.6% | 18.3% | up 44% |
Operating group net profit contribution
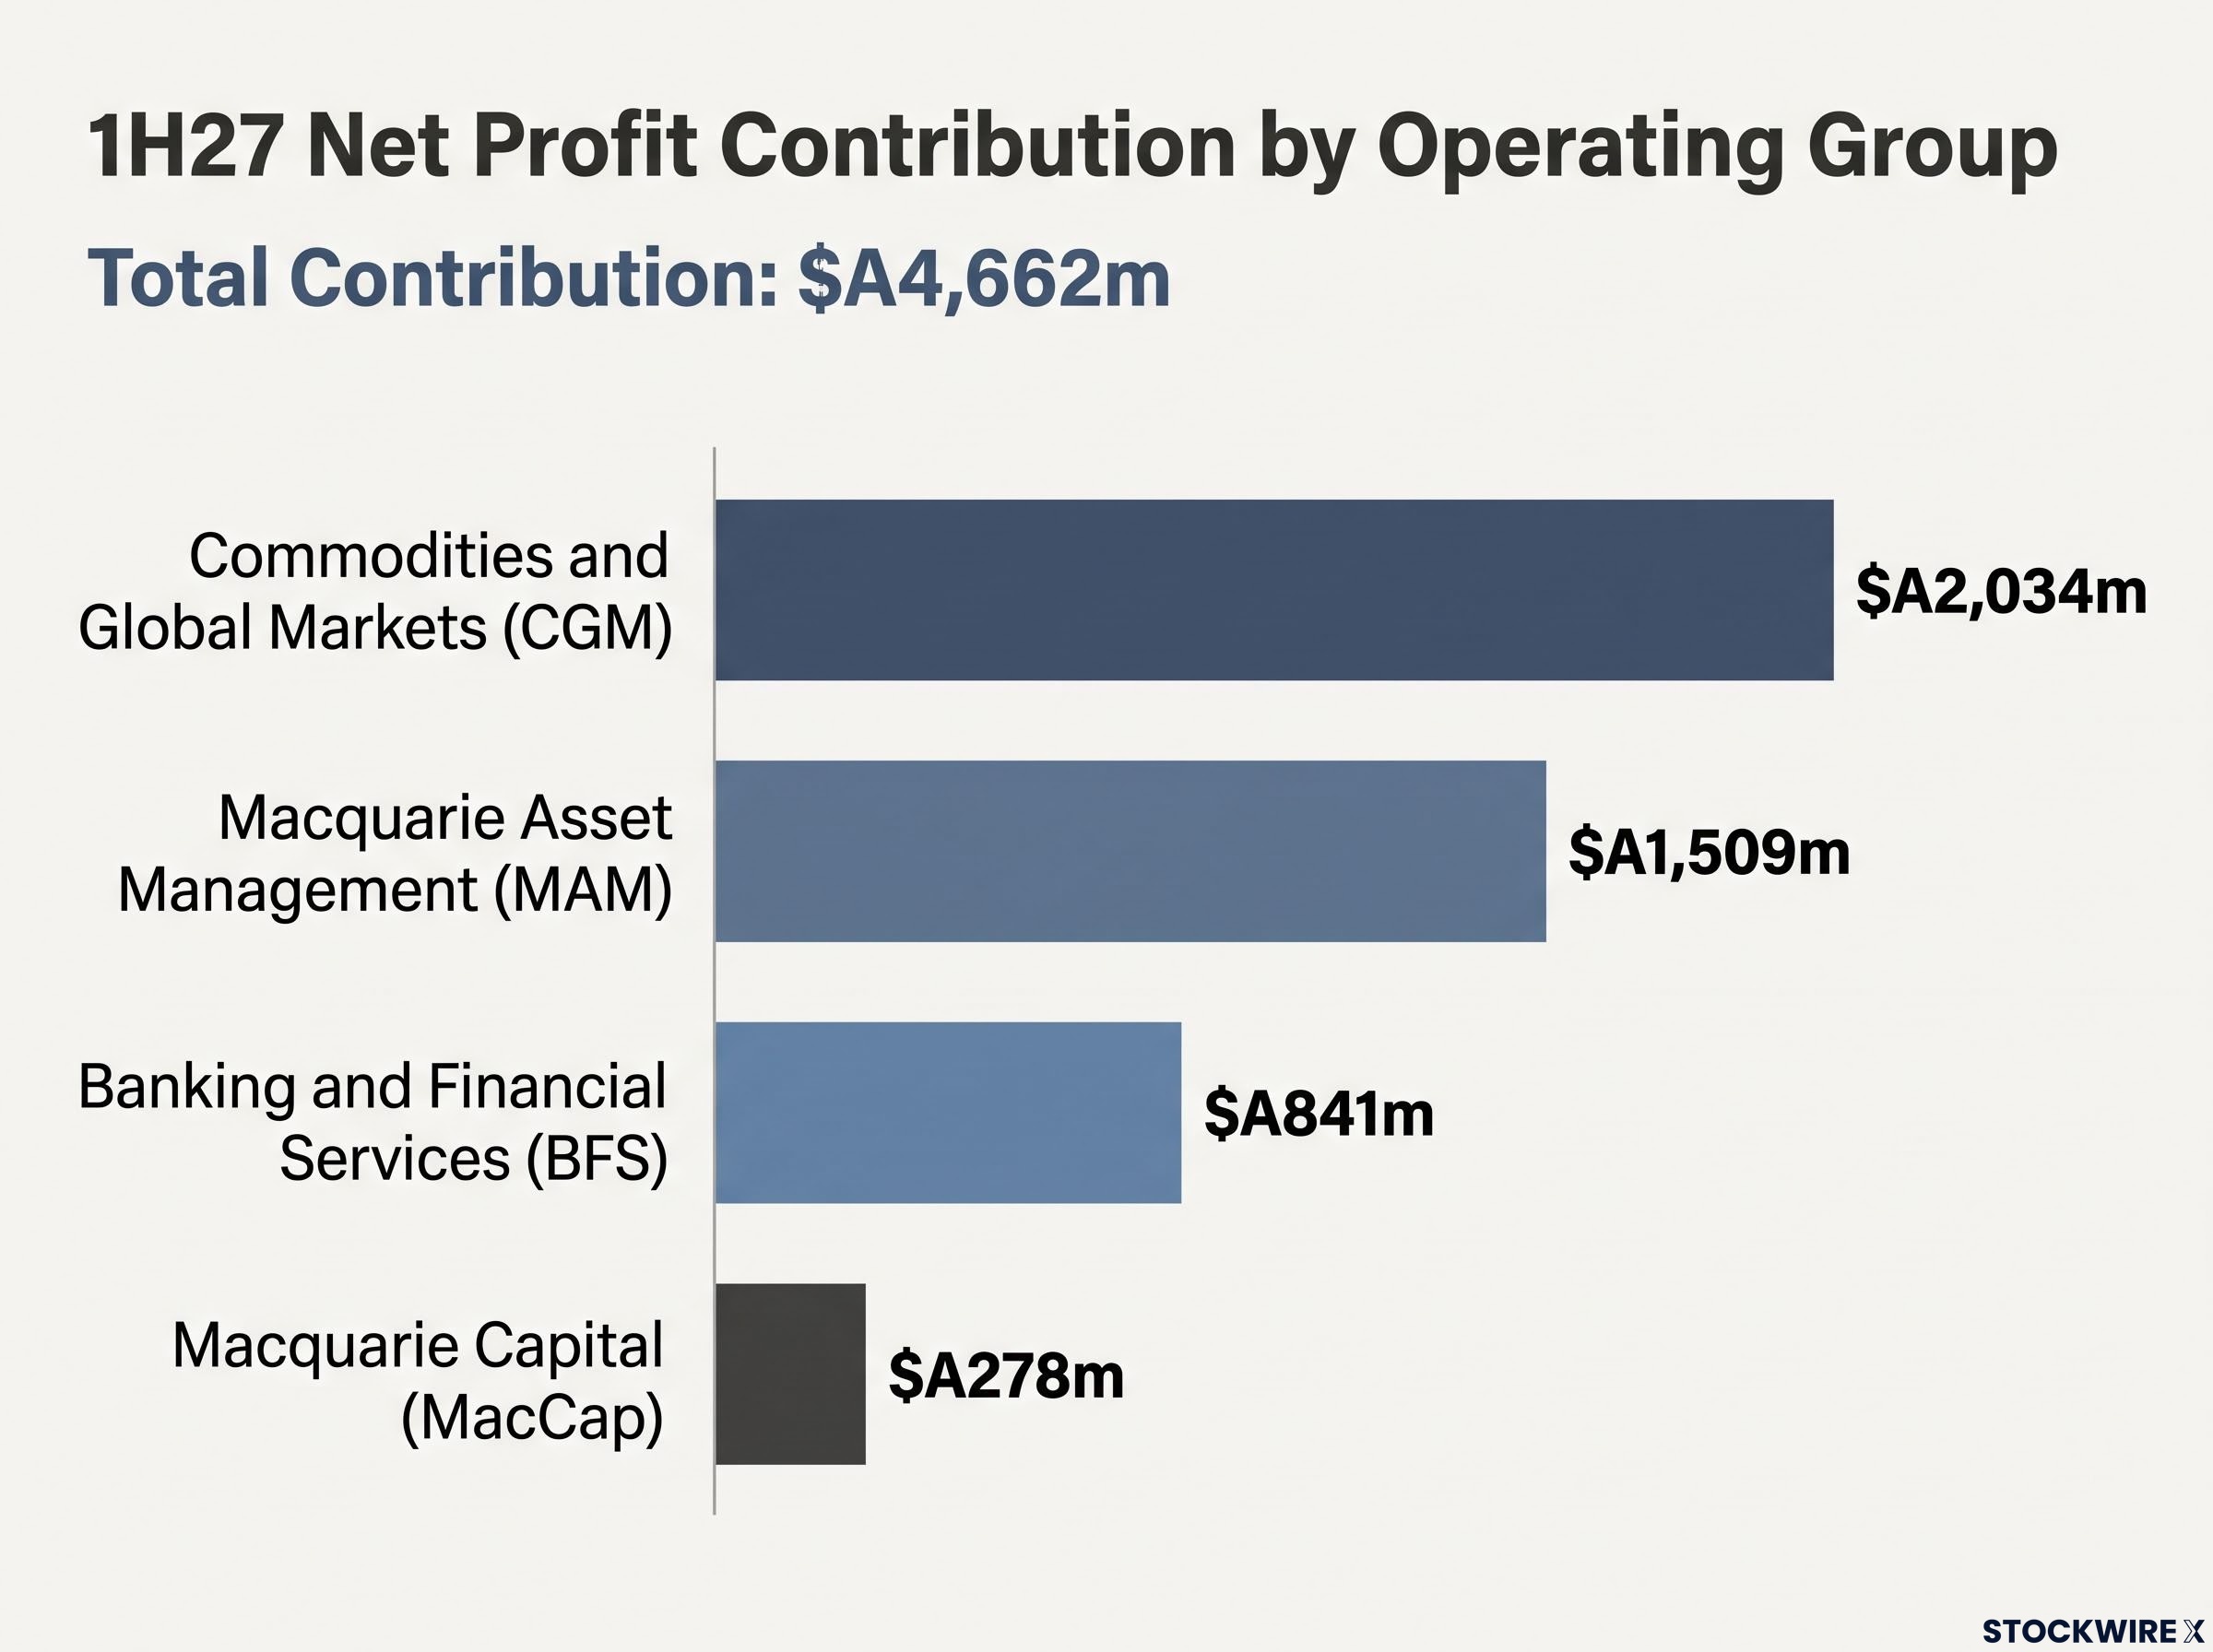
The operating groups contributed $A4,662m in 1H27, up 23% on 1H26.
Net operating income grew 10% while total operating expenses rose only 1%, to $A6,317m. The effective tax rate was 22.5%, compared with 31.4% in 1H26.
When big ASX news breaks, our subscribers know first
Operating groups: what drove the half
The presentation split the result between annuity-style and markets-facing businesses. Net profit contribution is management accounting profit before unallocated corporate items, profit share and income tax.
Annuity-style businesses
Macquarie Asset Management (MAM) delivered net profit contribution of $A1,509m, up 28% on 1H26. The increase was primarily driven by the gain on sale of Macquarie AirFinance, partially offset by lower performance fees due to timing of asset realisations.
MAM assets under management reached $A742.9b, up 3% on 31 March 2026. It raised $A15.3b of capital and invested $A17.6b across 11 new investments, with transactions including Qube Holdings and IHS Towers.
Banking and Financial Services (BFS) recorded net profit contribution of $A841m, up 6% on 1H26. The home loan portfolio (excluding offset accounts) stood at $A198.2b, BFS deposits at $A236.2b and funds on platform at $A161.3b.
Growth was partially offset by lower margins reflecting changes in portfolio mix and lending and deposit competition, higher credit provisions and higher expenses.
Margin pressure was already visible in the Q3 trading update, which showed BFS still gaining market share, with deposits up 6% and home loans up 7%.
Markets-facing businesses
Commodities and Global Markets (CGM) generated net profit contribution of $A2,034m, up 83% on 1H26 and down 35% on 2H26. Commodities income of $A1,800m was up 30% on 1H26.
Macquarie Capital (MacCap) contributed $A278m, down 61% on 1H26, reflecting lower investment-related income primarily driven by timing of asset realisations and lower M&A fees. Brokerage income rose 20% on the prior corresponding period, and the Private Credit portfolio reached $A28.0b.
The four net profit contributions in 1H27:
- MAM: $A1,509m
- BFS: $A841m
- CGM: $A2,034m
- MacCap: $A278m
Balance sheet, capital and dividend
Capital and liquidity
The APRA Basel III Level 2 CET1 ratio was 12.9%, while the Harmonised Basel III Level 2 CET1 ratio was 17.7%. The Group capital position above regulatory requirements was $A9.6b.
Average liquidity coverage ratio (LCR) for the September 2026 quarter was 187%. Total deposits were $A244.2b, up 10% from March 2026, and term funding raised since March 2026 totalled $A16.3b.
What a CET1 ratio and LCR tell investors
Common Equity Tier 1 (CET1) measures a bank’s core capital as a share of its risk-weighted assets. A higher ratio means a larger buffer to absorb losses.
The liquidity coverage ratio (LCR) compares a bank’s high-quality liquid assets with its expected net cash outflows over 30 days. Macquarie’s 12.9% APRA CET1 ratio sits above the APRA Basel III minimum of 9.0%, and its 187% average LCR sits above the 100% minimum.
Dividend and capital management
The 1H27 payout ratio was 50%, against a dividend policy of a 50-70% annual payout ratio.
Outlook and what happens next
Comparative period for the short-term outlook is FY26. In MAM, base fees are expected to be broadly in line, excluding the FY26 contribution of the public investments business in North America and Europe, and Net Other Operating Income is expected to be up, subject to timing of asset realisations.
BFS growth is expected to continue, with market dynamics and portfolio mix continuing to drive lower margins. MacCap transaction activity and investment-related income are expected to be down, subject to market conditions.
CGM net operating income is expected to be slightly up, excluding the impact from the divestment of the OnStream meters platform. The FY27 effective tax rate and compensation ratio are each expected to be broadly in line with historical levels.
For the medium term, management said Macquarie remains well-positioned to deliver superior performance with established, diverse income streams.
On regulation, Macquarie is working with APRA on a remediation plan, and in August 2026 it reported a breach related to the capital treatment of its structural interest rate risk hedging, which has been corrected with a $A100m governance-related overlay.
Key dates for Macquarie shareholders
- 12 November 2026: 1H27 dividend record date.
- 18 November 2026 to 27 November 2026: DRP pricing period of eight business days, with shares issued at a 1.5% discount to the prevailing market price. For what each date means, see how to read an ASX dividend announcement.
- 17 December 2026: 1H27 dividend payment date.
- 21 December 2026: Macquarie Bank Limited intends to resell all BCN2 to a nominated purchaser for $A100 each, followed by the proposed exchange of all or some of the BCN2 for MQG shares.
- 1 January 2027: APRA changes phasing out hybrid instruments as eligible capital take effect.
Get Financials News Before the Market Moves
Join 20,000+ investors receiving FREE breaking ASX news within minutes of release, with in-depth analysis already done. Non-resource sectors like banking, finance and tech are covered. Click the “Free Alerts” button at Big News Blast to get market-moving announcements the moment they break.