
Q1 FY27 highlights: record revenue of $18.3m and EBITDA of $2.4m
In its Q1 FY27 business update for the period ended 30 September 2026, Pureprofile reported record quarterly revenue of $18.3m, up 14% on the prior corresponding period (pcp) and 19% in constant currency. EBITDA rose 27% to $2.4m.
EBITDA margin improved to 13%, about 1 ppt above the 12% recorded in the pcp. EBITDA excludes significant items, which include share based payments, and all figures are preliminary and un-audited.
EBITDA growth materially outpaced revenue growth, which the company attributed to revenue growth, operating leverage and disciplined cost management.
Headline metrics for the quarter:
- Group revenue: $18.3m, up 14% on pcp
- EBITDA: $2.4m, up 27% on pcp
- EBITDA margin: 13%, compared with 12% in the pcp
- Platform revenue: $8.8m, up 108% on pcp
Martin Filz, CEO
“Pureprofile has made a strong start to FY27, with another record revenue quarter, revenue up 14% on pcp, and 19% in constant currency, and EBITDA up 27% on pcp, demonstrating operating leverage…”
| Metric | Q1 FY27 | Change on pcp |
|---|---|---|
| Revenue | $18.3m | Up 14% |
| EBITDA | $2.4m | Up 27% |
| EBITDA margin | 13% | Up about 1 ppt |
| ANZ revenue (inc Platform) | $9.6m | Up 21% |
| Rest of World revenue (inc Platform) | $8.7m | Up 7% |
| Platform revenue | $8.8m | Up 108% |
When big ASX news breaks, our subscribers know first
Regional and platform performance
ANZ revenue up 21% to $9.6m
ANZ revenue was supported by higher project volumes and higher average revenue per project across a broad base of clients. The company said the result reflects increased share of wallet and the depth of its client relationships in a core and profitable market.
Pureprofile Qual, formerly CRNRSTONE, was rebranded during the quarter, bringing the acquired qualitative research business under the Pureprofile brand. It contributed approximately 5 ppts to ANZ revenue growth.
The acquired qualitative research business was bought for $700,000 in cash at roughly 2.3x EBITDA, giving Pureprofile full-service capability and cross-selling access to its global client base.
Rest of World revenue up 7% to $8.7m (16% in constant currency)
Rest of World (ROW) revenue growth was supported by higher project volumes, although volume growth moderated from prior periods. Average revenue per project remained broadly stable in constant currency.
Foreign exchange reduced reported revenue by approximately $0.7m, reflecting the Group’s exposure to USD and GBP revenue. The company said this masked stronger underlying ROW growth.
Platform revenue up 108% to $8.8m
Platform revenue now represents approximately 48% of Group revenue, compared with 26% in the pcp. Growth was supported by continued expansion of API-driven integrations and growing adoption of automated data delivery solutions.
The company said strong client demand for scalable, technology-enabled offerings is expected to support continued Platform growth and contribute to margin expansion as the business scales.
How Platform revenue supports margins
Platform revenue comes from technology-enabled products, such as API integrations (software links that connect systems directly) and automated data delivery. Project-based research is different: each project is commissioned and delivered individually.
Pureprofile expects its scalable offerings to contribute to margin expansion as the business grows. In Q1 FY27, total operating expense growth of approximately 10% remained below revenue growth of 14%.
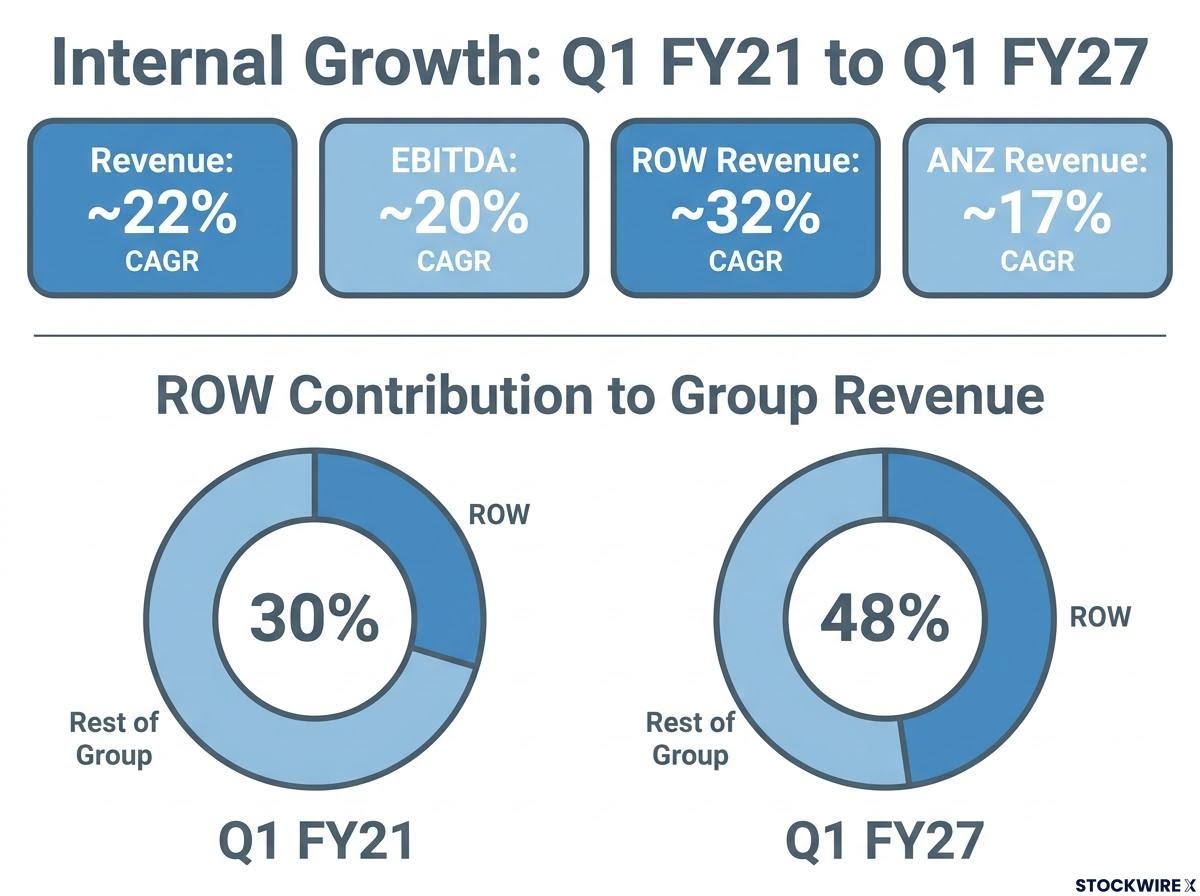
Over the six years from Q1 FY21 to Q1 FY27, the company reported internally funded growth with the following compound annual growth rates (CAGR):
- Revenue: approximately 22%
- EBITDA: approximately 20%
- ROW revenue: approximately 32%
- ANZ revenue: approximately 17%
ROW’s contribution to Group revenue rose from approximately 30% in Q1 FY21 to 48% in Q1 FY27.
Client growth, cash and funding position
Client numbers increased by 38 to 1,035 over the quarter, supported by further investment in ROW sales capability during the prior year. Annuity revenue was $16.9m for the rolling 12 months to 30 September 2026, compared with $16.7m to 30 June 2026.
Pureprofile also extended its $2.5m CBA loan facility to November 2029 on improved commercial terms. The annual line fee fell from 4.20% to 2.85%, plus BBSY interest.
FY27 guidance and what Pureprofile is targeting next
FY27 guidance is revenue of $72m to $75m and an EBITDA margin of 11-12%, the margin range having previously been 10% according to the CEO. Guidance is based on current expectations and assumes a continuation of current global macroeconomic conditions.
The outlook reflects continued growth across ANZ and ROW, including market share gains in the US and UK, and a continued shift in revenue mix toward scalable, technology-enabled solutions.
Key priorities during FY27 and beyond include:
- Grow market share in the large and underpenetrated UK and US markets
- Increase share of wallet across the existing client base
- Scale new products and expand global commercial reach
- Pursue targeted acquisitions, primarily in the US, that add scale, capability or geographic reach, with earnings-accretive acquisitions targeted to be funded from existing cash balances
- Expand margins through automation, AI integration and improved purchasing power across sample and other externally sourced services
For investors, the quarter combined record revenue, a guidance margin range lifted from the previous 10%, and a stated focus on targeted acquisitions alongside a disciplined approach to capital allocation.
For readers wanting to trace how management’s targets have evolved, our detailed coverage of Pureprofile’s earlier guidance upgrade explains how Rest of World revenue overtook ANZ and why the margin outlook was held at 10-11%.
Want the Next Tech Breakout in Your Inbox?
Join 20,000+ investors getting FREE breaking ASX news within minutes of release, with in-depth analysis already done. Click the “Free Alerts” button at Big News Blast to receive market-moving tech announcements the moment they break and stay ahead of the market.