
Q1 FY27 highlights: record $18.3m revenue and 27% EBITDA growth
In its October 2026 investor presentation covering Q1 FY27 (July to September 2026), Pureprofile outlined group revenue up 14% on the prior corresponding period (pcp) to a record $18.3m, or 19% in constant currency. EBITDA rose 27% to $2.4m.
EBITDA margin improved to 13% from 12% in the pcp. Management noted that Pureprofile collaborated with 1,035 clients in the quarter and now works with over 1,000 clients globally.
EBITDA growth outpaced the 14% revenue increase, which management described as demonstrating operating leverage. All figures are preliminary and un-audited, and EBITDA and EBITDA margin exclude significant items and share based payments.
Other highlights from the presentation include:
- Platform revenue increased 108% on pcp to $8.8m, representing 48% of Group revenue.
- Rolling 12-month annuity revenue reached $16.9m, approximately 25% of Group revenue, compared with $16.7m at June 2026.
- The $2.5m CBA facility was extended to November 2029, with the annual line fee reduced from 4.20% to 2.85%, plus BBSY interest.
When big ASX news breaks, our subscribers know first
Regional performance and operating leverage
ANZ and Rest of World
ANZ revenue increased 21% on pcp to $9.6m, supported by broad-based client growth, increased share of wallet and higher average project values.
Rest of World (ROW) revenue rose 7% to $8.7m, or 16% in constant currency. Management said stronger underlying growth was masked by an adverse FX impact of approximately $0.7m, and that volume growth moderated from prior periods.
| Metric | Q1 FY27 | vs Q1 FY26 |
|---|---|---|
| Revenue | $18.3m | 14% |
| EBITDA | $2.4m | 27% |
| EBITDA margin | 13% | 1 ppt |
| ANZ (incl. Platform) | $9.6m | 21% |
| Rest of World (incl. Platform) | $8.7m | 7% |
| Platform | $8.8m | 108% |
Cost discipline
The margin gain was supported by employee expense growth of just 5% on pcp, despite a $79k FX loss during the quarter.
Six-year trend
Quarterly revenue has grown from $5.4m in Q1 FY21 to $18.3m in Q1 FY27, a 22% six-year compound annual growth rate (CAGR). Platform revenue rose from $0.2m to $8.8m over the same period, an 83% six-year CAGR.
ROW revenue (including Platform) has increased from 30% to 48% of total revenue over six years. In constant currency, the Q1 FY27 split was 49% ROW and 51% ANZ.
How Pureprofile captures and delivers human intelligence
Pureprofile describes its business as connecting organisations to trusted human intelligence, using technology to deliver it at scale. In practice, this means consented, profiled panel members whose surveys, behavioural and transactional inputs become first-party, consented and privacy-compliant data.
Platform revenue comes from scalable, technology-enabled solutions. Management linked the growing platform share to margin expansion, noting that more clients leveraging solutions contributed to the 1 ppt margin gain.
Clients can access Pureprofile in four ways:
- Managed Services: end-to-end insights delivered by the Pureprofile team.
- Datarubico Insights Creator: AI-powered self-service insights.
- Datarubico Audience Access: self-service access to trusted audiences.
- APIs: direct access to Pureprofile human intelligence and audiences.
The company outlined the following advantages as its moat:
- 20M+ panel members, collected with consent and transparency.
- 271 Pureprofile insights experts around the world.
- Ranked in the top 150 quality data suppliers globally, per the Verisoul 2025 Market Research Quality Report.
- 94% of revenue from repeat clients (FY26).
- Global coverage in 100+ countries.
Strategic roadmap and FY27 guidance
Management framed the next growth phase around the US and UK, which it said are currently 40 times and 11 times larger than Australia, respectively. According to ESOMAR Global Market Research 2026, the US accounts for 54% of global insights industry turnover, from a total of US$153,274m.
The FY27 priorities are revenue growth, margin expansion and shareholder value. The last includes targeted, earnings-accretive acquisitions, primarily focused on the US.
Pureprofile has form on earnings-accretive acquisitions, having bought qualitative research specialist CRNRSTONE for $700,000 cash at 2.3x EBITDA, funded without issuing new shares.
| FY27 guidance | Range | Comparison |
|---|---|---|
| Revenue | $72m to $75m | 11% to 15% on FY26 |
| EBITDA margin | 11% to 12% | FY26: 10% |
Guidance is based on current expectations and assumes a continuation of current global macroeconomic conditions.
The FY26 presentation showed full-year revenue of $65.0m at the top of guidance, with EBITDA up 25% to $6.5m, setting the base against which the FY27 range of $72m to $75m is measured.
Management also identified AI opportunities in three areas: internal solutions such as translations, coding, probing and reconciliation; client-facing solutions such as The Hub and audio and video surveys; and AI companies as clients that need Pureprofile data to feed their large language models.
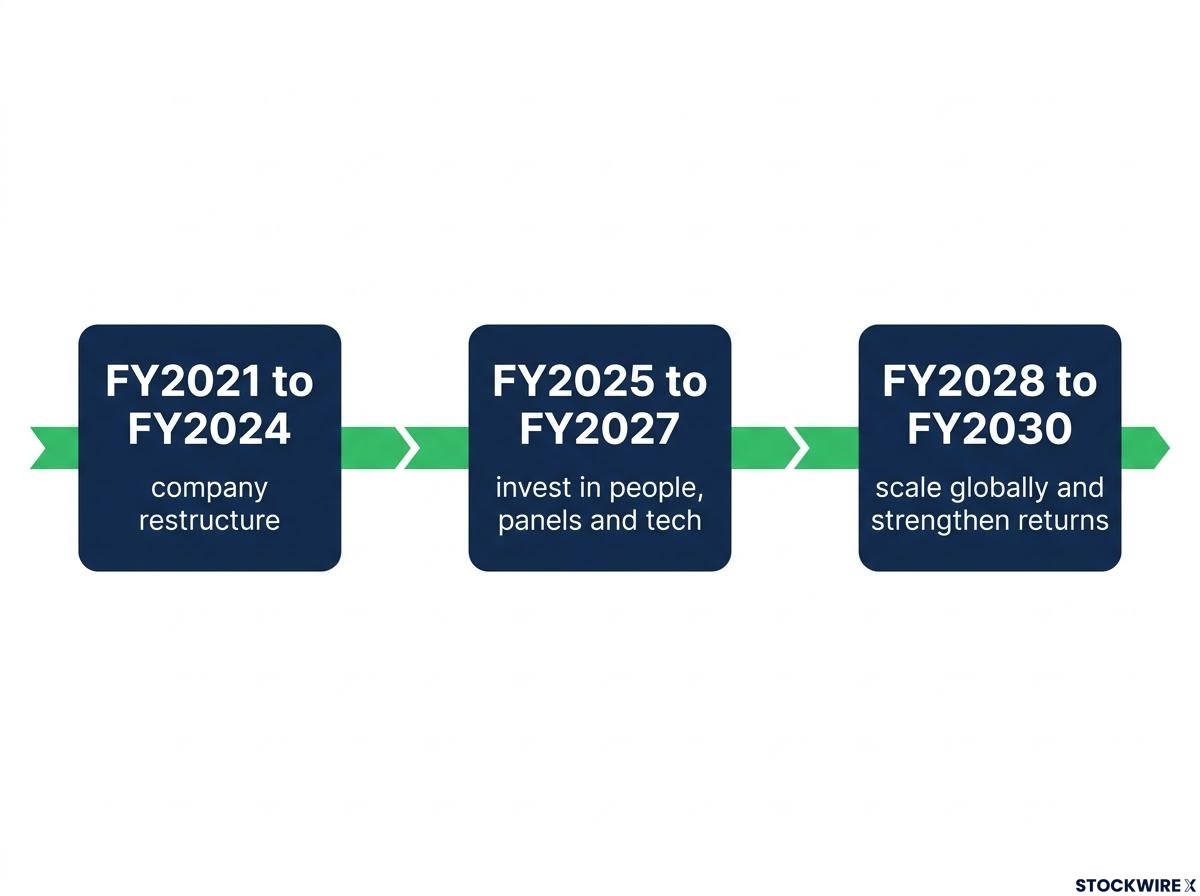
Pureprofile outlined its growth journey in three phases:
- FY2021 to FY2024: company restructure.
- FY2025 to FY2027: invest in people, panels and tech.
- FY2028 to FY2030: scale globally and strengthen returns.
Don’t Miss the Next Tech Breakout on the ASX
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, complete with in-depth analysis. Click the “Free Alerts” button at Big News Blast to see the next market-moving tech announcement the moment it breaks, and stay ahead of the market.