
In its October 2026 AGM presentation, Pureprofile outlined record Q1 FY27 revenue of $18.3m
In its October 2026 AGM presentation, Pureprofile highlighted record quarterly revenue of $18.3m for Q1 FY27, up 14% on the prior corresponding period (pcp) and 19% in constant currency. EBITDA rose 27% to $2.4m.
The presentation was delivered by Chair Michael Anderson, CEO Martin Filz and CFO Melinda Sheppard. Management also outlined FY27 guidance of $72m to $75m in revenue and an EBITDA margin of 11% to 12%.
EBITDA growing faster than revenue is the investor angle, with management describing the result as demonstrating operating leverage. Q1 FY27 (July to September 2026) figures are preliminary and un-audited, and EBITDA excludes significant items and share based payments.
Q1 FY27 results at a glance
The company highlighted growth across both regions and in its Platform business. The table below summarises the metrics presented.
| Metric | Q1 FY27 | Change on pcp |
|---|---|---|
| Group revenue | $18.3m | +14% (+19% constant currency) |
| ANZ revenue | $9.6m | +21% |
| ROW revenue | $8.7m | +7% (+16% constant currency) |
| Platform revenue | $8.8m | +108% |
| EBITDA | $2.4m | +27% |
| EBITDA margin | 13% | 12% in pcp |
Management said ANZ growth was supported by broad-based client growth, increased share of wallet and higher average project values. ROW revenue reflected stronger underlying growth masked by an adverse FX impact of approximately $0.7m.
Platform revenue represented 48% of Group revenue. Other points from the presentation:
- 1,035 clients collaborated with in Q1 FY27
- Rolling 12-month annuity revenue of $16.9m, approximately 25% of Group revenue, compared with $16.7m at June 2026
- The $2.5m CBA facility extended to November 2029
- The annual line fee reduced from 4.20% to 2.85%, plus BBSY interest
When big ASX news breaks, our subscribers know first
Six-year profit transformation behind the numbers
The presentation showed FY26 Group revenue of $65.0m, a 20% five-year compound annual growth rate (CAGR). EBITDA reached $6.5m, a 19% five-year CAGR.
Statutory net profit after tax (NPAT) was $2.3m, up 47% on FY25, marking 3 consecutive years of statutory profitability. That is a $7.9m NPAT improvement since FY21, while EBITDA more than doubled.
Platform revenue reached $19.3m in FY26, a 78% five-year CAGR.
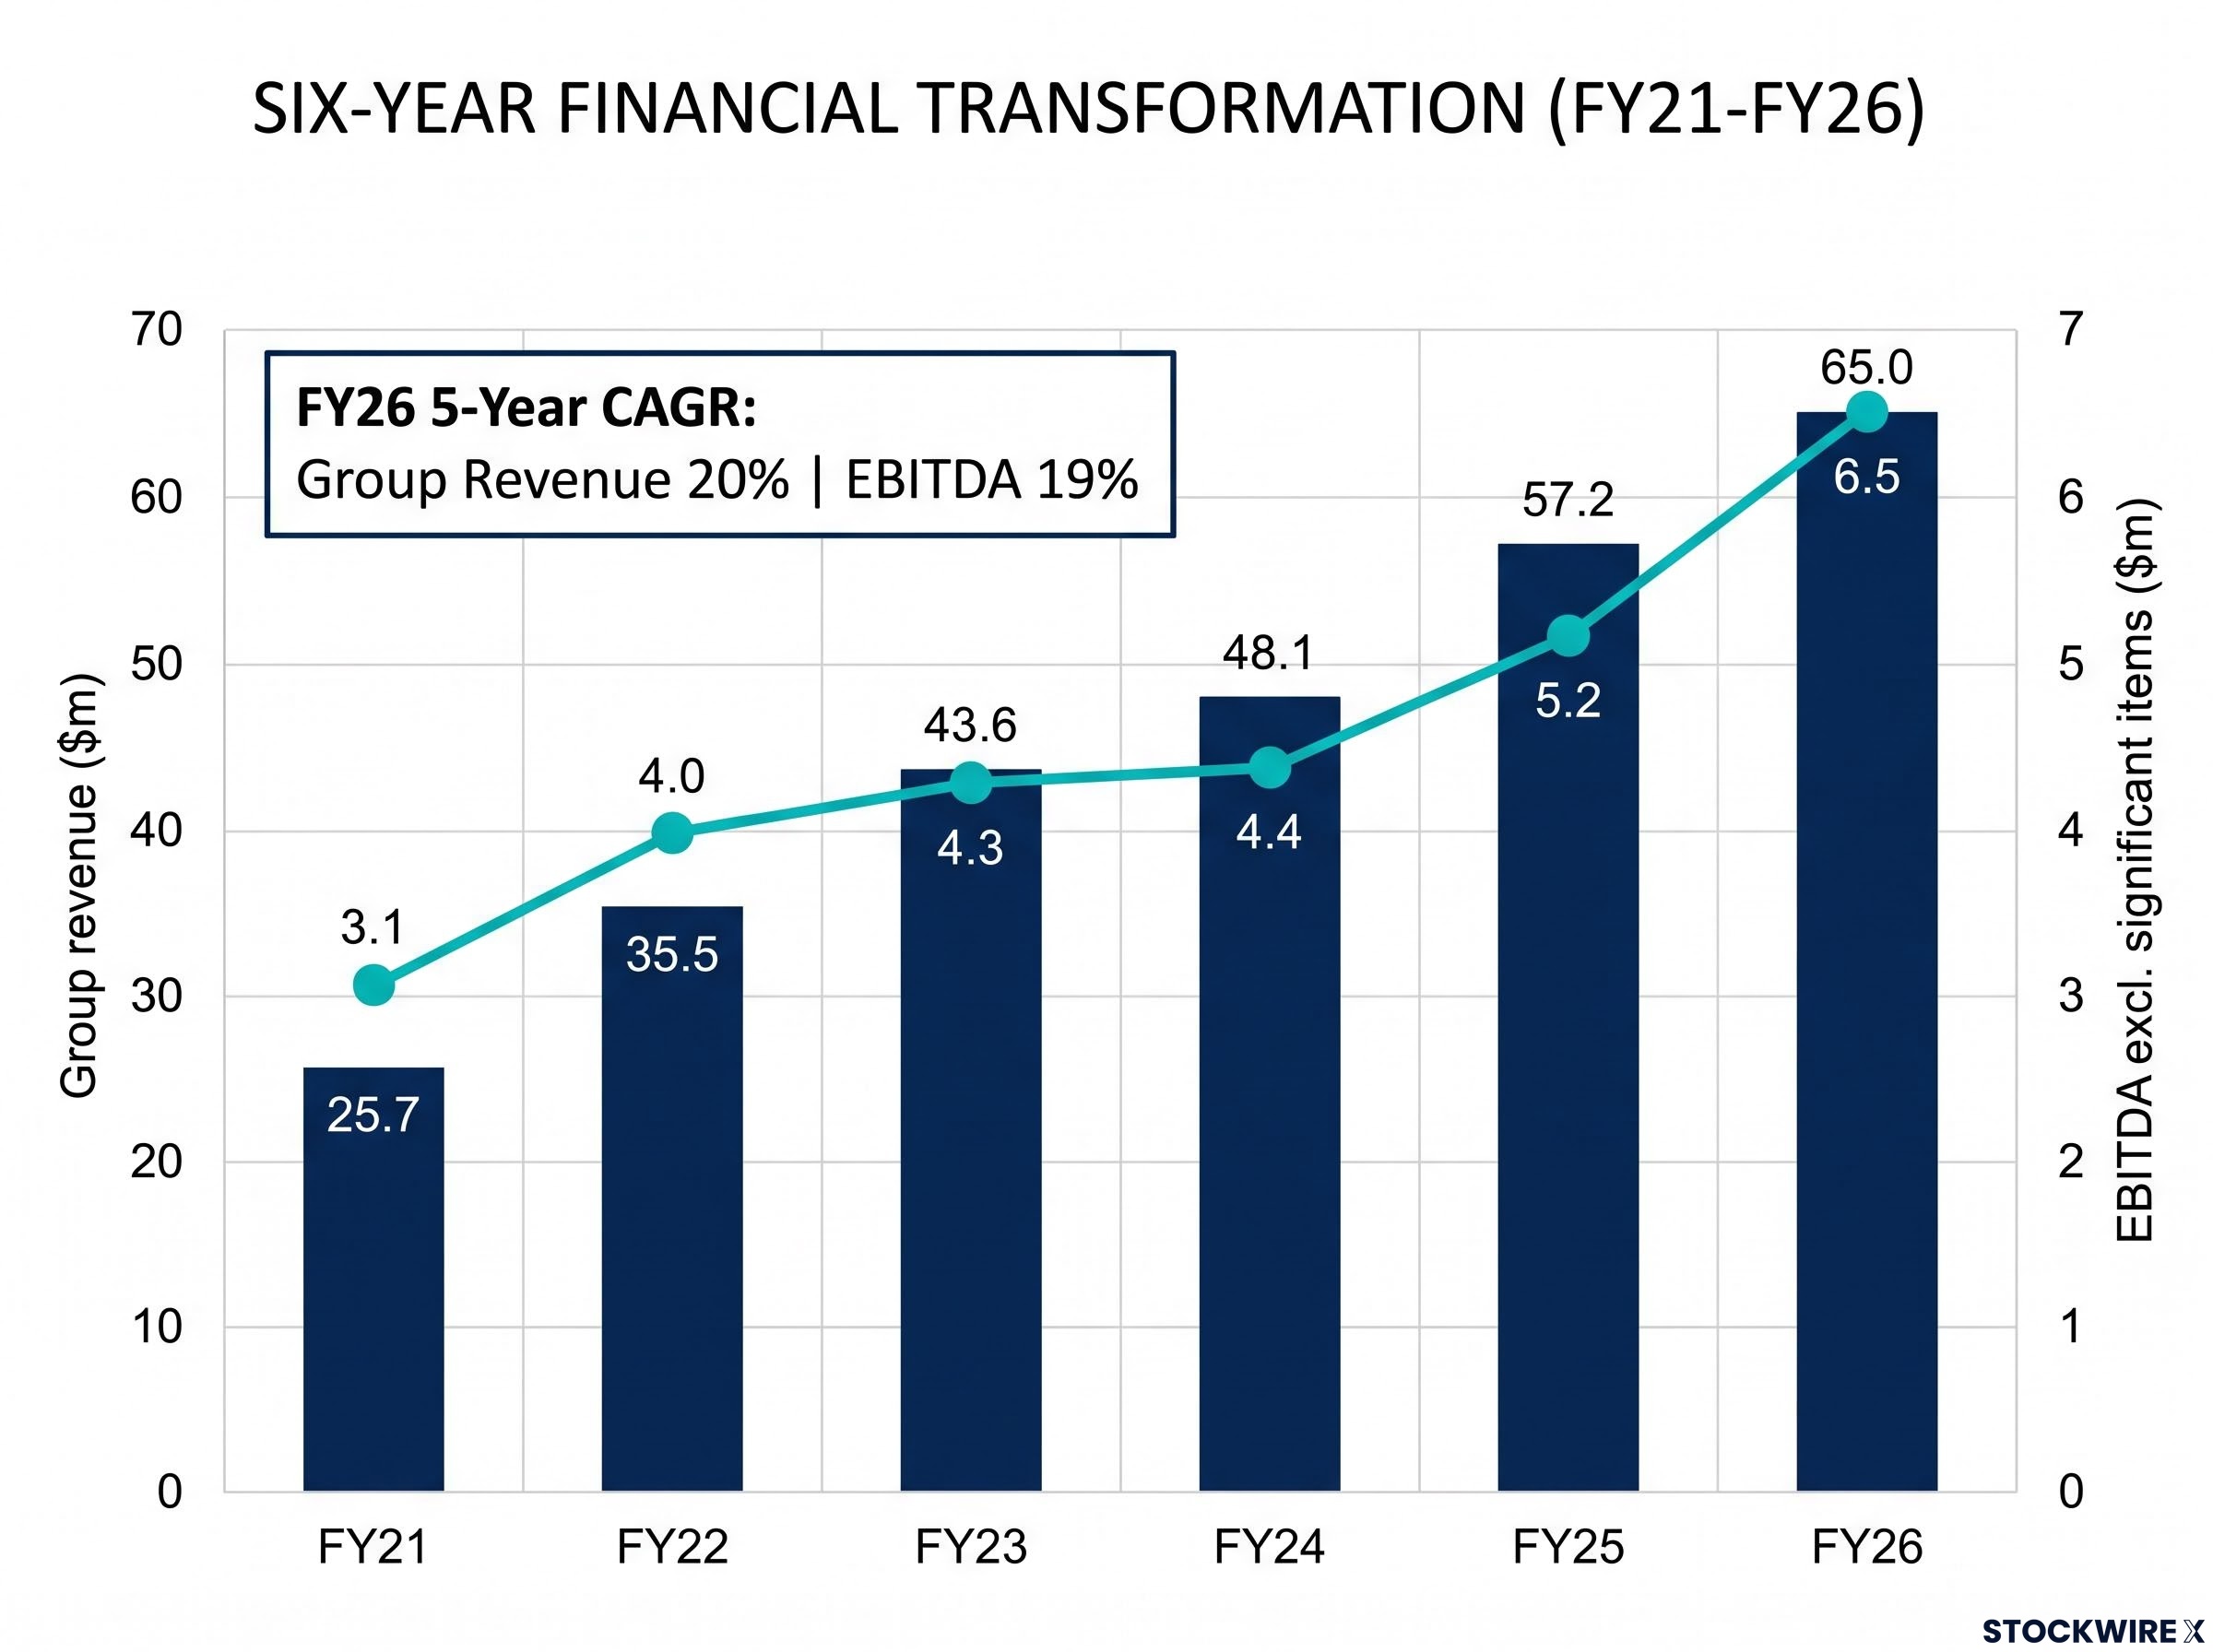
| Year | Group revenue ($m) | EBITDA excl. significant items ($m) |
|---|---|---|
| FY21 | 25.7 | 3.1 |
| FY22 | 35.5 | 4.0 |
| FY23 | 43.6 | 4.3 |
| FY24 | 48.1 | 4.4 |
| FY25 | 57.2 | 5.2 |
| FY26 | 65.0 | 6.5 |
The FY21 net loss after tax excludes loan forgiveness of A$8.4m.
FY27 guidance in focus
FY27 revenue guidance of $72m to $75m implies 11% to 15% growth on FY26. EBITDA margin guidance of 11% to 12% compares with 10% in FY26.
Guidance is based on current expectations and assumes a continuation of current global macroeconomic conditions.
What is human intelligence and why does it matter in an AI world?
Pureprofile describes trusted human intelligence as consented, verified, first-party data capturing real human experiences, opinions and behaviours, gathered through surveys, behavioural and transactional inputs. The company stated that in an AI-driven world, this type of data is increasingly valuable.
Management pointed to several defensive advantages:
- 20M+ panel members
- 271 insights experts globally
- A Top 150 ranking for the lowest survey fraud in the Verisoul 2025 Market Research Quality Report
- 94% of revenue from repeat clients in FY26
- Insights delivered across 111 countries
On AI, management identified internal efficiency gains, client-facing solutions such as The Hub and audio and video surveys, and AI companies as clients needing data to feed their LLMs (large language models).
Clients can access Pureprofile human intelligence through four routes:
- Managed Services: end-to-end insights delivered by the team
- Datarubico Audience Access: self-service access to trusted audiences
- Datarubico Insights Creator: AI-powered self-service insights
- APIs: direct access to Pureprofile human intelligence and audiences
Growth strategy: US and UK expansion and margin focus
Management said the US and UK are currently 40 times and 11 times larger than Australia, respectively. The US accounts for 54% of the US$153,274m global insights industry turnover in 2024, according to ESOMAR.
Three priorities were outlined for FY27:
- Revenue growth: grow UK and US market share, increase share of wallet across existing clients and win new clients
- Margin expansion: grow revenue faster than centralised costs and use technology, AI and process improvements to lift productivity
- Shareholder value: deliver sustainable earnings growth through disciplined capital allocation and earnings-accretive acquisitions, primarily focused on the US
The FY28 to FY30 phase is titled “Scale globally and strengthen returns”. It includes building a larger US business through organic growth and targeted acquisitions.
The CRNRSTONE acquisition, completed for $700,000 in cash at 2.3x EBITDA, offers a template for the earnings-accretive, cash-funded deals management has flagged as part of its growth plan.
What happens next for Pureprofile
Michelle Kvello commenced as Non-Executive Director on 28 October 2026.
The FY27 guidance period targets revenue of $72m to $75m and an EBITDA margin of 11% to 12%, based on current expectations and a continuation of current global macroeconomic conditions.
The FY28 to FY30 phase is outlined as scaling globally, including a larger US business via organic growth and targeted acquisitions.
Get Tech and Data News Before the Market Moves
Get FREE breaking ASX news delivered to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors already staying ahead of the crowd. Click the “Free Alerts” button at Big News Blast to receive market-moving announcements the moment they break.