
A proposed merger to create a scaled ASX diagnostics leader
In its investor presentation released on 22 September 2026, Genetic Signatures Limited (ASX: GSS) outlined a proposed merger with Microba Life Sciences Limited (ASX: MAP) via scheme of arrangement. The transaction would combine two complementary Australian diagnostics businesses, with GSS’s syndromic PCR products serving hospital and reference laboratories alongside Microba’s metagenomic testing for clinicians and pharma partners, forming a group covering an expanded gastrointestinal testing pathway.
The presentation cited combined FY26 revenue of approximately $30 million, combined cash and term deposits of approximately $30 million at 30 June 2026, around 149 employees, and products reaching more than 30 countries. Both Boards unanimously recommend the transaction, subject to a superior proposal, the Independent Expert’s conclusion, and finalisation and execution of the Scheme Implementation Deed.
When big ASX news breaks, our subscribers know first
Transaction structure at a glance
The table below summarises the key terms of the proposed transaction as outlined in the presentation.
| Term | Detail |
|---|---|
| Structure | GSS acquires 100% of Microba Life Sciences (ASX: MAP) by scheme of arrangement under Part 5.1 of the Corporations Act; merged group remains listed as ASX: GSS |
| Consideration | 0.654 new GSS shares per Microba share; no cash consideration, no new debt, no financing condition |
| Implied exchange basis | Prior one-month VWAP of 5.48 cents per Microba share and 8.38 cents per GSS share, as at 18 September 2026 |
| Ownership (undiluted) | Approximately 469 million new GSS shares issued; Microba shareholders ~67%, GSS shareholders ~33% |
| Pro forma financials | ~$30M FY26 revenue; ~$30M combined cash and term deposits at 30 June 2026 |
On governance, the presentation noted the merged group’s board would comprise six directors, three nominated by each company, providing equal representation despite the asymmetric ownership split.
Why both Boards support the deal — four strategic pillars
Significantly enhanced scale
The combined entity had pro forma FY26 revenue of approximately $30 million, compared with $14.8 million for each business in isolation. With around 149 employees, manufacturing in Sydney and Brisbane, and distribution across more than 30 countries, the presentation highlighted the potential for a larger and more liquid listed vehicle to re-rate as revenue and earnings scale.
A materially wider route to market
The presentation detailed how each company’s products gain access to customer segments they do not currently serve. GSS holds NHS and hospital laboratory relationships, while Microba brings Sonic Healthcare, SYNLAB, and Genova Diagnostics distribution relationships. A combined UK platform, described as the group’s fastest-growing market, was cited as a concrete example of this complementary positioning.
The Hvidovre Hospital contract activation in August 2026 converted a ten-year supply agreement into live commercial testing, establishing a high-profile European reference site that the combined group can leverage to support further EMEA tender activity.
A financially attractive combination
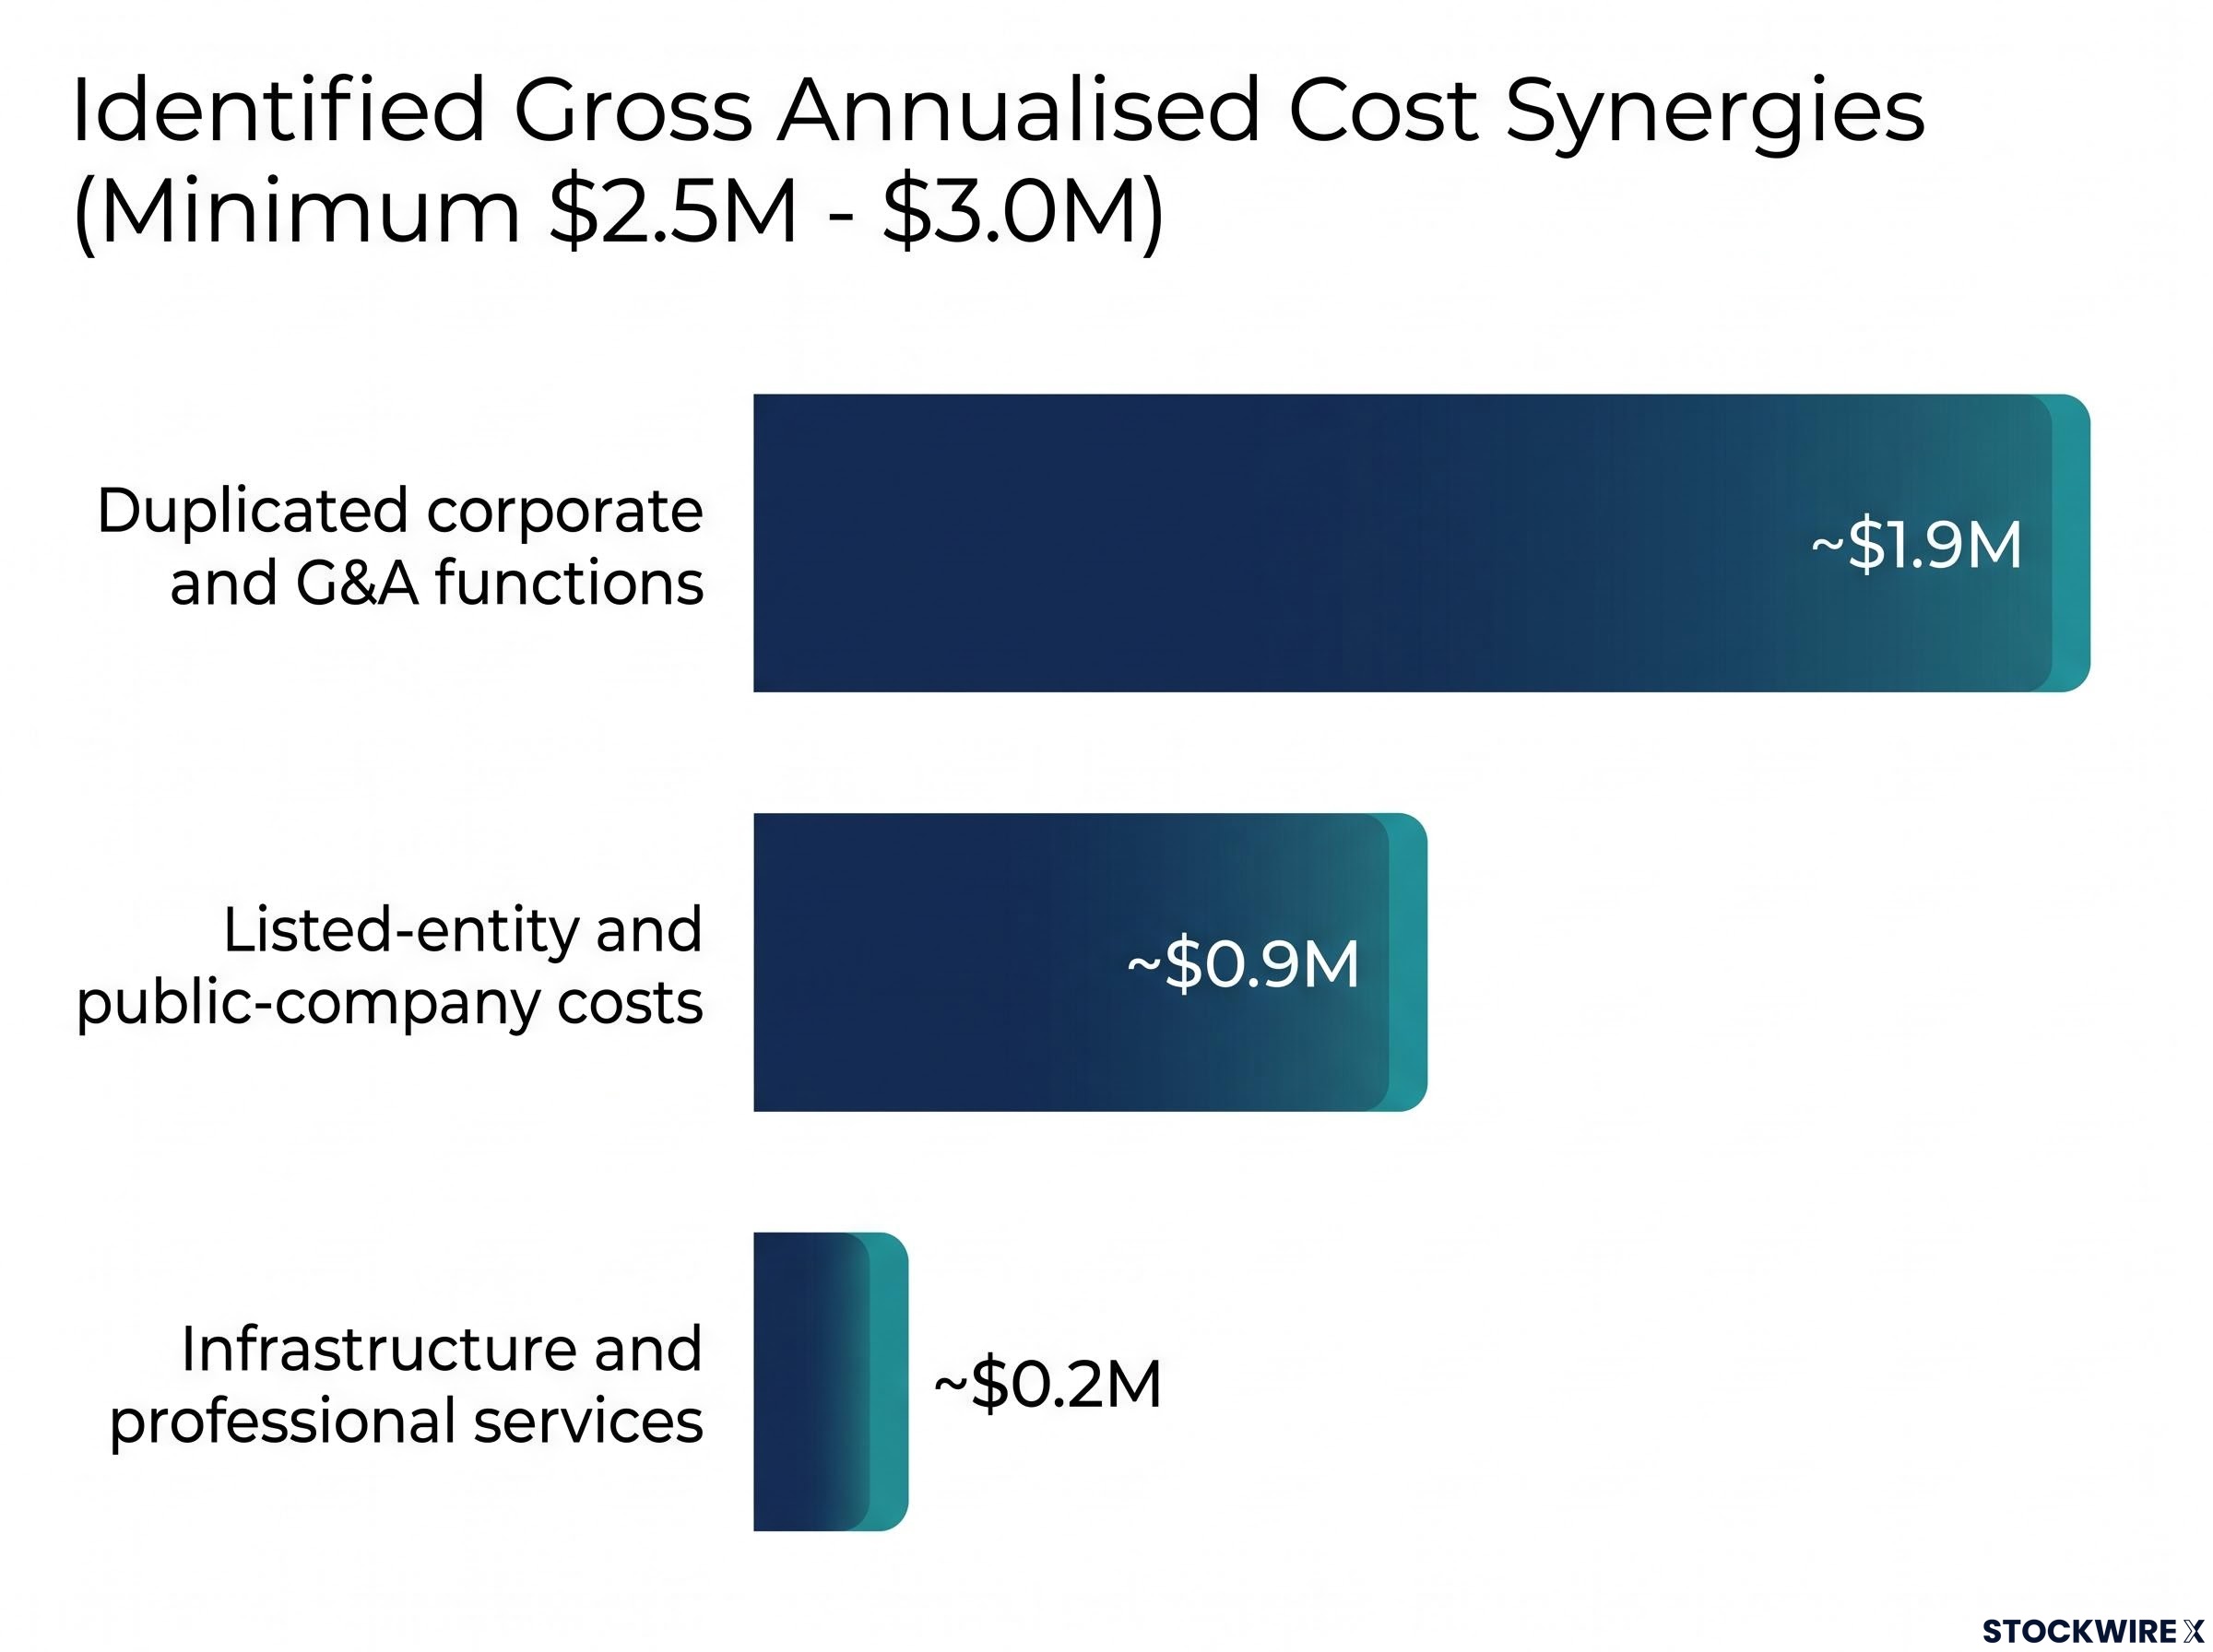
The transaction is proposed to be funded entirely in scrip, with no cash outlay and no new debt. Management highlighted a minimum of $2.5–$3.0 million in identified gross annualised cost synergies, with an approximately four-month payback on one-off costs. The presentation broke down the synergy sources as follows:
- ~$0.9M: Listed-entity and public-company costs (board fees, D&O insurance, audit, share registry, ASX and ASIC fees)
- ~$1.9M: Duplicated corporate and G&A functions (executive leadership, finance, company secretarial, people and culture)
- ~$0.2M: Infrastructure and professional services (software licences, corporate office space, corporate advisory)
The presentation noted that realised synergies remain subject to detailed integration planning. Additional synergy opportunities were also cited across laboratory and manufacturing footprint, procurement, combined sales and distribution channels, and shared quality, regulatory, and R&D capability, representing potential upside beyond the minimum identified.
Positioned for future growth through to cash-flow breakeven
The combined balance sheet of approximately $30 million in cash and term deposits is anticipated to provide a runway through to cash-flow breakeven. Management highlighted the end-to-end gastrointestinal offering as a differentiated proposition that neither business can deliver independently. GSS shareholders are noted to retain their existing holding, their listing, and three of six board seats under the proposed structure.
Genetic Signatures FY26 financial results showed a net loss narrowing 30% to $14.0 million alongside a debt-free $22.1 million cash position, with $5 million in annualised cost savings locked in for FY27 before the merger discussions accelerated.
Understanding the two businesses — what each brings to the merger
What Genetic Signatures does
Genetic Signatures is a specialist molecular diagnostics company focused on the development and commercialisation of its proprietary 3base® platform technology. The company designs and manufactures real-time PCR-based products under the EasyScreen™ brand for infectious disease detection in high-volume hospital and pathology laboratories.
In FY26, Genetic Signatures contributed approximately $14.8 million in revenue and held approximately $22.1 million in gross cash at 30 June 2026. The company holds FDA 510(k) clearance for its gastrointestinal parasite kit and maintains a distribution footprint spanning more than 30 countries.
What Microba brings
Microba is an ASX-listed precision microbiome company offering metagenomic diagnostics, including Microbiome Explorer, MetaPanel, and GI Navigator, to clinicians and pharma partners. Its FY26 group core testing volume grew 78% year-on-year and core testing revenue rose 92% year-on-year, representing the primary growth engine of the proposed combined group.
Distribution relationships include Sonic Healthcare, SYNLAB, and Genova Diagnostics. Since November 2025, Microba has signed 43 enterprise clinic accounts in Australia, with more than 175 further targets in the pipeline. Its UK platform, built around the Invivo Clinical clinician network, recorded UK core test sales up 92% on the prior corresponding period in Q4 FY26.
Microba also holds a therapeutics asset: MAP 315, a Phase 2-ready live biotherapeutic for ulcerative colitis, with an active partnering process underway and internal R&D investment currently paused. These metrics are sourced from the Microba Life Sciences Q4 FY26 investor presentation, dated 16 July 2026, as cited in the GSS presentation.
Contribution analysis
Genetic Signatures contributes roughly three quarters of the combined cash and the larger share of net assets. Microba contributes the larger share of near-term revenue growth and is expected to reach cash-flow breakeven before Genetic Signatures.
What comes next — indicative merger timetable
The presentation outlined the following indicative milestones for the proposed transaction:
- Despatch of the GSS Notice of Meeting — late September 2026
- GSS shareholder meeting to approve the proposed merger — October 2026
- Execution of the Scheme Implementation Deed (subject to GSS shareholder approval) — October 2026
- Lodgement of the Scheme Booklet with ASIC — mid November 2026
- First Court hearing — December 2026
- Despatch of the Scheme Booklet to Microba shareholders — December 2026
- Microba Scheme Meeting — January 2027
- Second Court hearing — January 2027
- Effective Date — January 2027
- Scheme record date — February 2027
- Implementation Date and issue of new GSS shares — February 2027
All dates are indicative and subject to change, including as a result of ASX, ASIC, and Court processes.
Looking ahead, the combined group’s stated vision, as outlined in the presentation, is to become the ASX-listed leader in gastrointestinal and infectious disease diagnostics, serving a broader customer base spanning rapid first-line pathogen detection through to metagenomic profiling.
Ready to Explore the GSS–Microba Merger and What It Means for ASX Diagnostics?
The proposed merger between Genetic Signatures (ASX: GSS) and Microba Life Sciences (ASX: MAP) aims to create a scaled, end-to-end gastrointestinal diagnostics leader, combining approximately $30 million in FY26 revenue with a $30 million cash runway targeted to carry the group through to cash-flow breakeven. With $2.5–$3.0 million in identified annualised cost synergies and a commercial footprint spanning more than 30 countries, the combined entity is positioned as a differentiated proposition that neither business could deliver independently.
For a deeper look at the technology and pipeline underpinning this transaction, visit the Genetic Signatures investor centre to explore the 3base® platform, EasyScreen™ product suite, and the company’s broader commercialisation strategy ahead of the indicative February 2027 implementation date.