
FY26 results signal a turning point for Atomo Diagnostics
In its FY26 results presentation, Atomo Diagnostics outlined a year of meaningful commercial progress, with total revenue rising 41% to $5.3 million (up from $3.8 million in FY25). The company framed the year as a transition “from foundation to global scale,” with EBITDA losses narrowing 39% year-on-year to $(2.06) million and cash on hand of $3.71 million at 30 June 2026, with no debt. Concurrent with the results, the board confirmed Dr. Cheri Walker as Interim CEO, a transition the presentation positioned as a deliberate shift toward global commercial execution following 15 years of foundation-building under founder John Kelly.
When big ASX news breaks, our subscribers know first
What drove FY26 revenue growth?
HIV franchise delivers 21% growth
The HIV segment remained Atomo’s established revenue anchor, generating $2.8 million, up 21% year-on-year. Key developments across the distribution network included:
- Australian pharmacy network grew from 126 to 196 active pharmacies (59 added in FY26), with a target to grow 6x over three years
- New Zealand expansion reached 73 pharmacies activated since the FY25 launch, with an 8x growth target
- NAPWHA government program demand grew 275% over the prior 24 months, reflecting strong institutional adoption
International HIV revenue also accelerated, with NFLD (Europe) up 69% year-on-year (approximately A$300k to A$500k) and Viatris (LMIC) up 74% year-on-year (approximately A$800k to A$1.4 million).
OEM/Pascal revenue surges 209%
The OEM segment was the standout growth driver for the year, reaching $2.2 million, up 209%. The primary contributor was the Lumos Diagnostics FebriDx launch, which uses Atomo’s Pascal device for rapid blood-based testing. Three OEM partners contributed to this result:
- Lumos Diagnostics (FebriDx): Atomo received FY26 Pascal orders of approximately A$1.9 million, a nine-fold increase on the prior year. Lumos also signed a six-year supply agreement with PHASE Scientific, with Lumos anticipating FebriDx product revenues of up to US$317 million over the term, subject to CLIA waiver being granted and contracted minimum order quantities being achieved.
- Chromacare (Ferritin): An initial order of approximately A$170,000 received for a rapid iron-level testing product targeting professional and self-test markets.
- Confidential UK Partner: 20,000 Pascal units ordered to support validation and registration requirements, with a commercial supply agreement anticipated in early FY27.
| Metric | FY26 ($m) | FY25 ($m) | Change (%) |
|---|---|---|---|
| Revenue | 5.33 | 3.79 | +41% |
| Gross Profit | 1.88 | 1.92 | (2%) |
| Gross Margin | 35% | 51% | – |
| Underlying EBITDA | (2.06) | (3.38) | +39% |
Gross margin compression from 51% to 35% reflects a product mix shift toward lower-margin global health segments. The FY25 gross margin also included approximately $340k in one-time licence fees. Overall operating expenses fell approximately $640k (around 9%) year-on-year, partially offsetting the margin headwind.
Inside Atomo’s pipeline — what’s coming next
Point-of-care diagnostics (POCT) are rapid tests that can be conducted outside a centralised laboratory, delivering results at or near the patient. Decentralised rapid testing has become a structural growth trend, accelerated by the pandemic and now driven by broader changes in how healthcare systems deploy timely diagnostic capability globally.
Atomo operates two complementary business lines: its own branded POCT products targeting professional and self-test channels, and the Pascal OEM platform, which supplies its proprietary all-in-one blood-testing device to third-party partners developing their own rapid tests. This dual model diversifies revenue risk and creates multiple pathways for the Pascal platform to generate recurring income across different indications and geographies.
The presentation highlighted two pipeline products as the primary sources of future revenue beyond the existing HIV and OEM base.
Active syphilis — clinical trials targeted for early CY27
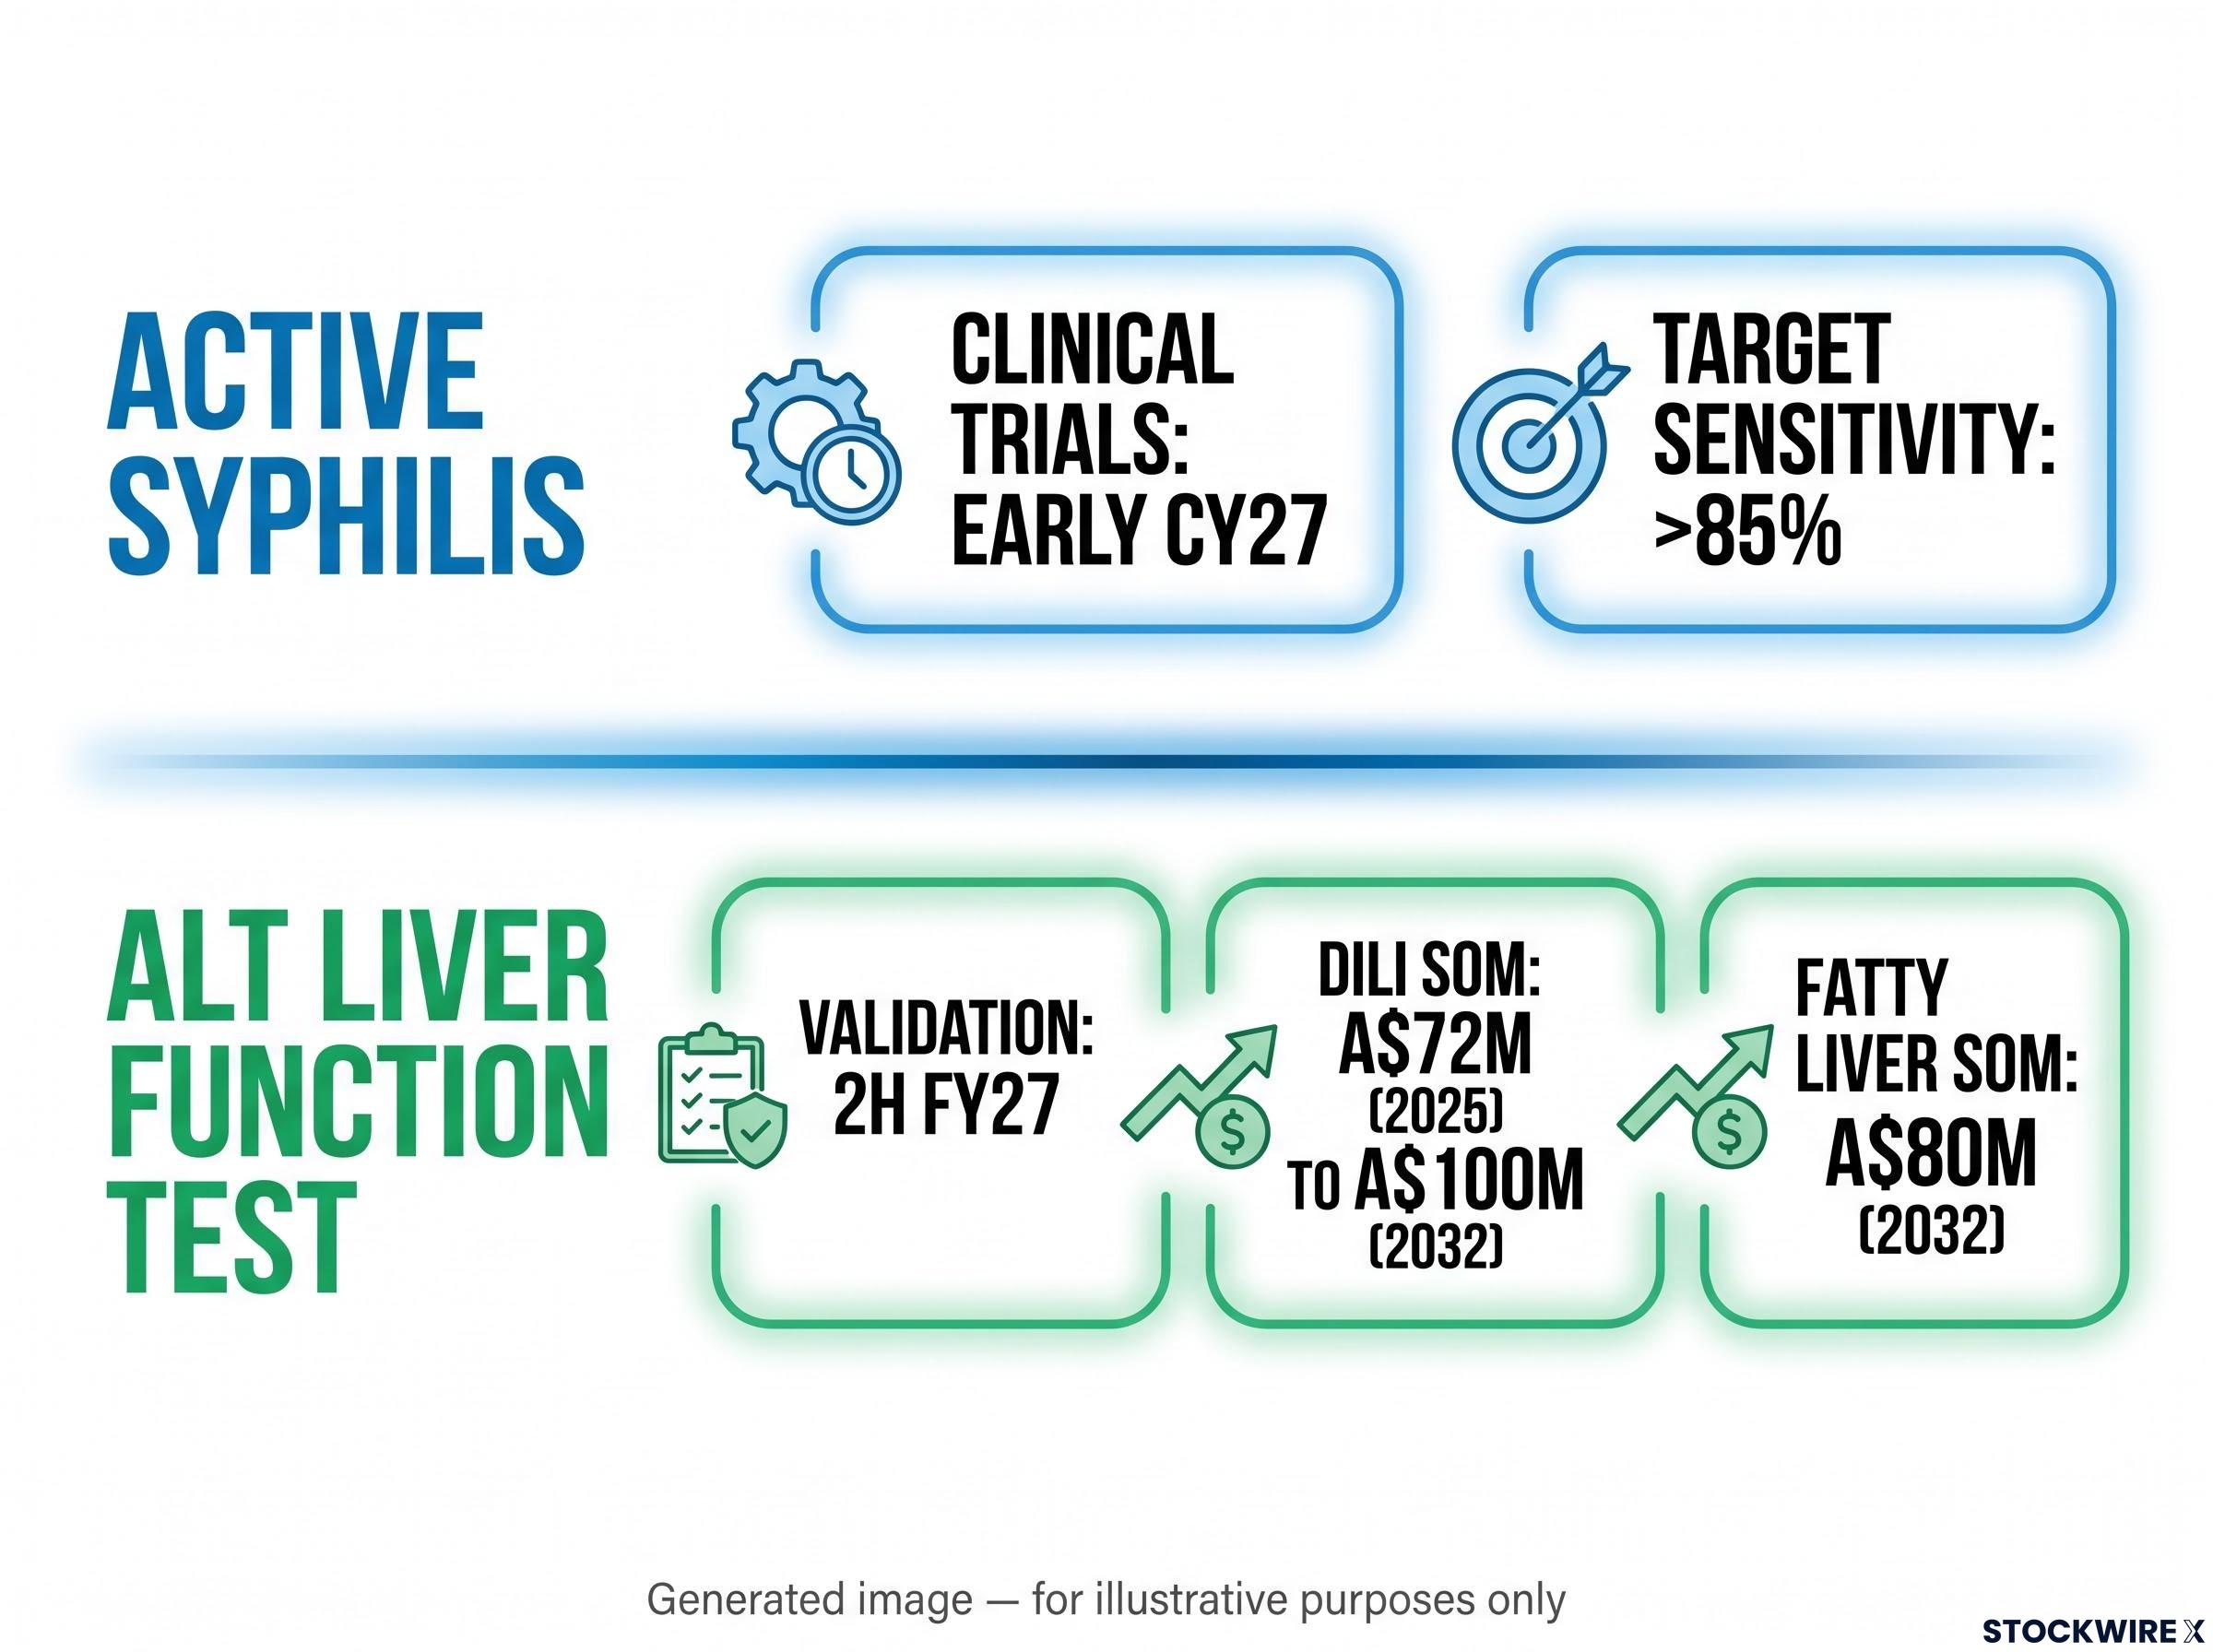
Active syphilis detection is the most advanced near-term pipeline asset. Product development and initial verification have been completed, and technology transfer to manufacturing commenced in Q4 FY26 and Q1 FY27. Clinical trials are targeted for early CY27.
The presentation highlighted a clear unmet clinical need: no existing rapid test can reliably distinguish active from prior infection, and no current test format is optimised for easy, reliable self-testing. Atomo’s product targets sensitivity greater than 85% for active syphilis detection, described in the presentation as market-leading. Commercialisation is also expected to benefit from channel leverage, with the same HIV distribution network reducing both cost and time to market.
ALT liver function test — a large addressable market enters the pipeline
The ALT liver function test is at an earlier development stage, with validation targeted for 2H FY27. The presentation identified two primary use cases: Drug-Induced Liver Injury (DILI) monitoring for patients on drugs requiring ALT surveillance, and fatty liver disease screening, which affects more than 1.5 billion people globally.
Serviceable obtainable market (SOM) estimates provided in the presentation were:
- DILI: A$72 million (2025) growing to A$100 million (2032)
- Fatty Liver Disease: A$80 million (2032)
Development will be supported by non-dilutive funding where available. A CRC-P grant is supporting active syphilis development, and the company plans to engage pharmaceutical, CRO, or commercial partners for the liver test during FY27.
Exclusive global licensing for the liver function test runs through December 2044, with product development substantively complete and an existing 20,000-cassette pharmaceutical company evaluation already underway in a US drug trial, providing commercial validation ahead of the FY27 validation timeline.
New leadership, clean balance sheet, clear runway into FY27
CEO transition sets up the next phase
The presentation framed the leadership change as a strategic evolution. John Kelly’s 15 years as founder and CEO established Atomo’s innovation and regulatory foundation, with Walker’s appointment intended to drive the next phase of global commercial growth. The presentation noted that Walker is positioned closer to Atomo’s key growth markets, particularly the US and Europe.
Cheri Walker, CEO Atomo Diagnostics
“It’s an exciting time to join Atomo as we enter our next phase of growth and continue building a strong pipeline of point-of-care diagnostic products for significant global markets. We are making good progress with our active syphilis and ALT liver function tests, while also evaluating several additional indications to complement our established HIV products. Atomo’s all-in-one blood-based testing platform is designed to deliver superior usability and greater consistency of results — an important advantage as we expand our professional-use diagnostics portfolio.”
Financial position supports the growth plan
The balance sheet at 30 June 2026 reflected a sound financial position heading into FY27:
- Cash and cash equivalents of $3.71 million, with no debt
- Net assets of $7.71 million, up from $6.97 million in FY25
- Total cash receipts for the period of $10.2 million, comprising approximately $4.6 million in customer receipts, $875k from the R&D tax rebate, $660k from the CRC-P grant for syphilis test development, and approximately $4.0 million from capital raised during the period net of transaction costs
The EBITDA loss trajectory also continued to improve, from approximately $(4.5) million in FY24 to approximately $(3.4) million in FY25 and approximately $(2.1) million in FY26, reflecting a clear directional trend toward breakeven as the revenue base expands.
The presentation outlined five FY27 strategic priorities:
- Successfully complete development and launch the active syphilis and liver ALT products, while completing feasibility on additional pipeline products
- Expand partnership activity globally, adding more OEM development partners and identifying commercial partners for Atomo products in the US and other markets
- Increase manufacturing capacity, capabilities, and efficiency to reduce costs and improve operating leverage
- Execute commercial expansion across HIV, pregnancy products, and planned launches for active syphilis, liver ALT, and other Atomo products
- Build a growing, diversified revenue base to fund innovation and compound enterprise value over the long term
Don’t Miss the Next Healthcare Breakout
Big News Blast delivers FREE breaking ASX healthcare news directly to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors already staying ahead of the market. Click the “Free Alerts” button at StockWire X to get the next market-moving announcement the moment it drops.