Most investors watching the artificial intelligence boom keep their eyes fixed on the obvious places: chip designers, data centre operators, the handful of megacap technology names that dominate the headlines. Fewer notice that the same boom is quietly steering foreign exchange markets thousands of kilometres away, in one of Asia’s most important trading hubs.
As of late September 2026, Singapore sits at an unusual crossroads. A surge in AI-linked manufacturing is running headlong into core inflation that refuses to cool, and the collision has set up a monetary policy decision due in mid-October that will shape the Singapore dollar’s path into next year.
Here is the framework you need to understand how Singapore runs its economy without a traditional interest rate, and how the coming decision could reshape your Asian currency exposure over the months ahead. Grasp this system and you will read the central bank’s next move before it happens.
Decoding the dual catalysts driving the October policy environment
The abstract story of a global AI boom becomes very concrete when you look at what came out of Singapore’s factories in August. Manufacturing output jumped 15.4% year-on-year, a sharp acceleration from a downwardly revised 6.9% annual gain in July, according to figures released by the Economic Development Board on 28 September 2026.
The gains were broad-based, with every manufacturing cluster except chemicals recording growth. Electronics and precision engineering led the charge, both tied directly to global demand for AI servers and accelerators. The Straits Times attributed the surge explicitly to sustained AI-related investment.
Singapore export growth in August 2026 added a further dimension to the manufacturing story: non-oil domestic exports surged 46.2% year-on-year, the fastest pace since October 1988, with electronics alone up 131.8% as AI infrastructure demand translated directly into shipped product volumes.
That is the growth side of the ledger. The price side tells a more uncomfortable story.
Data from the joint Consumer Price Developments release by the Monetary Authority of Singapore (MAS) and the Ministry of Trade and Industry on 23 September 2026 showed MAS Core Inflation creeping up to 2.2% year-on-year in August, from 2.0% in July. Headline CPI-All Items rose to 2.3%, up from 2.2%. The core pickup was driven by services, retail goods and food, categories tied more to domestic demand and wages than to imported costs.
| Indicator (YoY) | August 2026 | July 2026 | Direction |
|---|---|---|---|
| Manufacturing output | 15.4% | 6.9% (revised) | Accelerating |
| MAS Core Inflation | 2.2% | 2.0% | Rising |
| Headline CPI-All Items | 2.3% | 2.2% | Rising |
For policymakers, this is a balancing act. They need to cool domestic services and food inflation without choking off a manufacturing upcycle that has only just begun. For you, the combination of runaway AI-driven output and firming core prices is exactly why this market deserves closer monitoring than usual across your Asian currency allocations.
Assessing the sustainability of the AI manufacturing cycle
The obvious question is whether this boom lasts. History counsels caution.
The current upswing invites comparison with the 2017-2018 memory cycle and the 2020-2021 pandemic chip shortage, both of which delivered rapid gains before correcting as capacity caught up and demand normalised.
AI server and accelerator demand is viewed by many economists as more structurally supported than those earlier episodes, but it still hinges on corporate capital spending decisions that could reverse if firms overbuild. MAS and market economists generally assume some normalisation ahead, which is precisely why authorities are wary of over-reacting to a single strong print with aggressive tightening.
When big ASX news breaks, our subscribers know first
How the S$NEER framework actually operates
Here is the fact that consistently catches global investors off guard: Singapore does not set a policy interest rate to run its monetary policy. If you are waiting for a rate announcement in the style of the US Federal Reserve, you will wait forever.
Instead, MAS manages the Singapore dollar’s nominal effective exchange rate, known as the S$NEER. This is the value of the currency measured against a trade-weighted basket of the currencies of Singapore’s major trading partners, kept within an undisclosed policy band. The precise boundaries of that band are never made public.
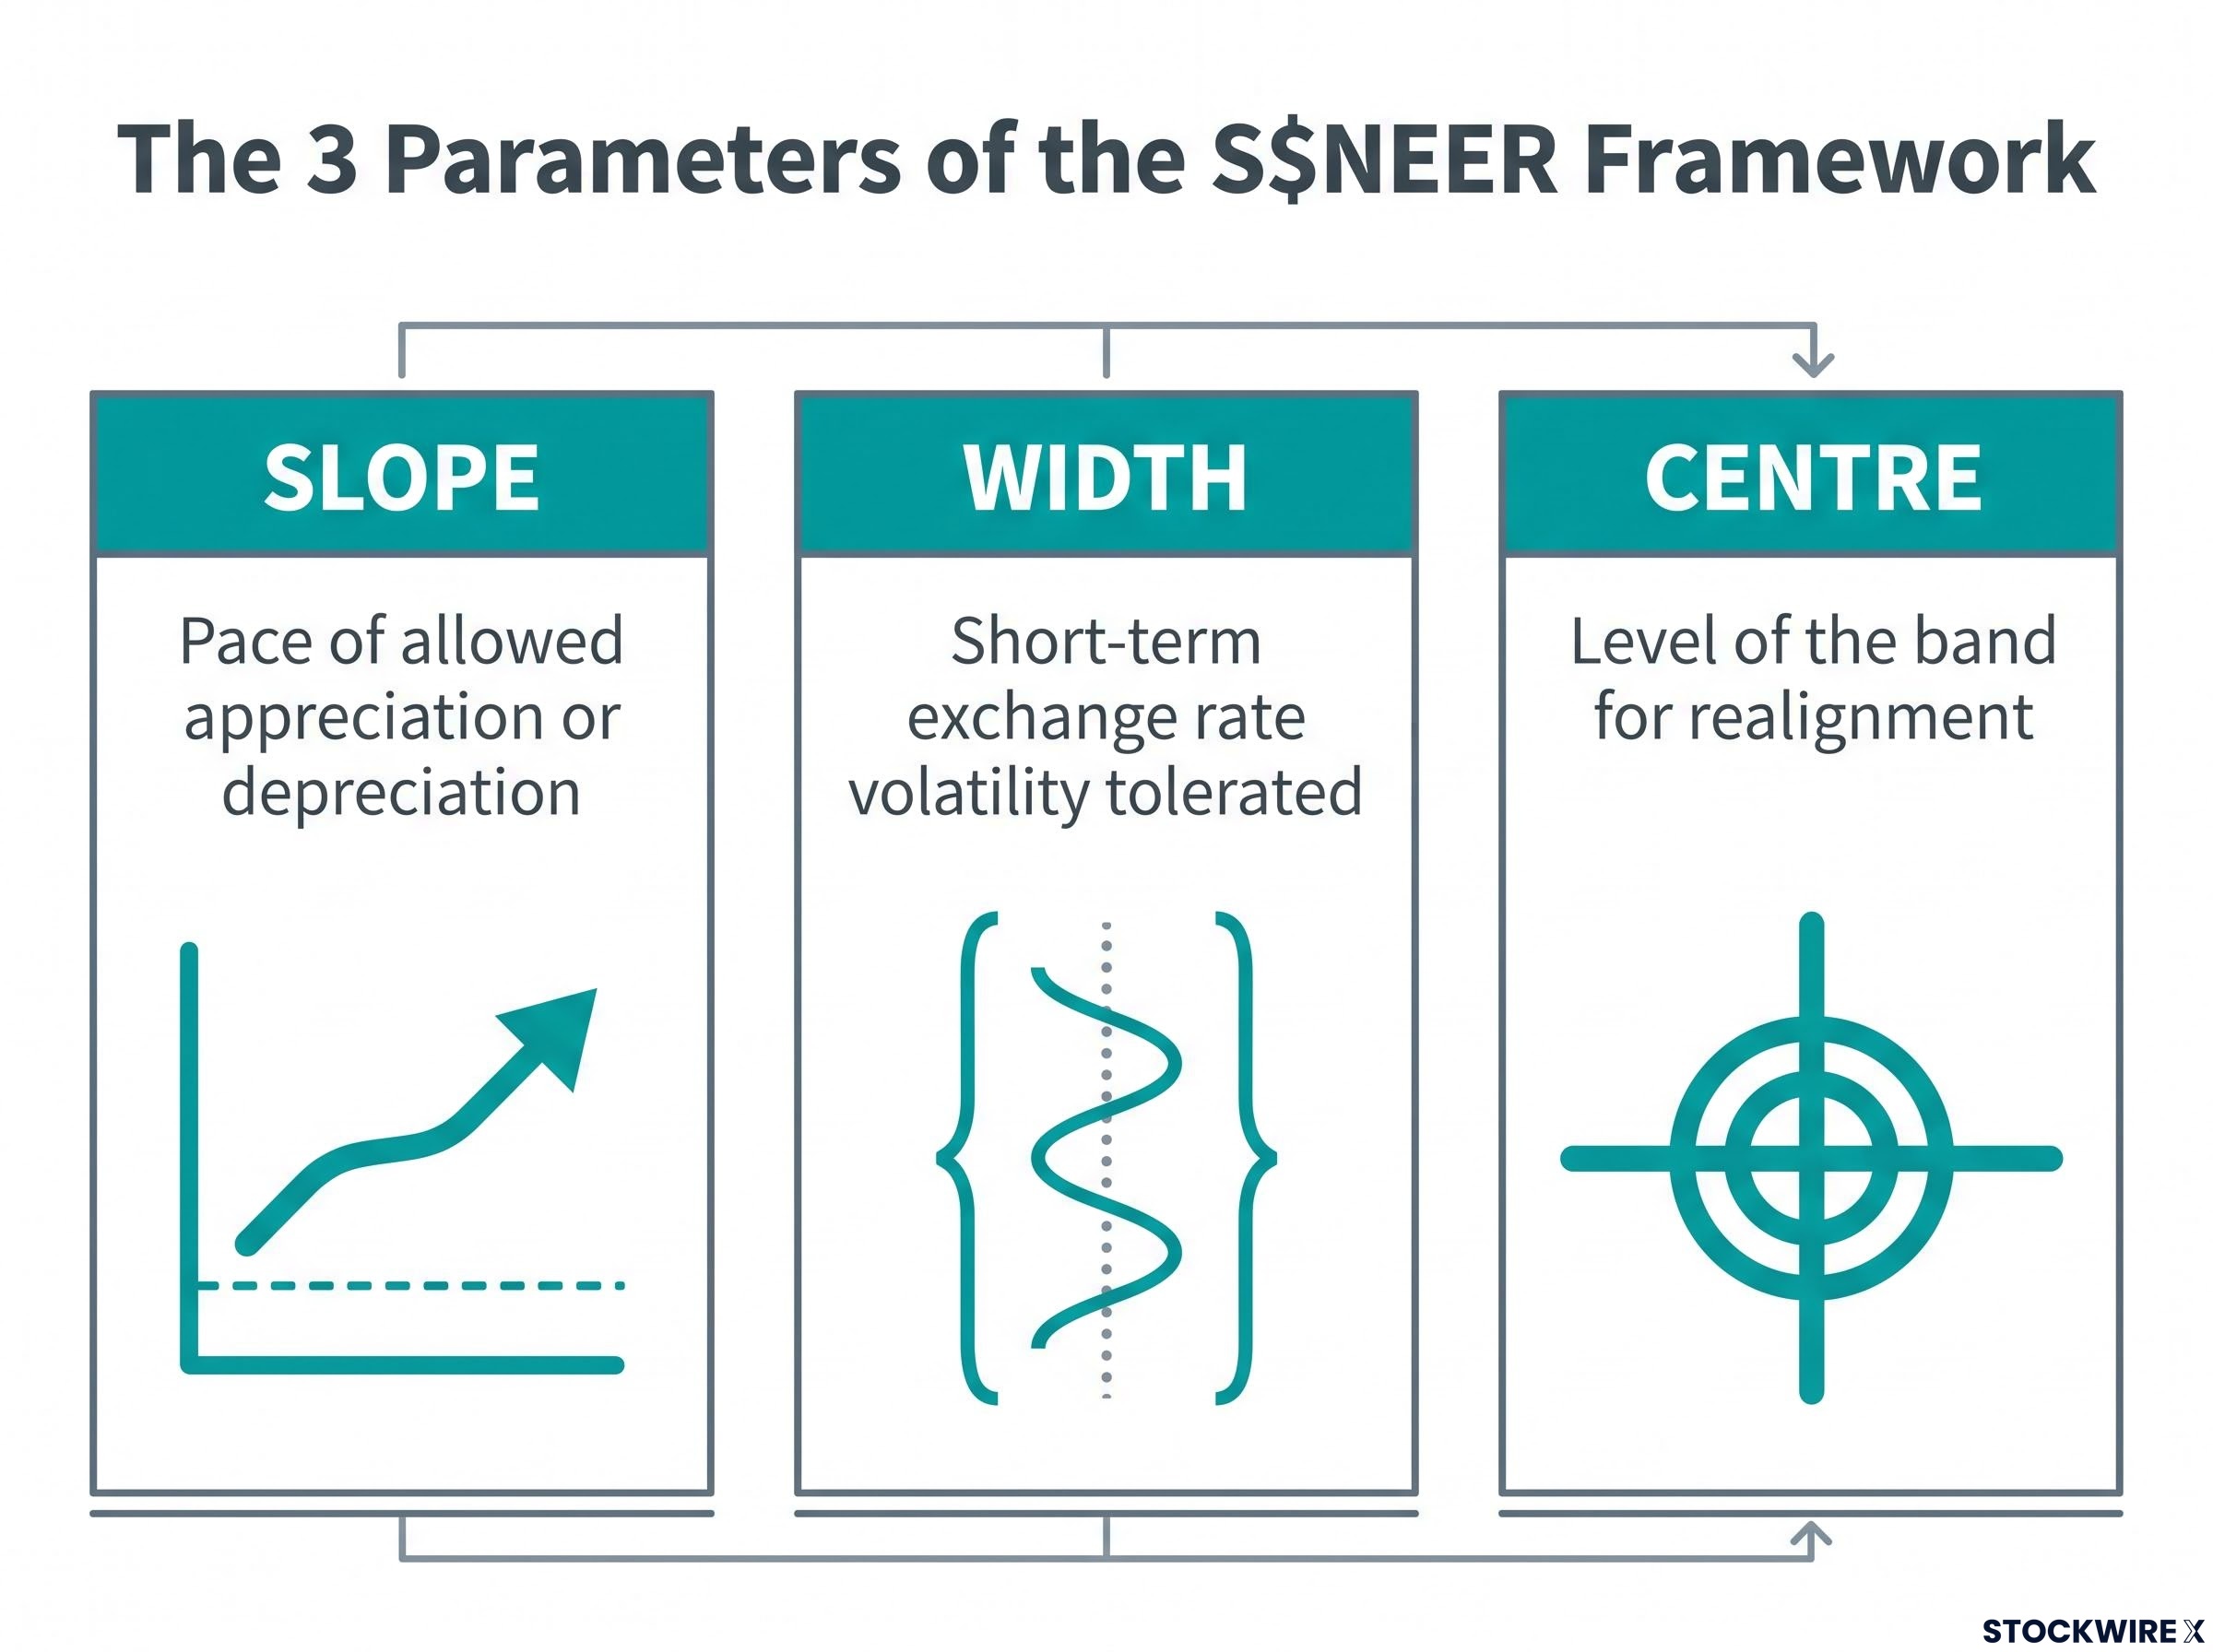
MAS steers the currency through three parameters, and knowing them lets you decode almost any policy signal the central bank sends.
- Slope: determines the pace of allowed appreciation or depreciation over time. A steeper slope means faster appreciation.
- Width: governs how much short-term exchange rate volatility is tolerated within the band.
- Centre: the level of the band, which can be re-centred higher or lower when a larger realignment is needed.
Why build policy around the exchange rate rather than a rate of interest? The answer lies in Singapore’s structure. This is an extremely open economy where imports, including energy and food, feed straight into domestic prices, and where capital moves freely across borders.
Singapore is not the only economy that has built its monetary framework around exchange rate as monetary policy: the Swiss National Bank similarly manages the franc against a basket of peers and has demonstrated, including through its abrupt 2015 floor removal, that even a credible currency commitment will be abandoned before the balance sheet grows without limit.
In that setting, domestic interest rates are largely determined by global markets rather than by anything MAS decides at home. Steering the currency’s value against a basket of trading-partner currencies is therefore a more direct lever on imported inflation than a short-term interest rate could ever be. A gradual appreciation bias dampens imported price pressures when global costs run hot.
The framework is not without trade-offs. It gives MAS less direct control over domestic credit cycles, so the central bank leans on macroprudential and regulatory tools to manage asset-price and leverage risks. Communication is harder too, because the band is undisclosed and the S$NEER is not something households can observe directly.
Understanding this mechanism hands you a distinct edge. While other investors sit waiting for a standard rate decision that will never come, you can read the slope, width and centre for what they actually signal about the real return on your Singapore dollar holdings.
Expectations for the mid-October policy calibration
Theory meets reality in mid-October, when the MAS Monetary Policy Committee is due to decide. No outcome has been confirmed, so everything from here is expectations-based, but the direction of the debate is becoming clearer.
OCBC’s Christopher Wong anticipates that MAS will modestly tighten policy by slightly steepening the S$NEER slope at the meeting. The reasoning rests on the pairing that runs through this whole story: persistent underlying inflation alongside resilient manufacturing activity, according to Wong’s view as reported by FXStreet.
A steeper slope is a subtle move. It represents a mild tightening, a gradual appreciation bias, rather than the blunter step of re-centring the entire band higher. The distinction matters, because a slope adjustment fine-tunes the pace of currency strength while a re-centring signals a far larger structural shift.
Analysts frame any prospective tightening via a steeper S$NEER slope as a calibration exercise rather than a binary policy choice or a blunt instrument response to inflation.
The internal tension is real. A stronger currency in effective terms could erode the price competitiveness of exporters in electronics, precision engineering and transport engineering, the very clusters now driving the recovery. MAS must weigh inflation control against the risk of denting a nascent upcycle.
For you, a steeper appreciation path signals that authorities feel comfortable enough with underlying growth to prioritise inflation control. That kind of stance typically acts as a fundamental floor under a currency’s valuation, which is exactly the shift worth watching for before the official announcement lands.
Translating central bank moves into Singapore Dollar performance
So what does all this mean for the currency itself? The expected October tightening feeds directly into near-term Singapore dollar strength, particularly against higher-beta Asian peers that lack the same policy support.
The SGD has already shown that resilience. USD/SGD was quoted at roughly 1.2777-1.2780 in late September 2026, with the Singapore dollar holding firm even as the broader regional FX environment softened, according to OCBC analysis reported by FXStreet.
Asian currency vulnerabilities in 2026 are not uniform: cumulative regional equity outflows of $134 billion through mid-year have hit structurally exposed currencies like the Indian rupee, Philippine peso, and Thai baht far harder than the Singapore dollar, illustrating exactly why the SGD’s policy framework gives it a different risk profile from higher-beta peers.
Technical signals point toward a pause rather than a fresh leg higher. Daily chart momentum for USD/SGD remains bullish, but tentative signs of deceleration are emerging, with the RSI trending lower and pointing to a likely period of consolidation ahead.
Domestic policy only carries the currency so far, though. Near-term direction is expected to hinge primarily on US interest rate movements and the Chinese renminbi, both of which sit largely outside Singapore’s control. If the Fed keeps rates high or the dollar stays strong, the S$NEER appreciates less for any given nominal move, complicating MAS’s calibration.
The clearest way to hold the risks in view is to lay them out plainly. Three scenarios could weaken the currency even with supportive local policy:
- Persistent US dollar strength or a global risk-off swing, which could push USD/SGD higher regardless of the effective S$NEER staying within its band.
- Weaker regional and Chinese growth, spilling over via trade, tourism and financial channels, and potentially forcing MAS to avoid overly steep appreciation.
- Cyclical AI demand fading, which could prompt MAS to flatten the slope again if the manufacturing surge and inflation uptick prove temporary.
The takeaway for your positioning is this. Domestic policy provides a genuine protective buffer for the Singapore dollar, but your foreign exchange exposure still needs active hedging against broader US dollar strength and the external forces MAS cannot offset.
Positioning your portfolio for the next phase of Asian currency markets
Three forces now define Singapore’s monetary moment: an AI-fuelled manufacturing surge, core inflation that has firmed to 2.2%, and an expected exchange rate adjustment in mid-October. They connect into a single story, one where a small, open economy uses its currency, not an interest rate, to manage the pressures the global AI boom is generating.
The single indicator worth watching is the S$NEER slope. A steeper slope confirms a modest tightening bias and, by extension, a stronger baseline for the Singapore dollar heading into late 2026. It is the clearest read you will get on regional currency stability.
Now is the moment to review your Asian currency hedges against that potentially firmer baseline, while keeping the external risks, US dollar strength and Chinese growth, firmly in the frame.
For investors wanting to map the specific transmission channels in detail, our full explainer on Fed and oil shocks hitting Asian FX covers how the hawkish repricing toward a 4.2% year-end US rate and the Strait of Hormuz tanker seizure are converging to threaten the Asia Dollar Index rebound.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
Forward-looking references to the October policy outcome are expectations-based and subject to change based on market developments and central bank decisions.