Overnight, the odds of a Bank of Japan rate hike this month fell by half. Market pricing that had implied roughly a 60% chance of an October move on Monday collapsed to about 30% by 28 September 2026, and it was not a data release that did it. It was a document.
The tension here is sharp. The BoJ raised its policy rate to 1.25% on 18 September 2026 by a 7-2 vote, signalled it intends to keep tightening, and then watched traders immediately conclude the next move is three months out rather than four weeks away.
Then Tokyo’s September consumer price index landed on 1 October at 2.4% year-on-year, well above the 1.8% consensus and above the BoJ’s 2% target. That print arrived after the repricing, which raises the live question: does the reset still hold?
Here is what the current pricing distribution, the incoming data, and the named-economist consensus mean for anyone tracking the BoJ rate hike timeline into the 30 October decision. By the end, you will know where the odds actually sit, what would move them, and what a quarterly hiking cadence implies for positioning.
How the September meeting summary moved the market
The sequence matters more than the outcome. On 18 September, the BoJ lifted its rate to 1.25% on a 7-2 vote. That decision was already priced and already digested. The repricing came later, and it came from how the central bank explained itself.
At 23:50 GMT on Wednesday, the BoJ published the summary of opinions from that meeting. Traders read the central bank’s stated conditions for the next move, specifically that further hikes depend on the economic outlook holding, as pointing to a longer assessment window than they had assumed. The reinterpretation was swift.
The sequence matters because the September meeting was itself uncontroversial; it was the forward guidance, specifically the language around conditions for the next move, that did the real work of repricing October expectations from 60% to 30% in the span of a week.
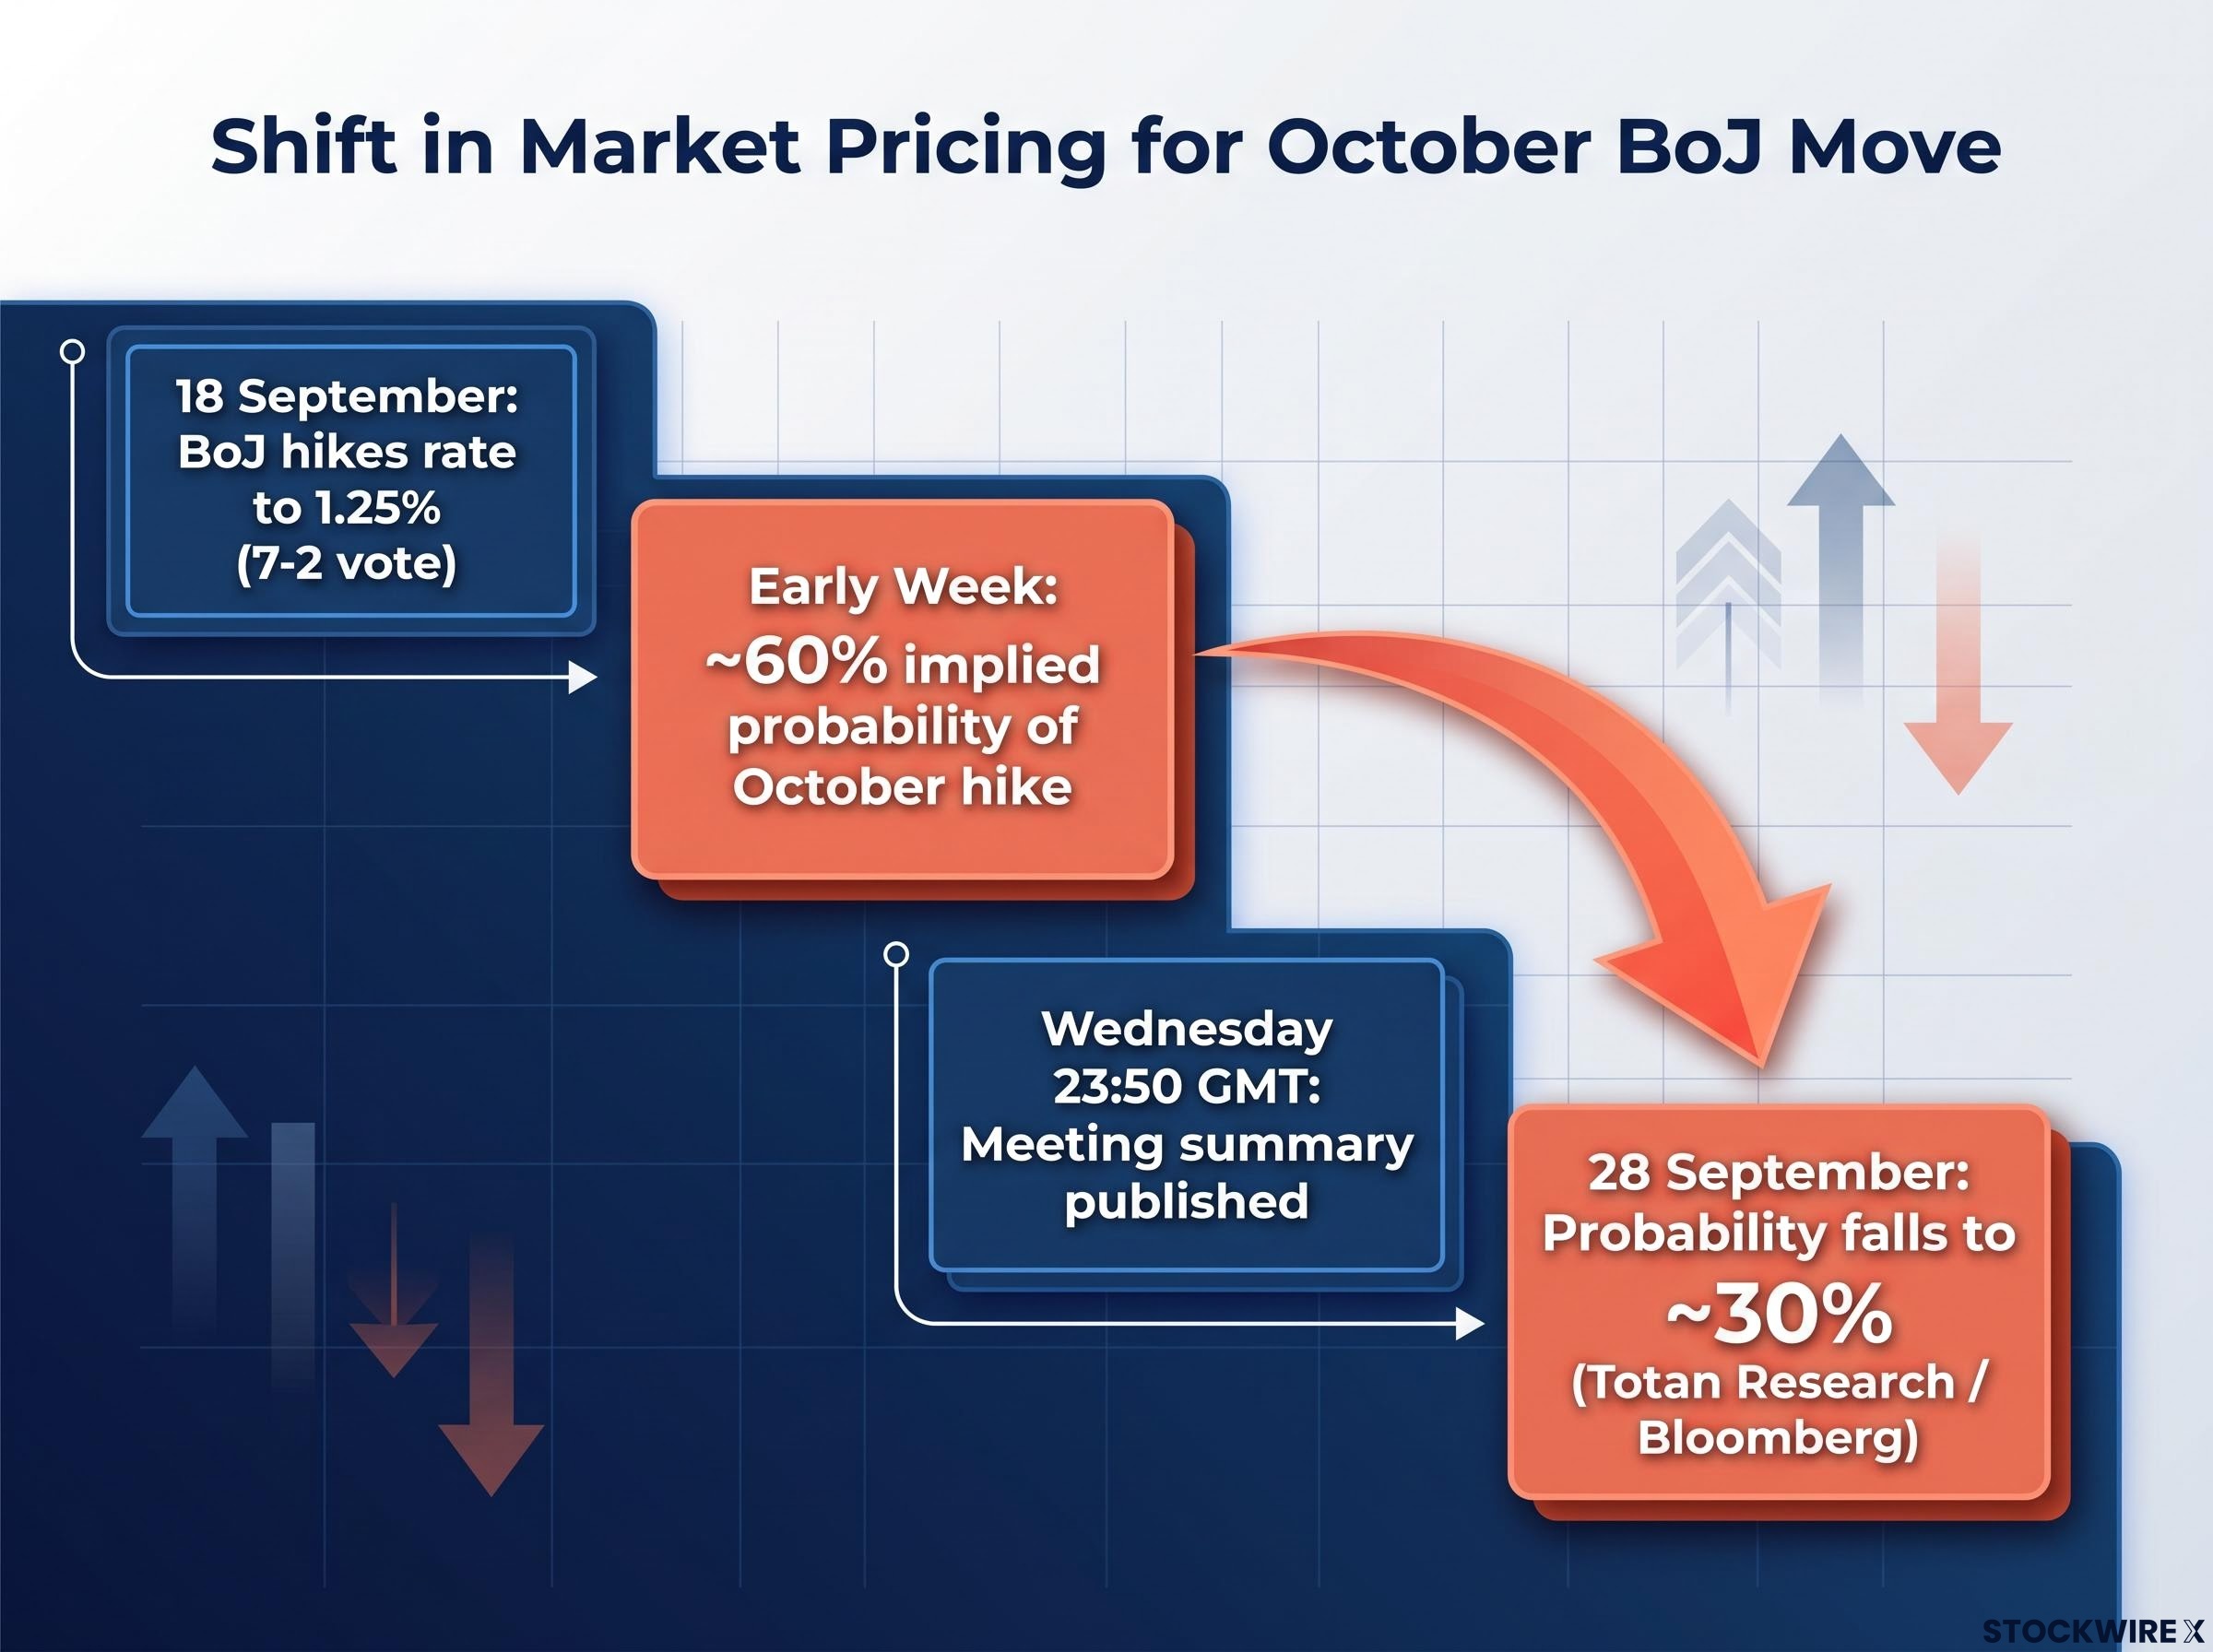
By the close on 28 September, overnight interest-rate swap pricing calculated by Totan Research and cited by Nikkei put the implied probability of an October hike at roughly 30%, down from around 60% at the start of the week.
“The market sees a more than 30 per cent chance of an additional 0.25 percentage point increase next month.” Totan Research swap-market calculation, cited by Nikkei, as of 28 September 2026
Bloomberg’s overnight swaps data told the same story, putting the October probability at 30% as of Friday afternoon. Two independent readings, one number.
The repricing broke down into three clean stages:
- 18 September: The rate decision itself, a 1.25% hike on a 7-2 vote, already expected.
- Wednesday: The meeting summary publication at 23:50 GMT, which recalibrated the assessment window.
- 28 September: Market pricing stabilising around a 30% October probability.
Here is the read that matters. The thing that halved October odds was the BoJ’s own language, not fresh economic data. That tells you communication is currently the dominant input into Japanese rate expectations, which means any October surprise would need to clear two hurdles, not one: a data threshold and a communication threshold.
That distinction is not academic. It sets up precisely what happened next, because the first serious piece of post-summary data arrived three days later.
When big ASX news breaks, our subscribers know first
What the Tokyo CPI surprise means for October odds
2.4%. That is the number that reopened the debate.
Tokyo Core CPI (the measure that strips out fresh food) rose 2.4% year-on-year in September 2026, released on 1 October. Consensus had sat at 1.8%, the same as the August reading. A 60 basis-point beat on a leading inflation indicator is not noise.
Tokyo’s inflation data matters because it runs ahead of the national figures by roughly three weeks, making it the forward signal BoJ watchers lean on when reading the next Outlook Report and policy deliberations. When Tokyo moves, the national print usually follows.
The structural context sharpens it further. This was the first time in nine months, since December 2025, that all three key Tokyo CPI measures were expected to clear the BoJ’s 2% target. The actual result also matched the top of the pre-release forecast range, which had spanned 2.1% to 2.4%.
| Indicator | August 2026 (Prior) | September 2026 (Actual) | Consensus Forecast |
|---|---|---|---|
| Tokyo Core CPI (ex-fresh food), YoY | 1.8% | 2.4% | 1.8% |
The timing is the point. This print landed after the market had already settled at 30% for October, which means it is the single most important live data point for anyone with Japanese rate exposure right now. Whether that 30% drifts back toward 50% depends on how the BoJ and its watchers absorb this specific reading in the weeks before 30 October.
The conditions the BoJ has set for an October move
Sources familiar with BoJ thinking, cited by Reuters, describe a high hurdle for an October hike. The thresholds are qualitative rather than numerical, and they fall into three groups:
- Tokyo CPI and related measures clearly and persistently above the 2% target, and above prior expectations.
- Tankan and corporate survey data showing inflation expectations rising and price increases spreading across goods and services.
- External shocks that lift the perceived risk of an inflation overshoot, such as renewed yen weakness or a commodity-price spike.
Yen dynamics deserve their own mention. Persistent currency weakness, amplified by high-profile political commentary, has fed bets on an earlier move, with markets sensing pressure on the BoJ to support the yen more firmly. That sits in direct tension with Governor Kazuo Ueda’s stated preference for gradualism and avoiding market disruption.
Persistent yen weakness has repeatedly tested the yen intervention threshold near 160 per dollar, a level where Ministry of Finance action risk rises sharply and where carry-trade unwind dynamics can amplify BoJ rate expectations faster than any data release.
A 60 basis-point beat on a leading inflation gauge, weeks before a scheduled meeting, is exactly the kind of shock sources describe as capable of clearing that high hurdle. The October-versus-December question is live again.
The wage foundation underpinning the hiking cycle
Strip away the October-versus-December noise and one question remains: why is the BoJ hiking at all? The answer sits in the wage data, and it is the strongest Japan has seen in decades.
Sustainable inflation, the kind the BoJ is willing to tighten against, requires wages to keep pace so that households retain purchasing power and domestic demand holds up. Without that, price rises are just a cost-of-living squeeze. With it, the central bank has a genuine mandate to normalise policy.
Both the monthly and the structural wage data are delivering. Consider the two series the BoJ watches most closely:
- Average Cash Earnings rose 4.7% year-on-year in July 2026, according to TradingEconomics (reported 7 September 2026), well above the 4.0% consensus and the prior reading of roughly 3.9%. The figure is compiled by the Ministry of Health, Labour and Welfare.
- The 2026 shuntō (Japan’s annual spring wage negotiations) produced an average rise of 5.46% year-on-year including base-salary increases, per a Keidanren survey of major firms summarised by Nippon.com on 5 June 2026.
The structural signal The 2026 spring negotiations delivered a 5.46% average wage rise, marking the third consecutive year above 5%. That is the evidence that wage-push inflation is becoming embedded rather than transient.
The link to policy is direct. The BoJ has repeatedly framed its willingness to keep tightening as contingent on wages supporting domestic inflation in a durable way. Both data series suggest that condition is being met.
For investors, wage growth running at 4.7% monthly and 5.46% in structured bargaining means the hiking cycle rests on a credible domestic-demand foundation. The practical consequence is that normalisation is not hostage to any single data print. It is driven by a broad trend that is already well established.
The wage data does not stand alone as a signal of domestic resilience: Japan’s private-sector demand foundation strengthened materially in Q1 2026, with GDP growing at a 2.1% annualised rate driven overwhelmingly by private consumption and business investment rather than government spending, adding a second structural pillar beneath the BoJ’s willingness to keep tightening.
That is why December reads as a pause for confirmation rather than a retreat. The direction of travel toward higher rates holds regardless of how the October question resolves.
The December-base-case framing also needs to account for a structural complication arriving in April 2027: a planned food consumption tax cut that could mechanically suppress headline CPI by up to 1.5 percentage points, making tax-adjusted inflation measures the metrics the BoJ will cite to justify continued tightening after the headline number distorts.
What a quarterly hiking cadence means for rate markets
If the BoJ is moving roughly once a quarter, the near-term fight over October versus December matters less than the shape of the whole path. Named economists are largely aligned on what that path looks like.
Makoto Sakurai, a former BoJ policy board member, frames December as the base case, nested within a September-December-next year quarterly rhythm. Kazuo Momma, a former BoJ executive director, agrees the basic pace will likely be every three months but puts the probability of back-to-back meetings, meaning an October move, at around 20-30%.
The survey data triangulates with the named voices. A Reuters poll in July 2026 found 86% of economists expected a hike by end-December. Among those naming a month, 53% chose December and 35% chose October.
| Analyst / Source | Base Case Timing | Probability Assigned to October |
|---|---|---|
| Makoto Sakurai (ex-BoJ board) | December | October only on a very large inflation forecast revision |
| Kazuo Momma (ex-BoJ executive director) | December / quarterly pace | 20-30% (consecutive meetings) |
| Reuters economist poll (July 2026) | December (53% of those naming a month) | 35% of those naming a month |
For an investor building a view on Japanese rates, that 53/35 split tells you December is the trade to price. But the Tokyo CPI result just handed the 35% October camp a data argument it did not have a week ago.
What could delay or derail the December base case
The December consensus is not bulletproof. Several factors could push the next move later, or reshape the path entirely.
The first is the BoJ’s own caution. Having just raised rates in September, the board wants time to assess the impact before moving again, which argues against haste.
The second is global uncertainty. The BoJ has previously cited concerns about global growth and U.S. trade tariffs when weighing the pace of tightening. For broader context, futures markets at the time of reporting assigned roughly one-in-three odds to a U.S. Federal Reserve rate hike on 28 October, a reminder that Japanese rate markets do not move in isolation.
The third works the other way. If the Tokyo CPI strength flows through to the October Outlook Report and triggers a large upward revision to inflation forecasts, Sakurai’s stated October condition would be met, collapsing the December consensus back toward October.
What the data now says heading into October 30
Pull the threads together and the picture is cleaner than the back-and-forth suggests. The meeting summary pushed expectations to December. The 2.4% Tokyo CPI reading on 1 October arrived with enough force to reopen October. And the wage data confirms the hiking impulse is structurally intact underneath both.
What tips the balance before 30 October comes down to a short list of releases and documents. Here is the watch list, in order of weight:
- The October Outlook Report. This is the key document for inflation forecast revisions, and Sakurai has explicitly named it as the trigger. A very large upward revision is what converts October from tail risk to genuine option.
- Tankan and corporate survey data. These show whether price expectations are broadening across firms, one of the BoJ’s stated conditions for an October move.
- Yen dynamics and external shocks. Renewed currency weakness or a commodity spike would raise the overshoot risk the BoJ watches most nervously.
Sakurai’s framing sets the bar plainly: if the upward revision to price forecasts is “very large,” October becomes a real option rather than a tail risk.
So the mental model is straightforward. December certainty looks like the BoJ confirming its path on schedule after a confidence-building quarter. An October hike would require the Outlook Report, corporate surveys, or the yen to deliver a clear overshoot signal in the next few weeks.
The read you should take is that the timeline is genuinely binary right now. December is the base case, October is the live tail risk, and the October Outlook Report is the document most likely to decide which one plays out.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. These statements are speculative and subject to change based on market developments and central bank decisions.
December is the map, but the CPI data just added a fork in the road
The BoJ’s direction is not in question. A quarterly cadence, supported by named economists, survey data, and the central bank’s own signalling, points to December as the higher-probability next move. That part of the picture is stable.
What changed is the data environment. The 2.4% Tokyo CPI print on 1 October is a different input from the one that drove the post-summary repricing to 30%, and it hands the October camp an argument it lacked a week earlier. The BoJ’s credibility now rests on responding to data without appearing to chase market pressure, which makes Governor Ueda’s communication between now and 30 October as consequential as the numbers themselves.
For anyone with exposure to the yen, JGB duration, or rate-sensitive equities, the takeaway is this: the BoJ rate hike timeline has become a live two-outcome distribution. December remains the higher-probability event, but the Tokyo CPI result has made October a credible alternative worth pricing.