Approved Article With Interlinks
On 16 September 2026, the Federal Reserve moved the federal funds target range from 3.50%-3.75% to 3.75%-4.00%, and in doing so it separated portfolios built on assumptions from portfolios built on fundamentals.
This was the first rate increase since 2023, delivered under Chair Kevin Warsh, and it came with a warning attached: further hikes are possible if inflation driven by tariffs and AI-related capital spending does not ease. Major benchmark indexes struggled to hold their footing in the immediate aftermath. Two AI-driven stock strategies, named Energy Elite and Fed-Resistant Compounders, offer a real-world lens on what actually survived.
Here is what the September 2026 returns show, not a hypothetical back-test: a concrete checklist of the balance sheet and sector characteristics that held up when borrowing costs rose. After reading, you will know the exact filters that separated the resilient holdings from the ones that buckled, and you will be able to apply the same screen to your own positions.
What the Fed’s first hike in three years actually did to the market
The decision was unanimous. The Federal Open Market Committee voted 12-0 to raise rates by 25 basis points, according to research that remains independently unverified, lifting the target range to 3.75%-4.00%. Alongside the headline move, the Board raised the interest rate on reserve balances to 3.90% and the primary credit rate to 4.00%, both effective 17 September 2026.
Markets did not panic. They recalibrated. That distinction matters, because the difficulty benchmark indexes had holding ground was a repricing to a new regime rather than a reflexive sell-off.
The post-hike equity rebound that followed the September 2026 decision, with the S&P 500 gaining 1.14% and the Nasdaq jumping 1.69% the next session, reinforced the idea that well-telegraphed tightening resolves uncertainty in ways that can briefly override the mechanical cost of higher borrowing.
The Fed’s own language signalled the shift. Earlier statements this year held a patient posture on elevated inflation. The September statement dropped references to “supply shocks from energy” and pivoted toward securing a “timelier return” to the 2% inflation goal. That is a real change in tone, and it tells you the central bank is now more worried about persistence than about being patient.
If you feel uneasy about the near-term picture, the historical record suggests that unease is rational, not reactionary.
In the quarter following the first hike across past cycles, the S&P 500 has historically posted a median decline of approximately 3.9%, with the Russell 2000 falling around 7.2% in the same window. Both figures are drawn from research that has not been independently confirmed.
Short-term pain, in other words, is the statistical baseline. What complicates the picture is the recovery: the S&P 500’s average 12-month gain after a first hike has historically sat near 6.7%, again per unverified research. That means the more consequential question is not whether the market wobbles now. It is which of your holdings survive the near-term pressure intact.
Markets are now watching a handful of forward-looking indicators to judge whether the hike is doing its job:
- Weekly jobless claims: the key indicator of whether tighter monetary policy is beginning to slow hiring and reduce demand for workers.
- Flash Purchasing Managers’ Index (PMI): monthly snapshots of activity across manufacturing and services that show how companies are responding to costlier credit.
- Housing starts and factory output: bellwether data for sectors that rely heavily on capital investment, where sustained rate pressure tends to bite hardest.
When big ASX news breaks, our subscribers know first
Why balance sheets became the deciding factor overnight
Higher benchmark rates do not raise every company’s interest bill at once. They hit hardest where debt is floating, where refinancing is imminent, and where cash reserves are thin.
Consider the mechanism as it actually unfolds. A real estate developer with maturing loans has to refinance at the new, higher rate, and its interest expense climbs. A utility with ageing infrastructure needs recurring external financing for maintenance and expansion, so tighter credit conditions bite directly into margins. An asset-heavy industrial faces the same squeeze.
Now hold that against a firm with more cash than debt. It refinances nothing under duress, funds its own growth internally, and earns a premium valuation precisely because investors are hunting for that kind of safety. The divergence between these two groups did not develop over months. It sharpened the moment rates moved.
That is why balance sheet quality became the deciding filter, and the specific markers AI models screened for are ones you can check yourself.
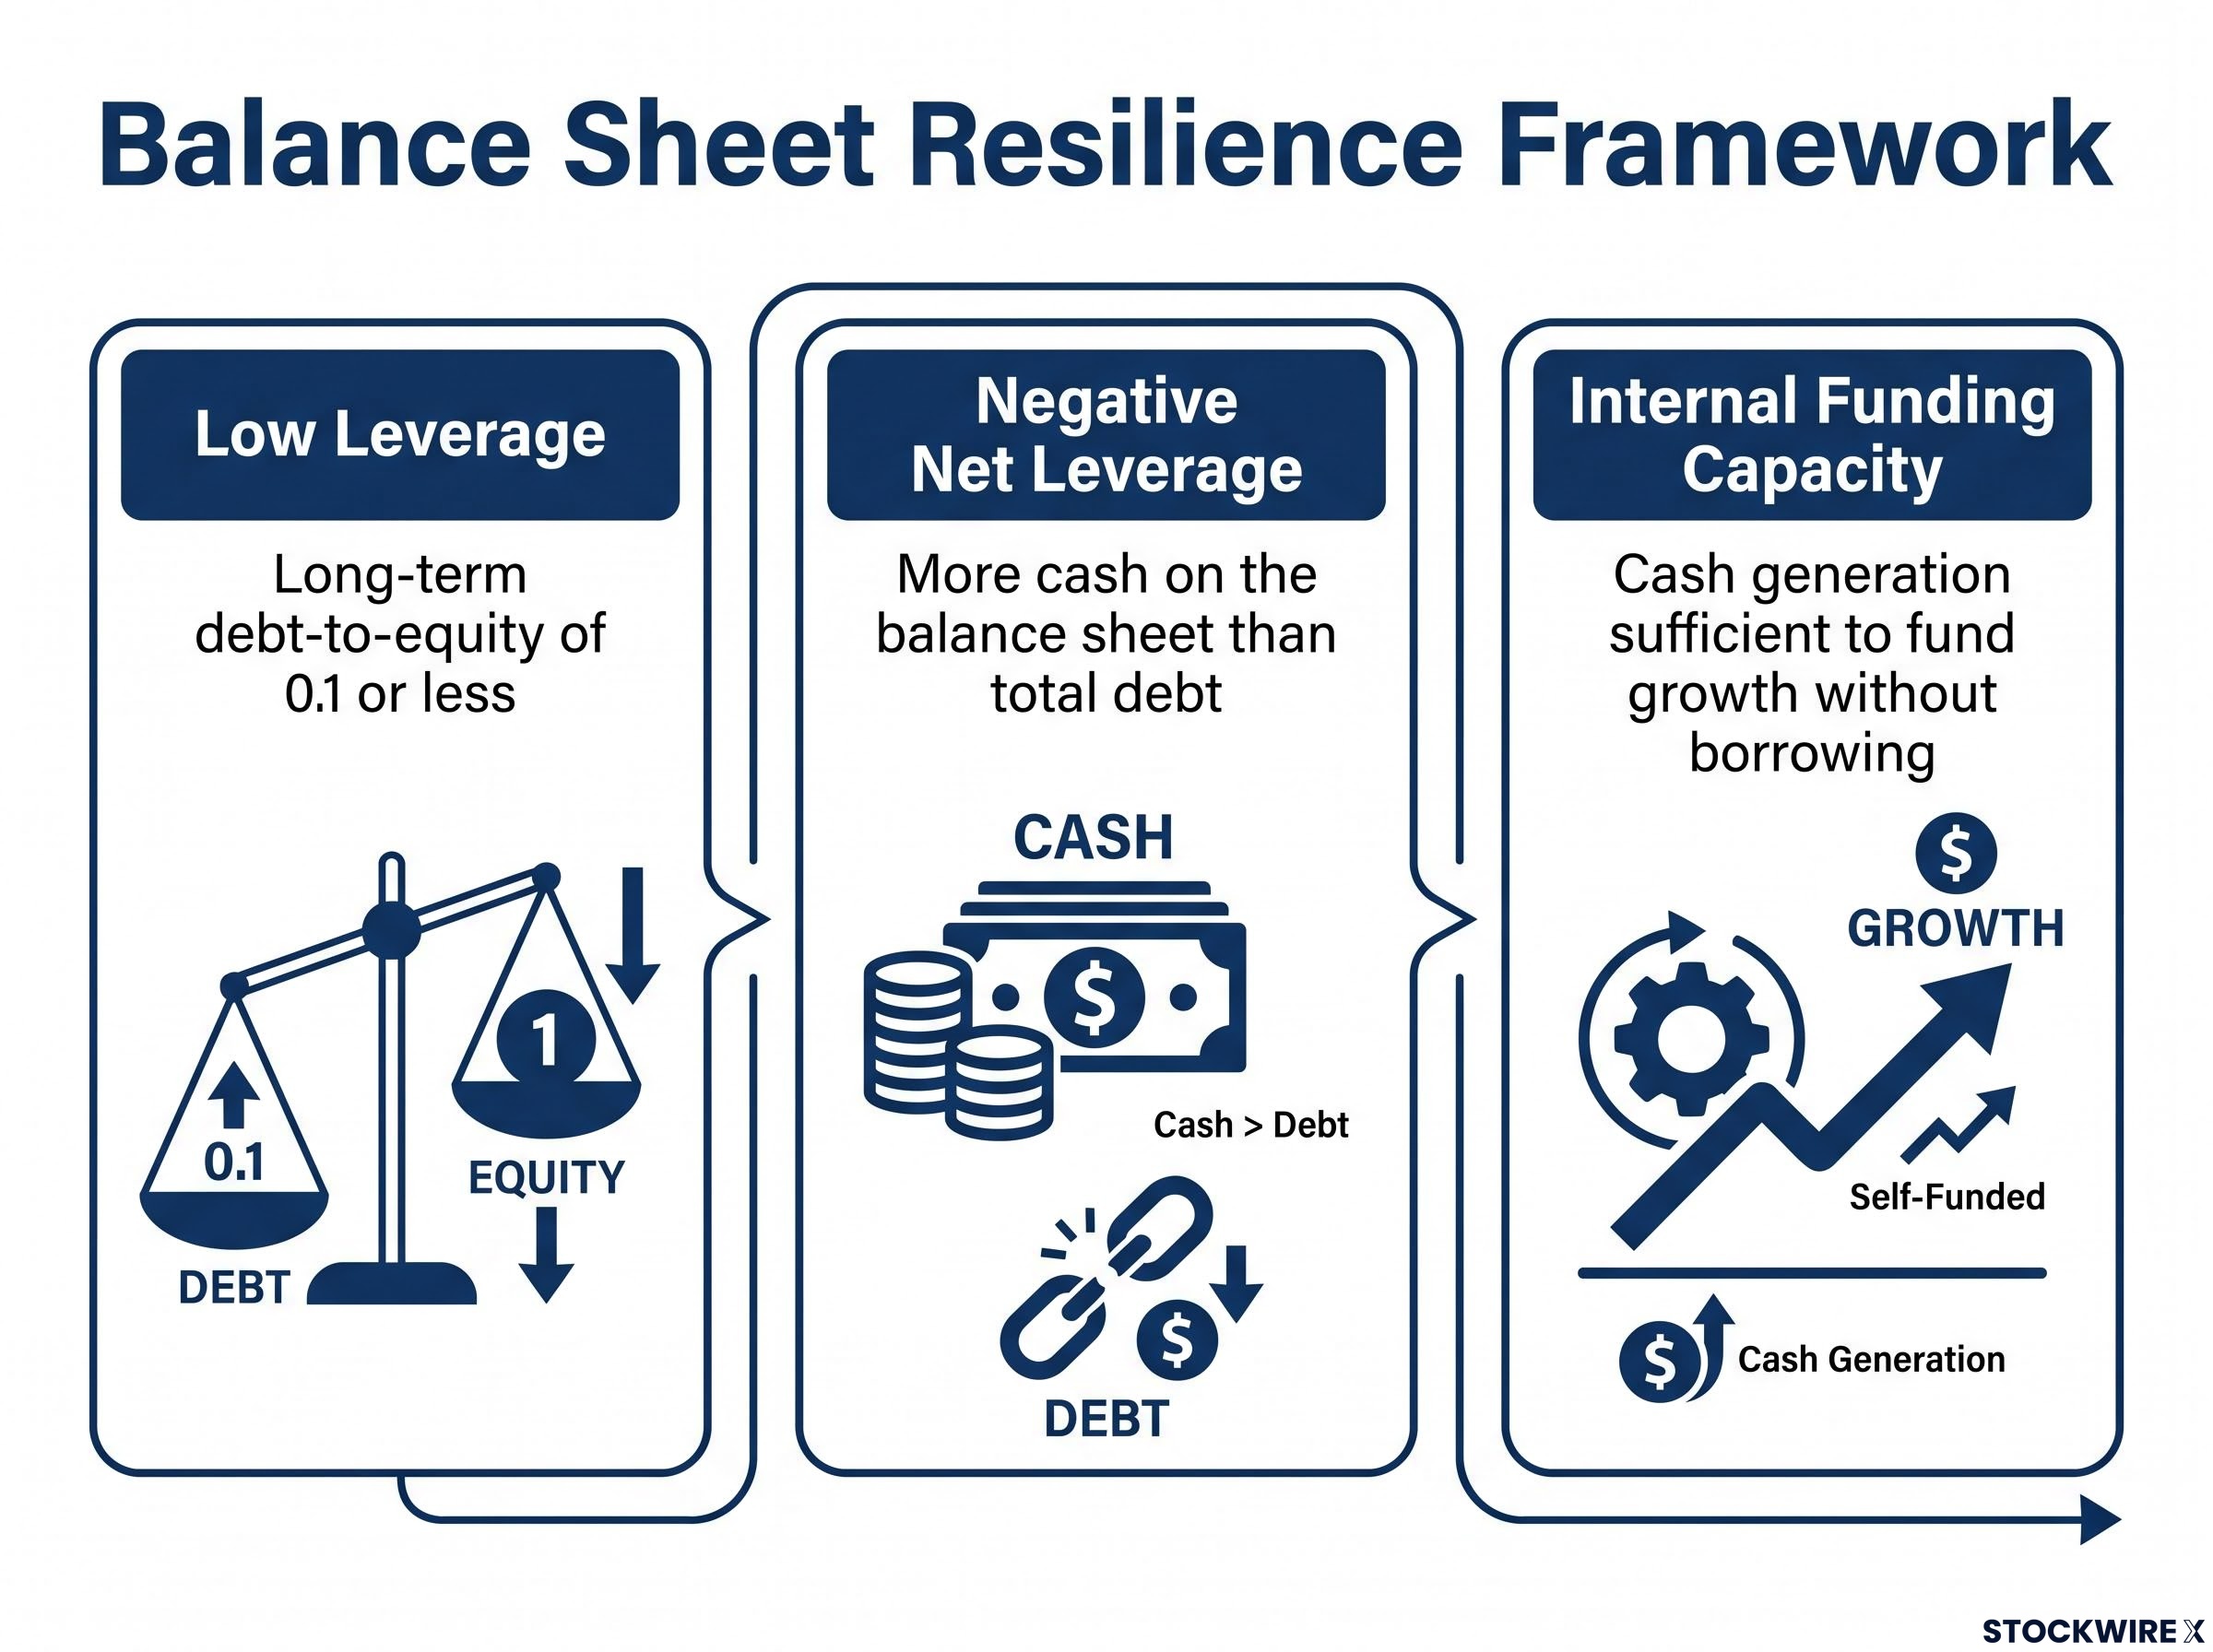
| Resilience characteristic | Measurable threshold or indicator | Risk it mitigates |
|---|---|---|
| Low leverage | Long-term debt-to-equity of 0.1 or less; high interest-coverage ratio | Refinancing stress as rates climb |
| Negative net leverage | More cash on the balance sheet than total debt | Dependence on external financing |
| Internal funding capacity | Cash generation sufficient to fund growth without borrowing | Exposure to rising borrowing costs |
The 0.1 debt-to-equity benchmark, cited by strategists in research that remains unverified, is the number to look for first. Pair it with negative net leverage, which simply means a company holds more cash than debt, and you have the screen that flagged the resilient names.
Cash-to-enterprise-value screening, the methodology Morgan Stanley applied to the entire Russell 1000 using Q1 2026 data, is one operationalised version of the negative net leverage filter described above, and it surfaces names like Veeva Systems, which carries no debt and ranks first on that metric.
Pricing power was the second half of the equation
Low debt keeps a company alive. Pricing power lets it thrive.
A firm that can raise prices without losing sales volume passes higher financing and input costs straight through to customers, protecting or even expanding its margins. That capacity is what separated the compounders that held from the ones that absorbed the compression.
There is a legitimate debate worth noting here. Some cash-rich, mega-cap technology companies are frequently cited as resilient despite higher discount rates, because their internal funding capacity insulates them from borrowing costs almost entirely. The mechanism is the same one you have just walked through: when a company does not need the credit market, the credit market cannot punish it. These are the exact filters that separated the AI-selected compounders’ gains from the broader market’s struggle, and you can run the same check on every position you own.
The two AI strategies that held up, and the numbers behind them
Start with the returns, because they are concrete.
The Fed-Resistant Compounders strategy leaned on three names, each selected for the balance sheet traits described above.
| Company | Ticker | Gain from selection |
|---|---|---|
| Everforth | NYSE: EFOR | 87.53% |
| Consensus Cloud Solutions | NASDAQGS: CCSI | 68.31% |
| Nucor | NYSE: NUE | 66.53% |
Each figure is the return from initial AI selection through the September 2026 reporting period. Everforth was identified at roughly 3x forward earnings and anchored by a secured $115 million U.S. Army AI contract, giving it high-margin defence software revenue at a cheap entry point. Nucor was chosen for its conservative financial structure, a buffer against rising rates; subsequent research, which is unverified, points to Q2 2026 net earnings of $1.16 billion, or $5.04 per diluted share (adjusted $4.84), on revenue of $10.4 billion. Consensus Cloud Solutions entered on its recurring cash-flow profile, with unverified research citing Q2 2026 EPS of $1.49 on revenue of $91.36 million and full-year 2026 adjusted EPS guidance of $5.55-$5.95.
Read those gains against a market that struggled to hold ground, and the pattern is clear: the selection logic, not luck, produced the numbers.
When commodity cash flows insulate against rate pressure
Energy behaves differently in a hiking cycle, and the Energy Elite strategy exploited it.
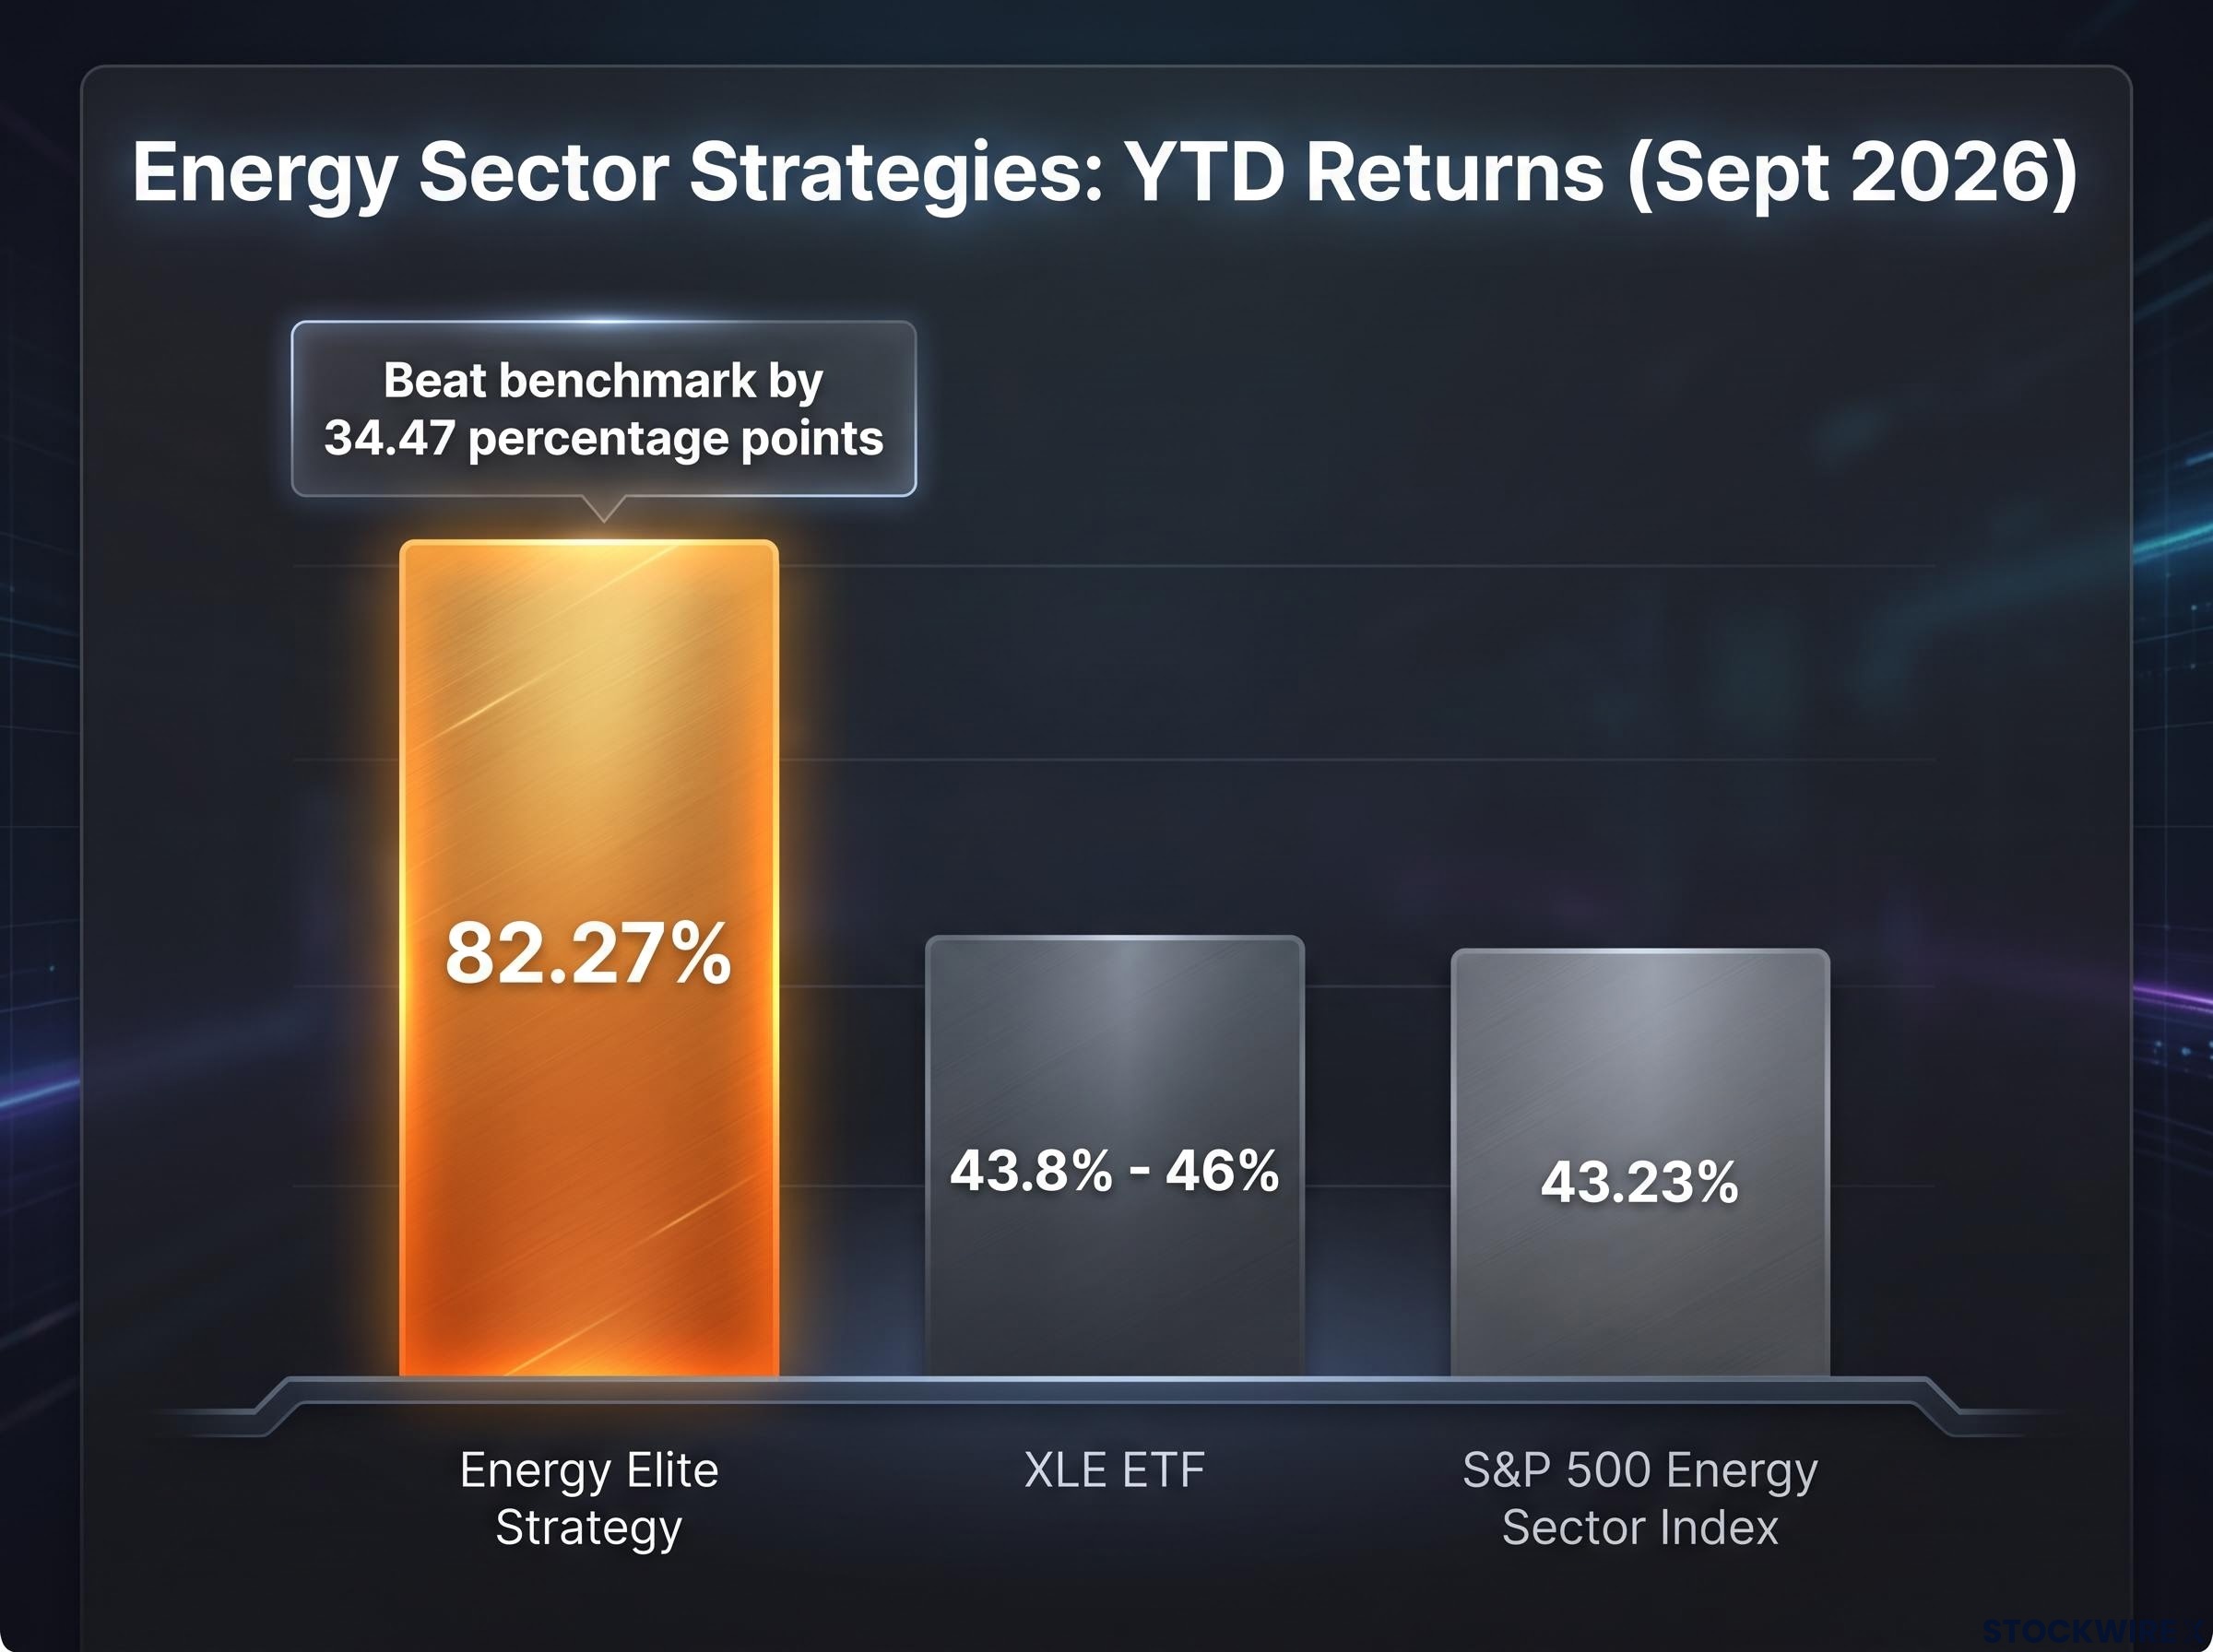
The Energy Elite portfolio delivered a year-to-date return of 82.27% as of the September 2026 reporting period, surpassing its benchmark by 34.47 percentage points.
For context, the Energy Select Sector SPDR ETF (XLE) posted an unverified year-to-date gain of roughly 43.8% to 46% by mid-September 2026, and the S&P 500 Energy Sector Index sat at 43.23%. The gap between the strategy’s 82.27% and the sector ETF’s roughly 44% is the quantitative case that identifying fundamental inflection points beats passive sector exposure. When you assess your own sector allocations, that distinction is the one to weigh.
The four holdings, with returns from initial selection:
- Delek US Holdings (NYSE: DK): 117.43%, selected on refining-margin strength.
- HF Sinclair (NYSE: DINO): 65.72%, driven by favourable margins and share buybacks.
- CVR Energy (NYSE: CVI): 52.48% total, including 26.29% in September 2026 alone, flagged at a PEG ratio of 0.43 on rising Mid-Continent production.
- SM Energy (NYSE: SM): 44.53%, though sources conflict on its consensus estimates and revenue, so treat those secondary figures with caution.
The refining backdrop explains the margins. Crack spreads have stayed elevated as Strait of Hormuz disruption tightened product markets, with unverified Q4 2026 diesel margin forecasts near $50 per barrel in the U.S. and $37 per barrel in Europe. Global net refining capacity additions of 0.71 million bbl/day fall short of estimated demand growth of 1.06 million bbl/day, keeping product markets tight.
Where AI-driven selection breaks down: the risks this environment exposes
Understanding how these strategies fail makes you a sharper user of them, not merely a more cautious one.
- Overfitting and backward-looking signals. AI models learn from historical patterns, and this macro configuration, tariff-driven inflation stacked on an AI capital-spending cycle stacked on rate hikes, is genuinely novel. Patterns that worked in past cycles may simply not apply here.
- Concentration and beta. AI-generated portfolios tend to cluster in large-cap tech and semiconductor names, with an unverified average market beta of roughly 1.6.
Peer-reviewed research on AI trading strategy risks confirms that leading large language models consistently favour high-momentum, high-beta stocks and frequently violate explicit beta constraints when generating portfolio recommendations, a structural tendency that compounds concentration risk in novel macro environments like the current rate cycle.
- Opacity and explainability. AI systems often cannot articulate why a stock was chosen, which complicates human oversight exactly when it is needed most, during rapid drawdowns.
For investors wanting to understand the systemic dimension of this concentration problem in more depth, our full explainer on AI model convergence risk examines how shared architectures and overlapping training data can produce correlated exits that amplify tail moves at exactly the moment diversification is supposed to provide cover.
- Demand destruction and hidden leverage. A slowdown from higher-for-longer rates could erode refined-product demand, and refiners that over-borrowed during this high-margin window face compounding refinancing stress if crack spreads normalise while rates stay elevated. New mega-project capacity is expected to integrate in late 2026 and 2027, pressuring spreads downward.
A market beta of roughly 1.6 means an AI-concentrated portfolio can swing around 60% more than the broader market.
Hold that number alongside the headline returns. If the post-hike pressure accelerates into a correction, a 1.6 beta portfolio could fall roughly 60% harder than the index. That is the figure the strategy’s marketing will not put next to the 82.27%.
What actually holds up when rates stay high: a framework for your next move
The September 2026 data confirmed which characteristics carry a holding through a rate-elevated environment. These are the filters to apply to anything you are reconsidering right now:
- Low leverage: check long-term debt-to-equity is 0.1 or below, found in the company’s balance sheet.
- Pricing power: look for sustained or expanding profit margins across recent quarters in the income statement.
- Commodity-linked or internally funded cash flow: confirm either negative net leverage (more cash than debt) or cash generation that funds growth without borrowing.
Then keep a watching brief on whether the rate environment deepens or stabilises:
- Weekly jobless claims: the first sign the labour market is cooling.
- Flash PMI: how businesses are coping with tighter conditions.
- Housing starts and factory output: the strain gauge for capital-intensive sectors.
Here is the tension to hold. The AI strategies delivered real returns because they identified fundamentals early, and the S&P 500’s historical 6.7% average 12-month post-hike gain (unverified) suggests recovery tends to follow the initial pain. But the same beta and overfitting risks mean uncritically adopting AI-selection outputs is its own vulnerability. The filters are the value. The blind trust is the danger.
For investors who want to extend these filters into a full portfolio construction approach, our comprehensive walkthrough of portfolio resilience frameworks covers how to diversify across economic regimes rather than asset-class labels, including a three-tier adaptive structure that applies rules-based rebalancing through inflation and rate cycles.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors. Several figures cited are drawn from research that has not been independently verified and should be treated accordingly.