The S&P/ASX 200 closed at 9,153.20 on Wednesday, its best finish in about 11 weeks. On the same day, the Australian Bureau of Statistics (ABS) reported the largest quarterly fall in housing lending since its series began in 2002.
Both facts are true. They point in opposite directions.
The index has climbed roughly 540 points from its early-October low, yet the domestic data behind bank earnings, property turnover and retail spending keeps weakening. If you judge the economy by the index level alone, you could take a narrow, catalyst-driven rally for broad recovery.
Here is what is pushing the ASX 200 rally higher, which data is flashing caution, and the signals to watch from Thursday 12 November through the holiday retail period.
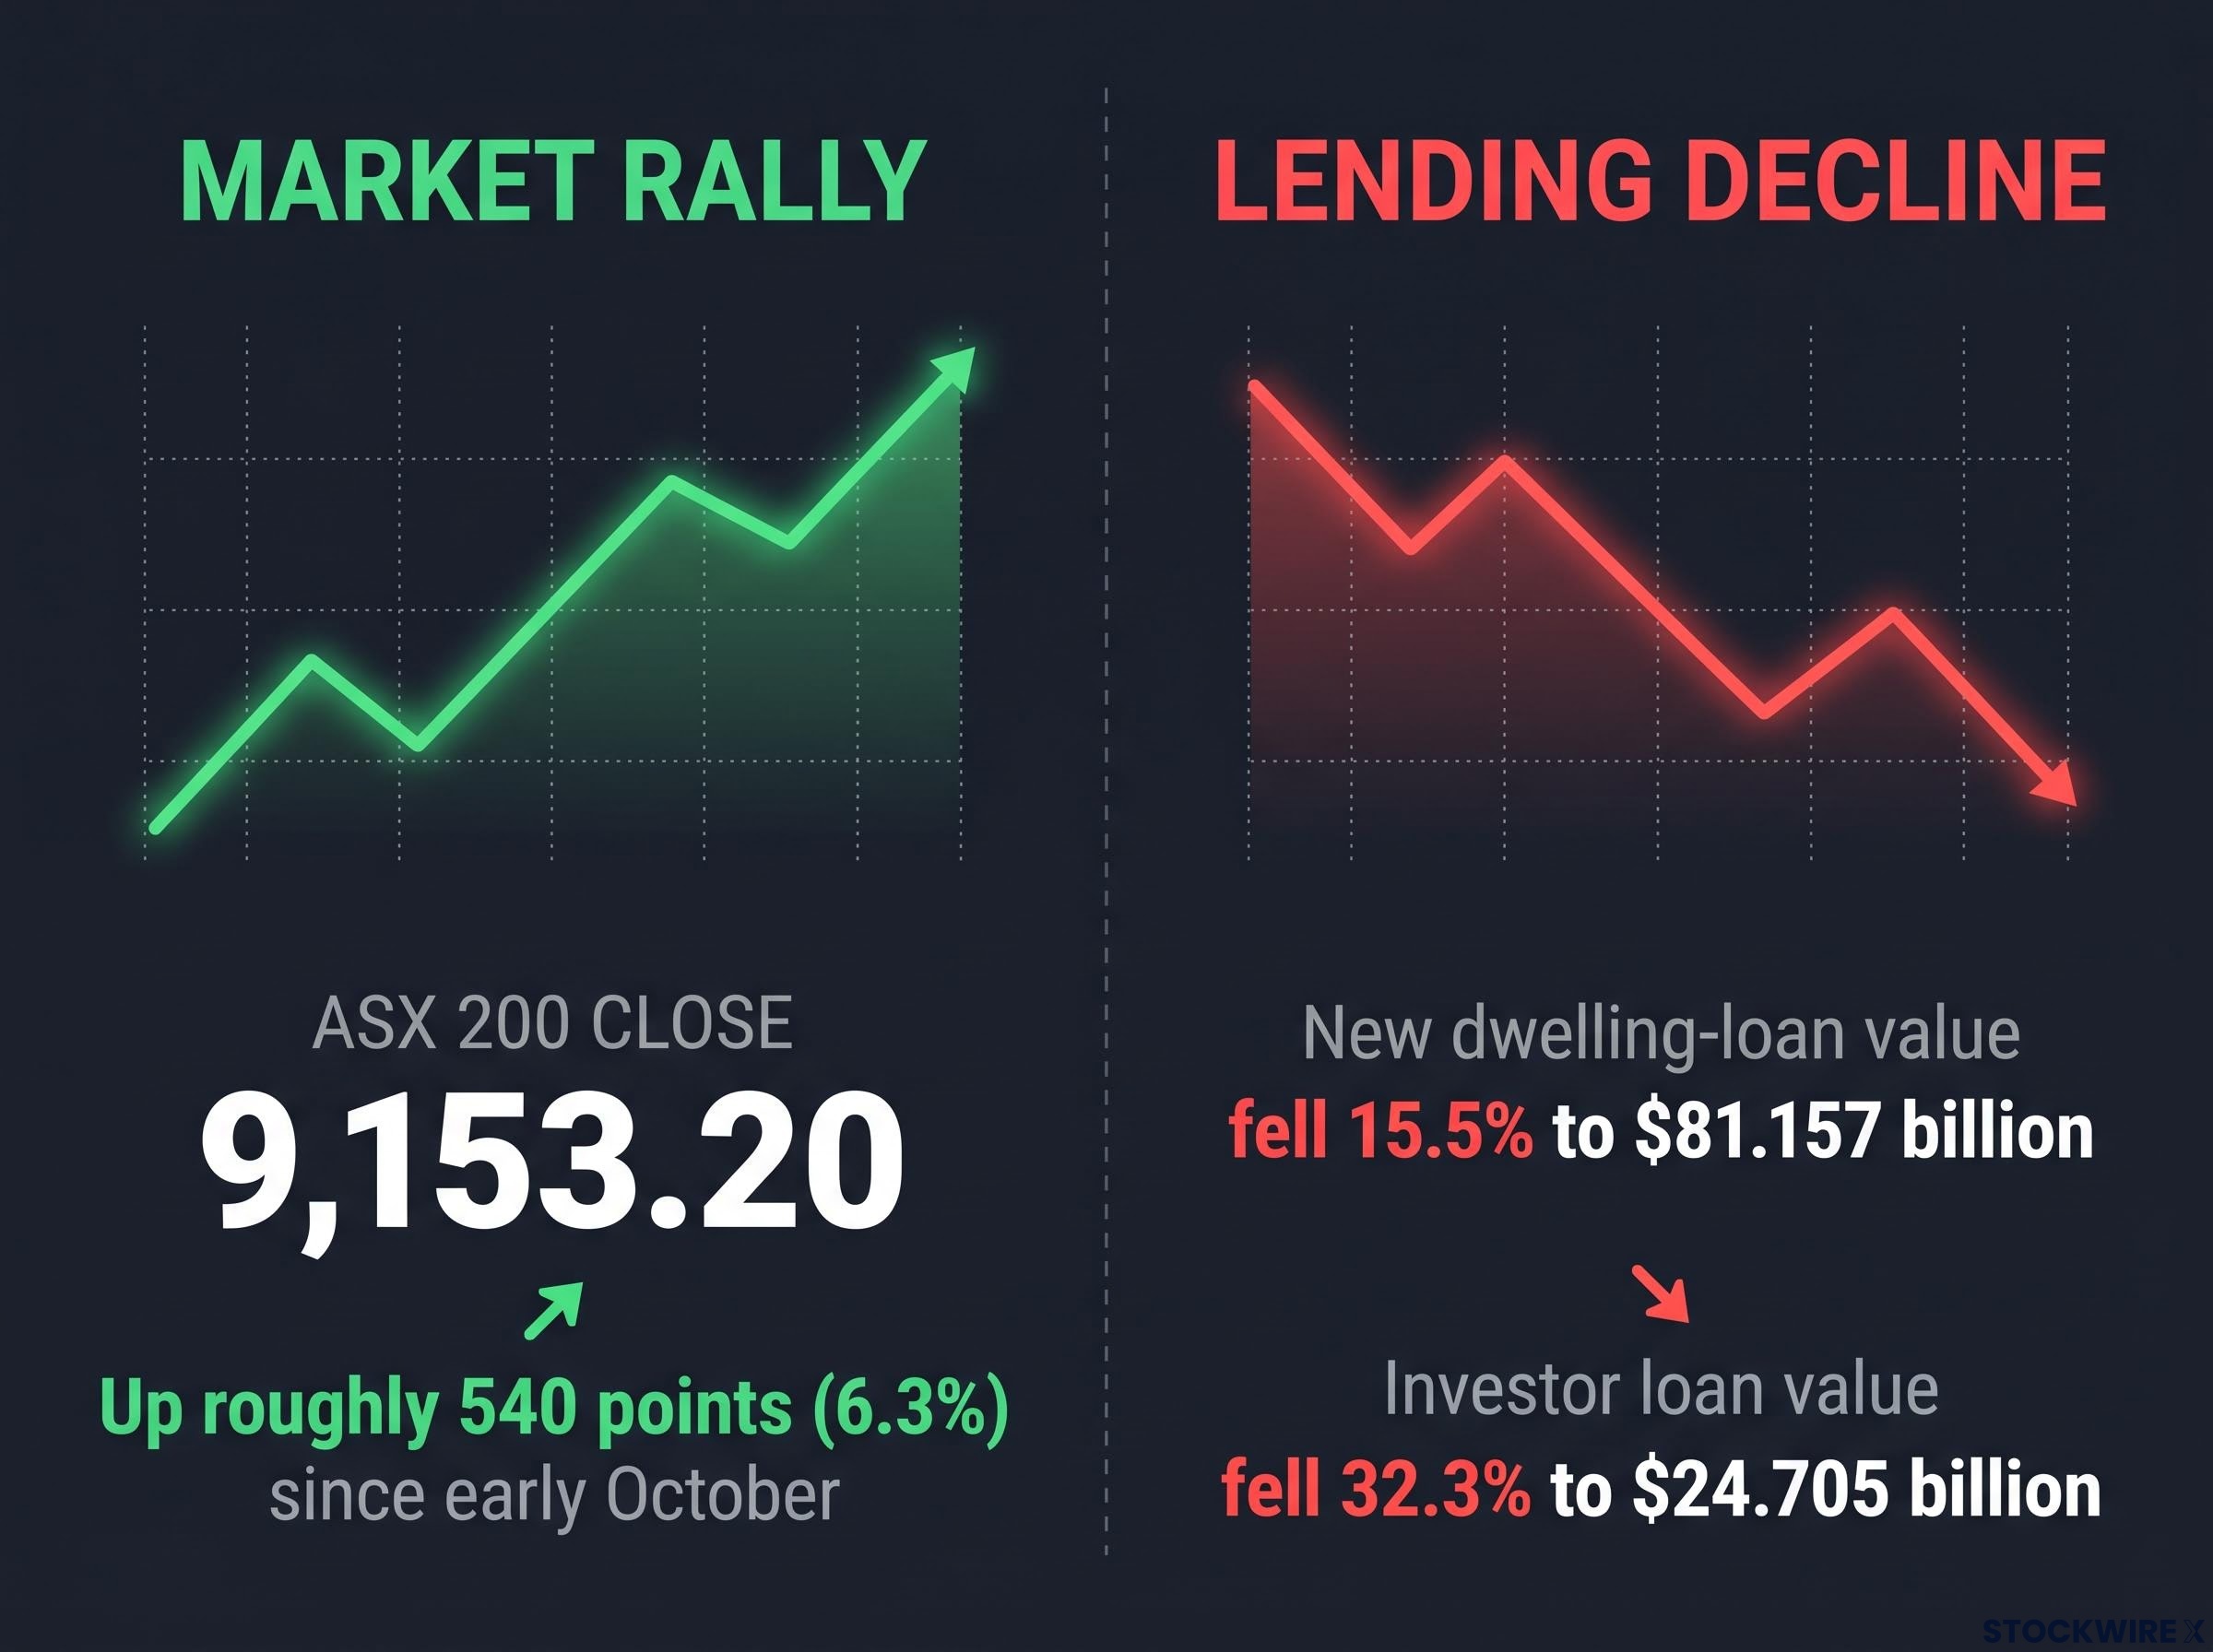
The ASX 200 has gained roughly 540 points, or 6.3%, while new dwelling-loan value fell 15.5% to $81.157 billion and investor loans fell 32.3%.
What actually drove the third straight gain?
Wednesday’s session did not start well. The index opened weak, swung through a volatile middle stretch and only reached its session peak late in trading. It closed up 24.20 points, or 0.27%, for a third straight daily gain.
The sector split explains more than the close does.
- Close: 9,153.20, up 0.27%
- Technology: about +1.52%, the strongest sector
- Financials: about -0.35%, the only major sector to fall
- Also higher: materials, utilities and energy
- Australian dollar: around 68.7 US cents
Technology’s lead was linked partly to news about the valuation range for Anthropic’s prospective initial public offering (IPO), which lifted sentiment towards growth stocks. Banks, which carry heavy weight in the index and depend on domestic lending, went the other way.
Since early October The ASX 200 has gained roughly 540 points, or about 6.3%, from its early-October low.
No attributable broker commentary from groups such as Morningstar or Macquarie was found explaining the full move since October. The best-supported reading of the evidence is cyclical relief and earnings repricing, not a structural improvement in domestic demand.
That matters for how you read your own portfolio. A 0.27% gain led by tech, with banks falling, suggests the index level is flattering the domestic economy. It is worth checking whether your holdings are exposed to the sectors doing the lifting or to the ones carrying the strain.
The RBA rate hike impact on households has been building since September, with falling home values and record-low sentiment readings showing up before any earnings downgrade, which is why index strength can mislead on the domestic economy.
When big ASX news breaks, our subscribers know first
Which stocks moved the market, and why do the takeover and earnings stories differ?
The sector pattern points to narrow drivers, and the stock movers confirm it. The most dramatic story came from a bidder that had already been turned away twice.
IDP Education jumped after Blackstone returned with a revised, unsolicited, non-binding proposal of $3.00 cash per share, valuing the company at about $835 million. It was announced after the close on 10 November. The price is 20% above Blackstone’s prior $2.50 proposal and about 36% above the undisturbed close of $2.21.
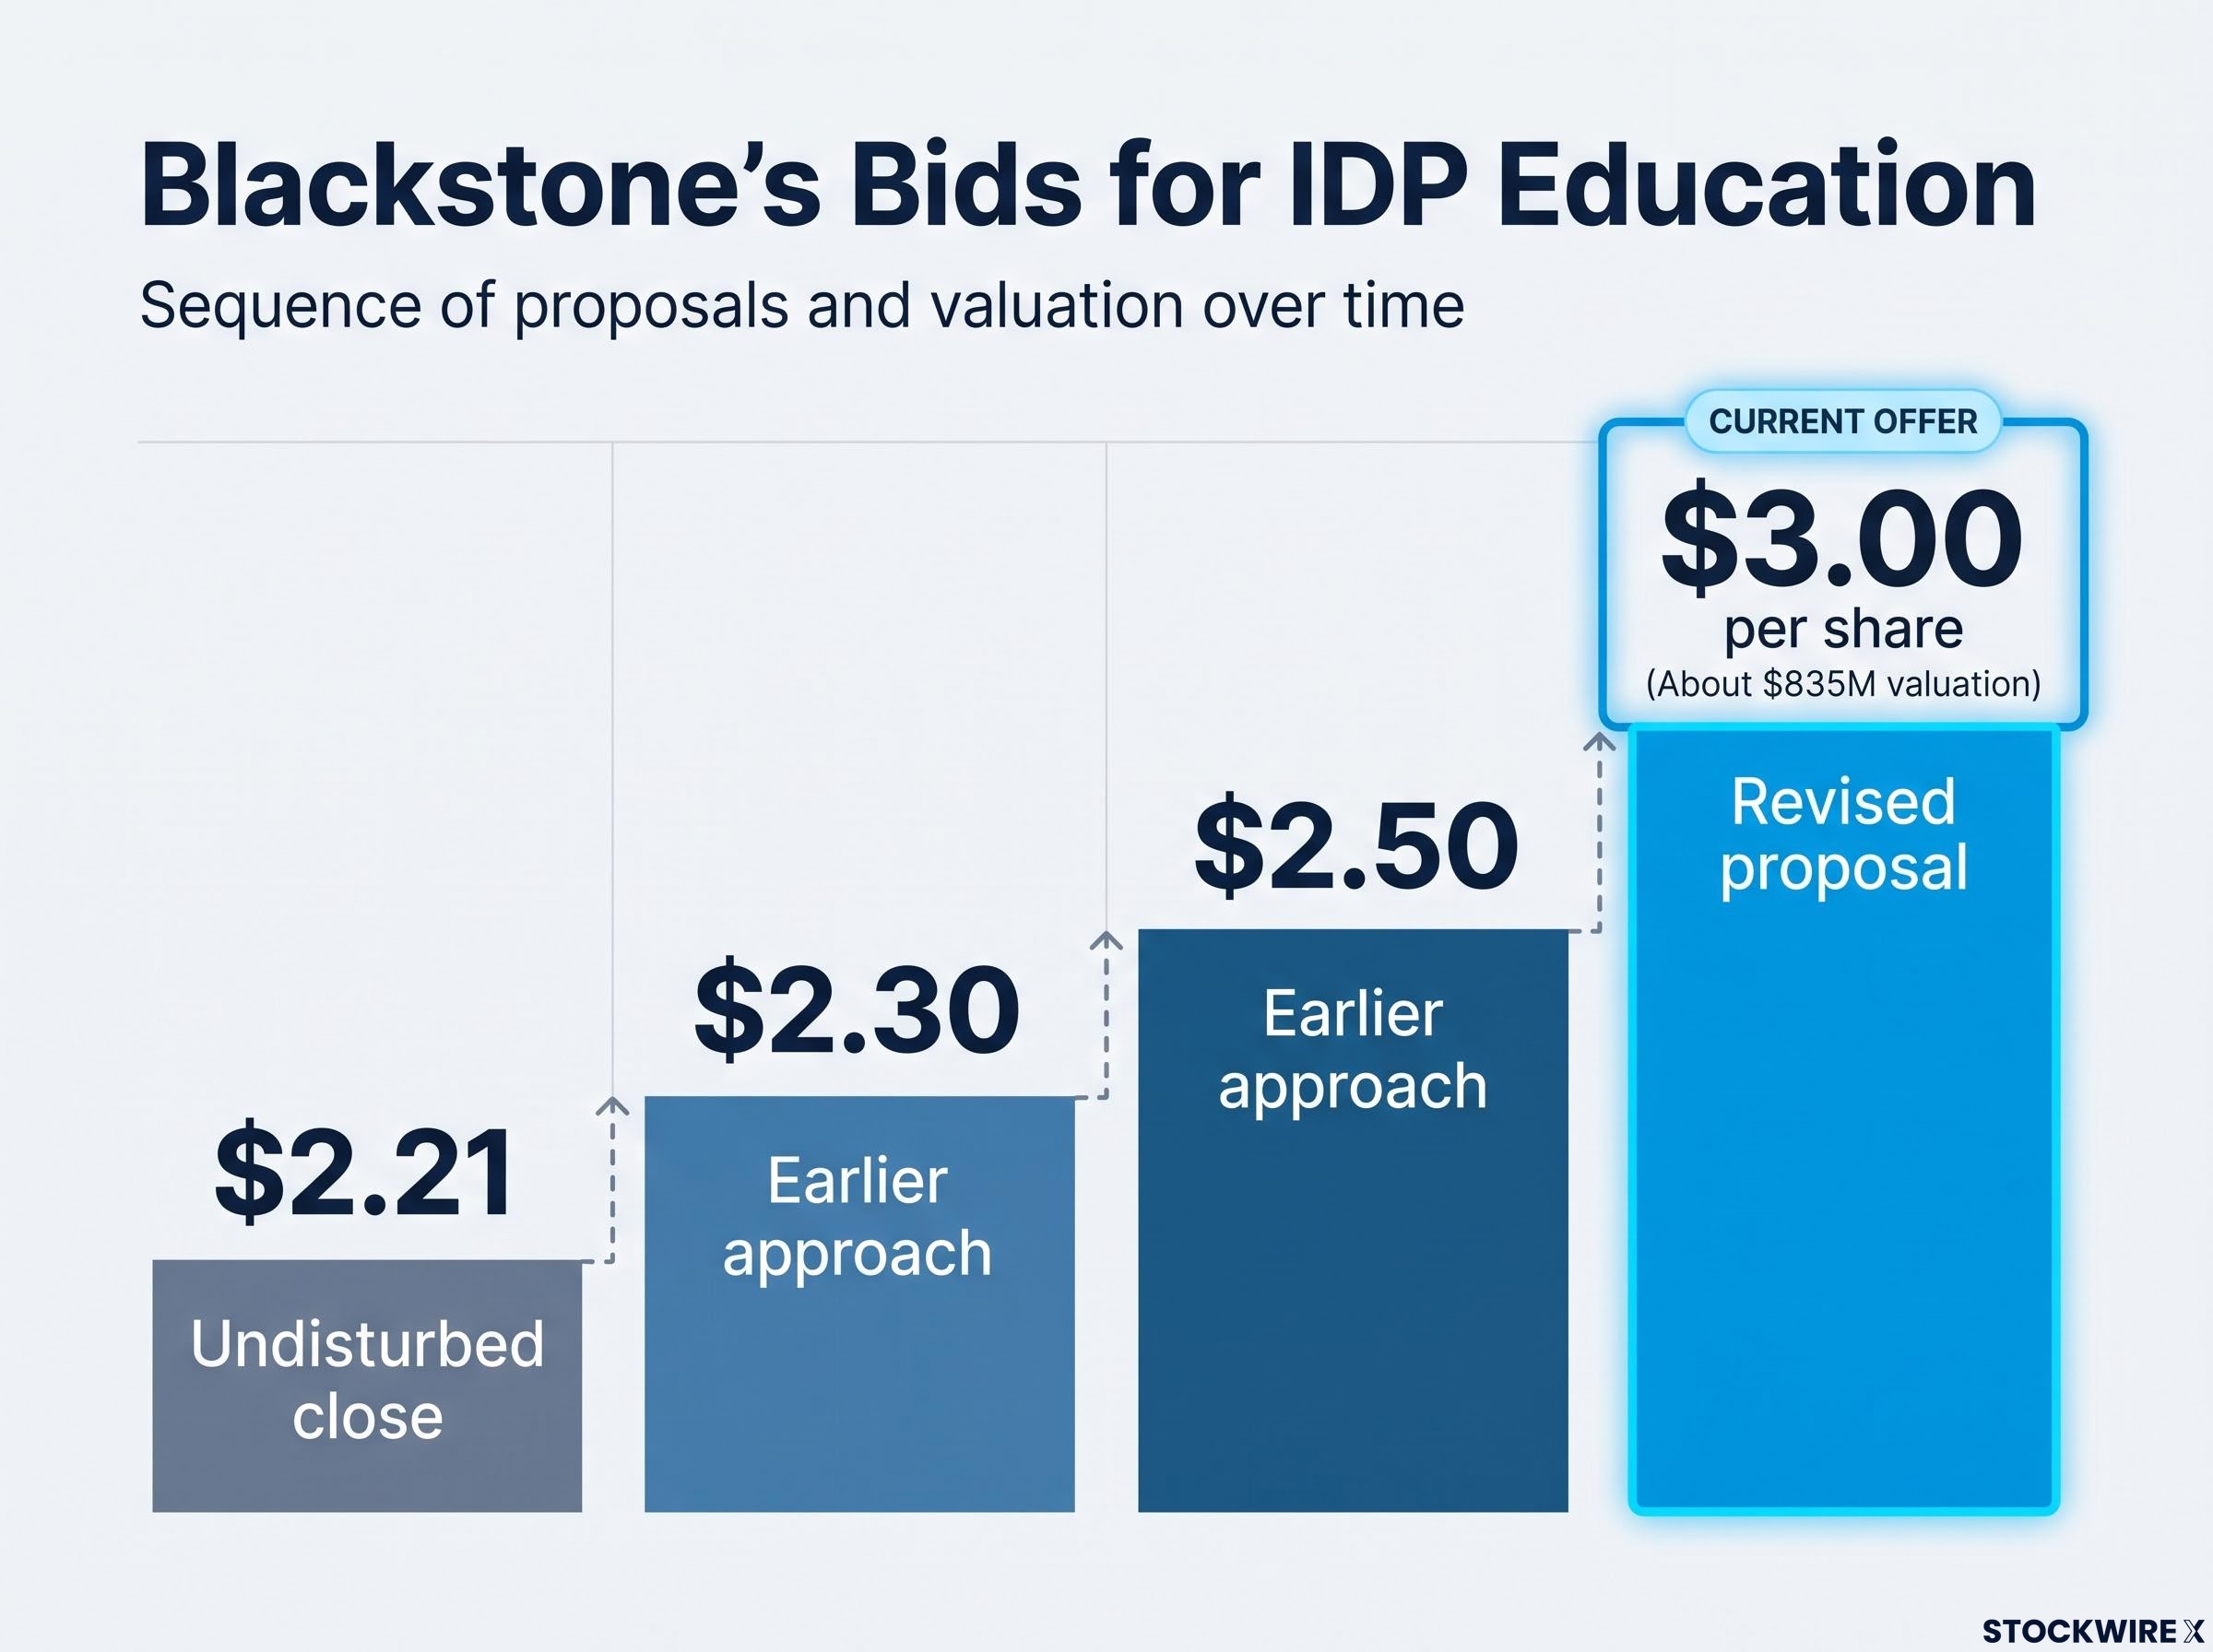
Blackstone’s revised proposal of $3.00 per share values IDP Education at about $835 million, well above the $2.21 undisturbed close.
The size of IDP’s share move varies by source. One report put the rise at 16.2%, while others cited roughly 16-24%, a spread that likely reflects intraday peaks versus the closing price.
How a rejected takeover bid becomes a live one
Blackstone’s earlier approaches, at $2.30 and then $2.50, were unanimously rejected. The board said they failed to reflect the fundamental value of IDP’s global platform and were highly opportunistic in their timing.
The board’s language on the $3.00 proposal is different. It said it will consider the offer, but it has made no decision, makes no recommendation and gives no assurance a transaction will proceed. Its stated considerations include fundamental value, future earnings potential, the benefits of its transformation programme and the interests of shareholders as a whole.
The shift tells you an initial rejection is not necessarily final. It does not tell you how this one ends.
The other movers rode quieter, earnings-based catalysts.
| Company | Catalyst | Key figure | Reported share move |
|---|---|---|---|
| IDP Education | Revised Blackstone proposal | $3.00 per share (about $835 million) | 16.2% in one report; others about 16-24% |
| Monadelphous | First-half FY2027 indication | About $1.7 billion revenue; $80-85 million NPAT | 7.2% on 11 November in one report; about 15% elsewhere |
| Life360 | Rebound after Q3 FY2026 sell-off | Revenue US$174.1 million, up 40% | Up about 10% |
| Minerals 260 | Bullabulling debt approval | $410 million credit-approved debt | Unclear; no single figure confirmed |
The Monadelphous conflict likely reflects different sessions, since the stock also rose on 10 November. Life360, whose adjusted earnings before interest, tax, depreciation and amortisation (EBITDA) rose 41% to US$34.6 million and which added about 5.3 million active users, had fallen on 10 November after lowering the top end of its revenue targets. Minerals 260’s $335 million project finance and $75 million working capital facilities from ANZ, NAB and Société Générale sit alongside $170 million of Franco-Nevada royalty funding, a $30 million equity investment and a $250 million placement.
The common thread is that each gain came from a specific catalyst. Holding the index does not give you the same exposure as owning these names, and any takeover proposal stays conditional until a board recommends it.
Why are housing and retail data flashing warning signs?
While those stocks rallied, the ABS released September-quarter housing finance figures that were worse than expected. The value of new dwelling-loan commitments fell 15.5% to $81.157 billion, the largest quarterly drop since the series began in September 2002. Loan numbers fell 15.0% to 111,878.
Investors pulled back hardest. Investor-loan numbers dropped 30.6% to 35,301.
Record investor retreat The value of investor loans fell 32.3% to $24.705 billion, the largest quarterly investor decline on record.
The mechanism: from fewer settlements to weaker earnings
A lending fall does not stay inside the housing market. It travels through listed company earnings in four steps.
- Fewer deals: When fewer people buy homes or refinance, fewer property settlements happen. A settlement is the final step where money and ownership change hands.
- Fewer transactions for PEXA: PEXA runs the electronic platform most settlements pass through and earns revenue per transaction, so lower volumes cut revenue while many costs stay fixed. This squeezes operating leverage, which is how much profit grows or shrinks as revenue changes.
- Slower bank growth: Weaker lending means banks write fewer new loans, which limits how fast their loan books grow and can reduce fee income.
- Wider spending effects: Lower property turnover weighs on mortgage competition and on spending linked to moving house, such as furniture and homewares.
Who is exposed: PEXA, the banks and discretionary retailers
PEXA shares fell a little over 3% after it reported Q1 FY2027 volumes down 11.5% to 934,000 and cut its guidance. The company blamed consecutive interest-rate rises, tax changes and falling property prices.
Australia’s 15-year high cash rate, the highest since November 2011, is the backdrop for the PEXA volume decline, since borrowers who have never faced rates this level are delaying purchases and refinancing.
| Measure | Previous FY2027 guidance | Revised FY2027 guidance |
|---|---|---|
| Revenue | $385-415 million | $355-380 million |
| Core NPAT | $5-20 million profit | $6 million loss to $6 million profit |
| EBITDA margin | 31.5-33.5% | 29.0-31.5% |
Commonwealth Bank rose early, then reversed after the ABS release to finish down about 1.2%. CBA also reported a quarterly result before the open and Macquarie traded ex-dividend the same day, so the housing data is one factor in that move, not the sole cause. Adairs fell about 2% after reporting first-19-week sales down 0.6%, and said conditions had grown tougher over the past six weeks.
Westpac-Melbourne Institute consumer sentiment sits at 78.2, its weakest since late 2022. Falling turnover hits transaction-based businesses and bank growth before it shows up in headline indices, so a portfolio tilted to housing-linked earnings carries more exposure than the index level suggests.
Can the holiday retail season offset the weakness?
Adairs’ improvement from a 4.5% decline in its first eight weeks is the hopeful side of its update. Whether that holds depends on what comes next.
| Positive case | Risk case |
|---|---|
| Roy Morgan and the Australian Retail Council forecast $7.2 billion of Black Friday-Cyber Monday spending (27-30 November), up 5.5% | Household consumption forecasts have been downgraded to 1.4% annual growth |
| 58% of shoppers cite lower prices as their main motivation, which can drive strong volumes | Only about 38% plan to spend more on gifts |
| Black Friday can bring Christmas spending forward and clear inventory | Heavy discounting can compress gross margins |
| Concentrated event spending can lift sales even when demand is soft | RBA liaison contacts expect softer discretionary conditions into 2027 |
The Australian Retail Council said the Reserve Bank’s rate rise came just before Black Friday and Christmas. Deloitte expects discretionary spending to bear the brunt of the slowdown as households delay purchases or trade down.
Weak discretionary spending intent has been visible for months, and the wider recession risk in Australian retail numbers helps explain why Adairs and other housing-linked retailers describe tougher trading even as event-driven sales rise.
That makes Adairs, which also owns Mocka and Focus on Furniture, a live test. Its remaining seven weeks to 27 December made up about one-third of last year’s first-half group sales.
Strong discount-event volumes can coexist with weak underlying demand and thinner margins. Sales headlines alone will not confirm a recovery; the margin story will. The principal risk to the rally is that equities are pricing in a recovery before household demand, housing turnover and company guidance actually improve.
What to watch on Thursday and through the holiday season
The rally rests on tech strength and company-specific catalysts, while housing and discretionary data soften underneath. The coming weeks will show which force carries more weight.
Thursday 12 November brings:
- ANZ trading ex-dividend, which may weigh on banks
- Aristocrat Leisure full-year results
- Ora earnings (date not separately confirmed)
- Harvey Norman dividend payment
- Numerous annual general meetings
- Little US data overnight
Some calendars also list Paladin and Life360 updates, but Life360 released its Q3 FY2026 results on 9 November and no Paladin date has been confirmed.
Beyond Thursday, follow the IDP board’s response to Blackstone, the next housing data and Black Friday trading updates. Transaction completion and future company performance are not guaranteed, and these signals may move in either direction.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.