
Compumedics outlines Value Realisation Program to realise R&D value
In its November 2026 investor update, Compumedics (ASX: CMP) outlined a Value Realisation Program built on five programs: three for Somfit®, one for MEG and one for DWL®. Each has dedicated specialist deal makers pursuing partnership, licensing, co-development and strategic investment.
The presentation stated the aim is an accretive return on shareholders’ existing investment. The presentation framed this against a record FY26 revenue of A$60.3m and a 39-year history with 25,000+ installed systems. No transaction has been agreed, and there is no certainty that any transaction will proceed.
Five programs and the first adviser appointed
The presentation detailed the status of each program:
- Program 1, Somfit® US pharmacy and consumer: adviser appointed.
- Program 2, Somfit® pharma and CRO trials: search under way.
- Program 3, Somfit® cardiology: search under way.
- Program 4, DWL® TCD AI-robotics: search under way.
- Program 5, OrionMEG®: search under way.
Syed Husain of Red Brook Advisors is lead adviser for Program 1. Management said 2-3 further appointments are expected by the end of the March 2027 quarter.
The Red Brook Advisors appointment brings a registered pharmacist with more than 30 years of healthcare deal experience, including almost 20 years at a Fortune 5 US healthcare company, to the Somfit® pharmacy and consumer program.
Leadership changes behind the program
The company highlighted a deeper team supporting the program:
- Mike Stone is Chief Commercial Officer, USA, since June 2026.
- Troy Lamb is CFO and Company Secretary from 1 November 2026.
- David Lawson is Finance Director.
- Dr William Oliver leads OrionMEG® US entry.
When big ASX news breaks, our subscribers know first
FY26 results and recurring revenue momentum
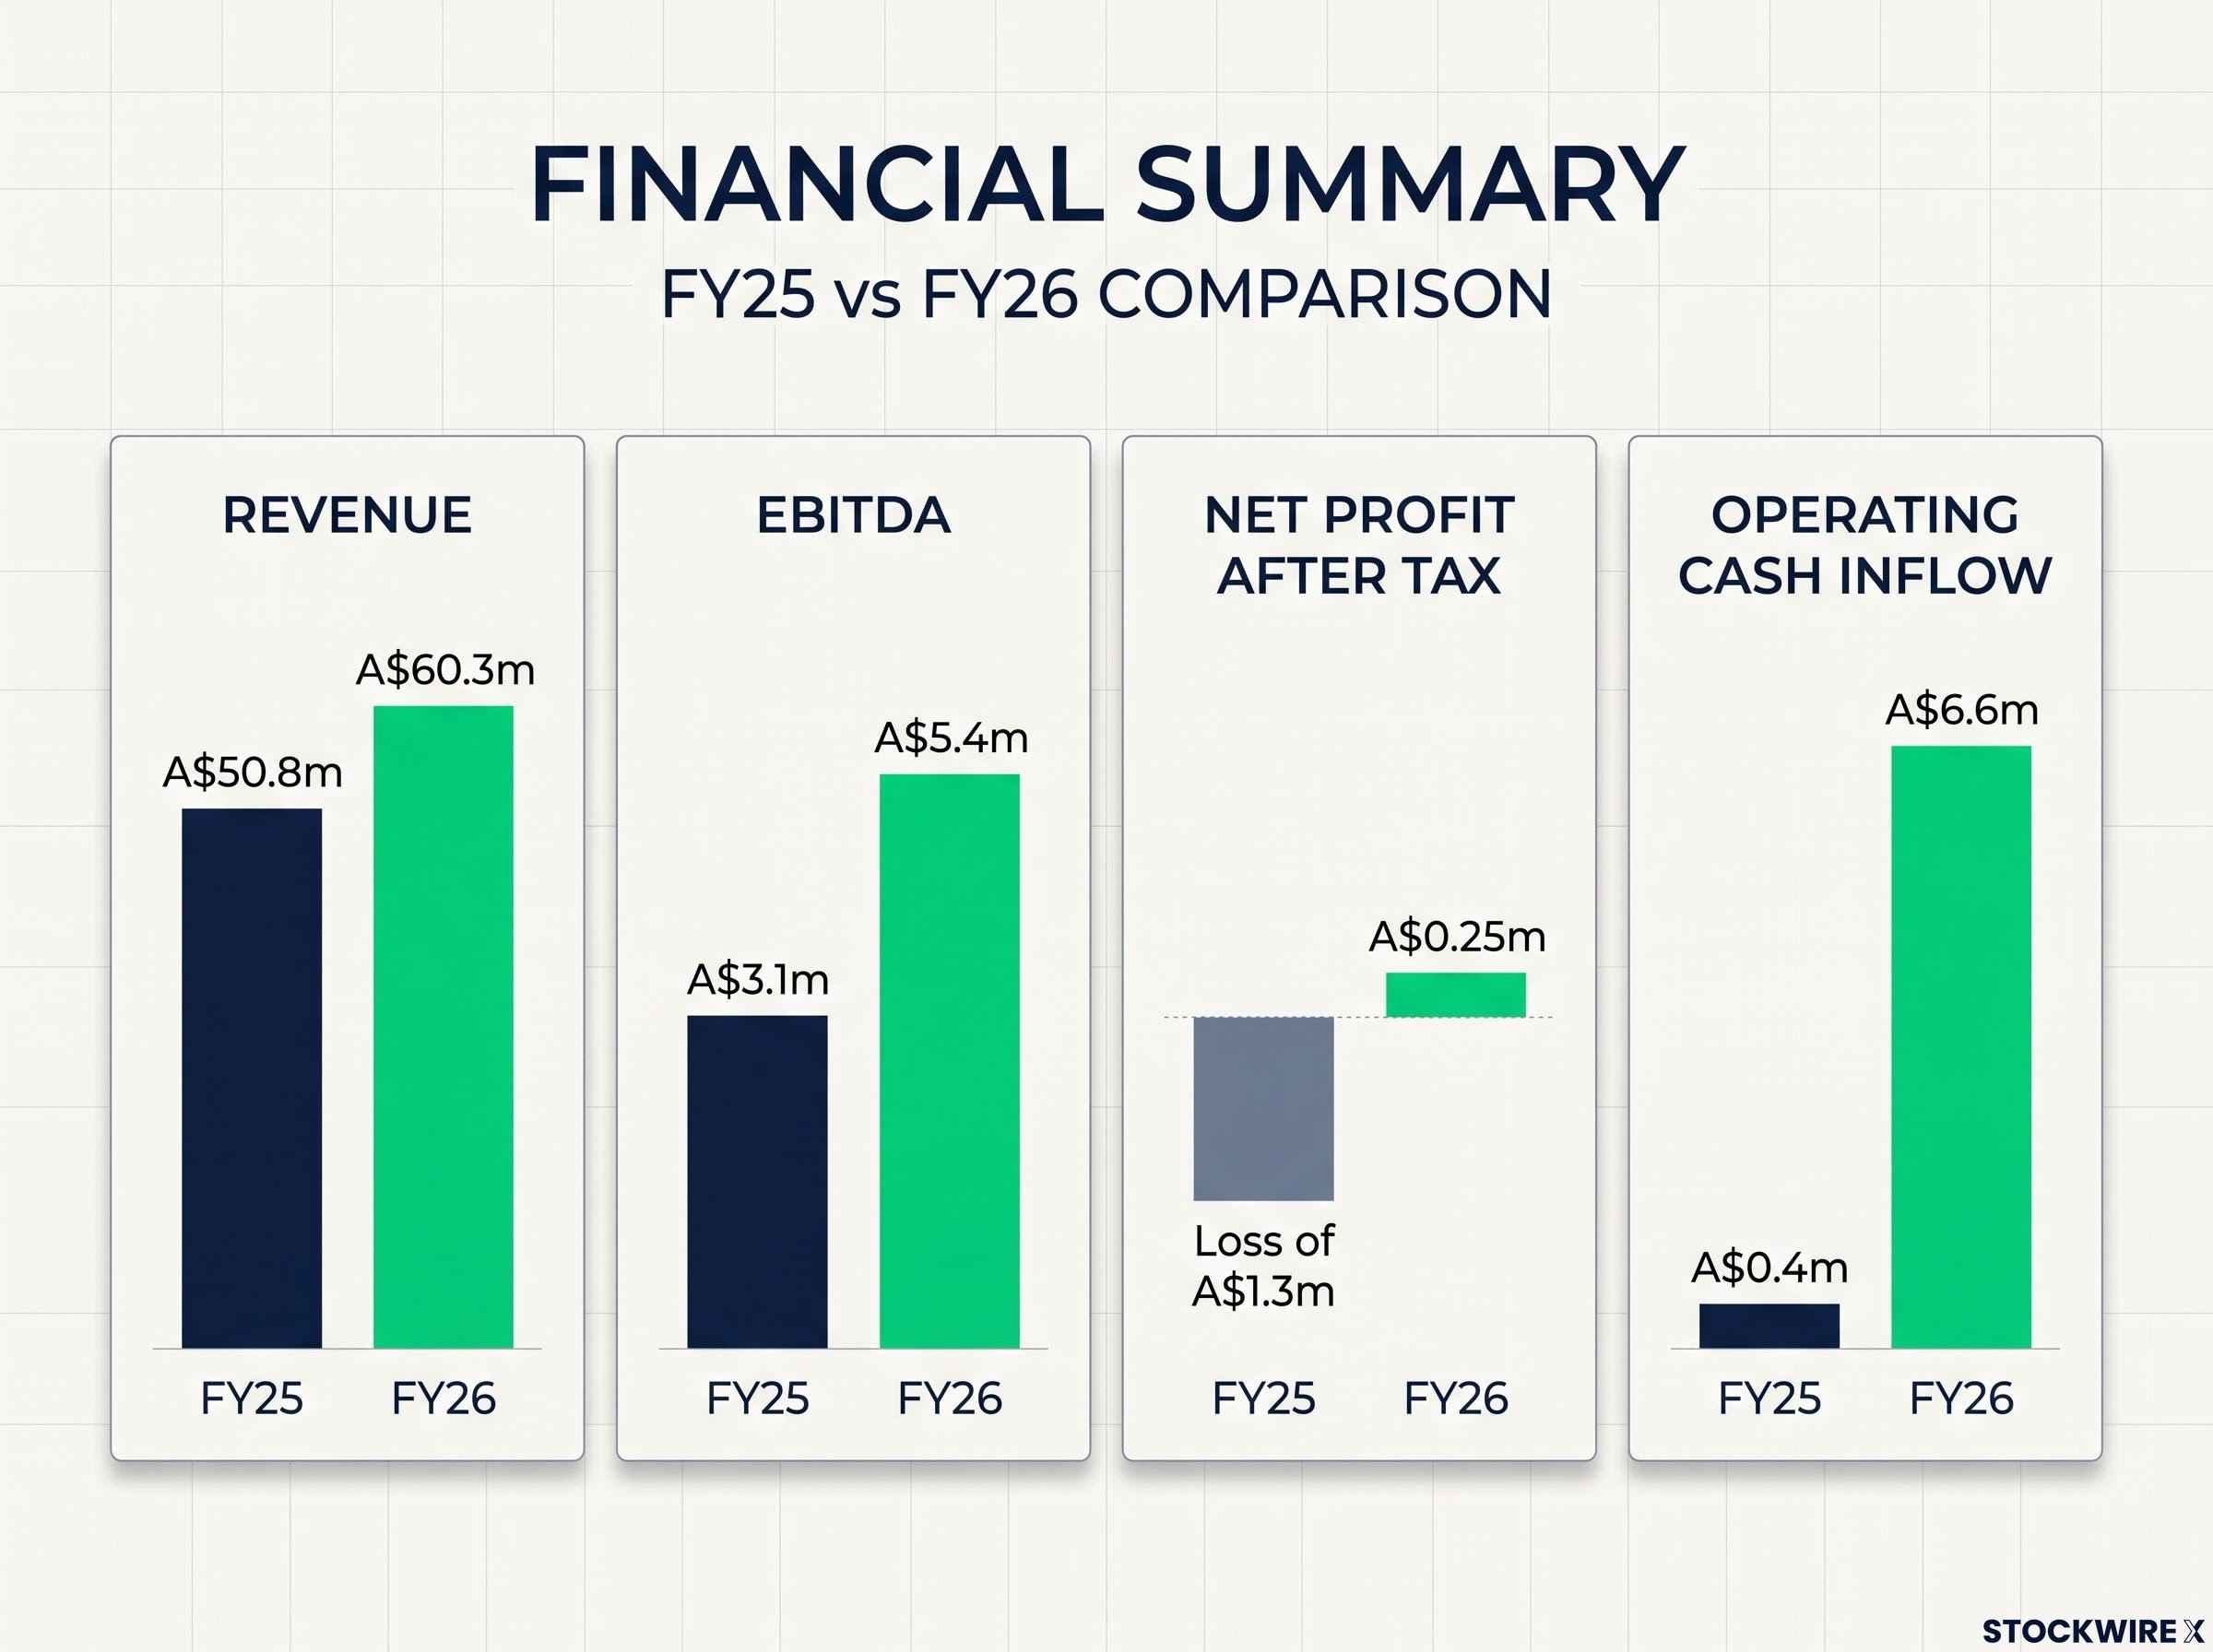
Management outlined a return to profit and a sharp cash turnaround for FY26. Revenue grew 18.5% on FY25, and the EBITDA margin reached 9% (FY25: 6%).
| Metric | FY26 | FY25 |
|---|---|---|
| Revenue | A$60.3m | A$50.8m |
| EBITDA | A$5.4m | A$3.1m |
| Net profit after tax | A$0.25m | Loss of A$1.3m |
| Operating cash inflow | A$6.6m | A$0.4m |
SaaS and recurring revenue
The presentation showed more revenue now recurring:
- Somfit® and NEXUS 360® SaaS revenue was A$10.2m, up 70%, and 17% of Group revenue.
- Recurring revenue reached 30% of sales (A$18.3m).
- More than 1,000,000 studies are on the platform.
Guidance missed, approach reset
Management stated plainly that FY26 guidance was missed. Revenue of A$60.3m and EBITDA of A$5.4m compared with the April 2026 revised ranges of A$62-65m and A$5.5-7m.
The company named the main causes as MEG shipment delays from helium supply and pricing disruption, and a later-than-planned Somfit® D US release. It said revenue was delayed rather than lost, with A$28.3m of open orders entering FY27, including A$13.1m of MEG.
The new guidance approach, as outlined:
- One year ahead only, and conservatively.
- No multi-year scenarios or valuations.
- Milestones reported once delivered.
Growth platforms: Somfit®, MEG and DWL®
Somfit® D shipping and US reimbursement
The first 50 units of the FDA 510(k)-cleared Somfit® D shipped to US customers in November 2026. The presentation also highlighted:
- More than 75% of the Australian and NZ pharmacy home-sleep-testing segment.
- Master Services Agreements with 2 of the top 5 global CROs.
- Approximately A$3.5m of products invoiced to pharma and CRO customers.
From 1 January 2027, US home sleep test codes are set by how much a test measures. Complexity is decided by the lower of the channel count and the parameter-category count.
Somfit® measures sleep directly from frontal EEG, EOG and EMG, and the current US release is designed to support moderate-complexity reporting. An FDA 510(k) submission for the high-complexity capability is planned for the December 2026 quarter, with release following FDA clearance.
OrionMEG® and DWL®
MEG delivered A$9.7m of FY26 revenue from nil in FY25, with 7 Orion systems sold and an order book of A$13.1m. US research hospitals are expected to begin ordering in FY27, with first US installations anticipated in FY28.
DWL® generated A$4.5m of revenue (FY25: A$4.7m). Robotic-probe patents were granted in the US, EU and China in 2026, and the Board is pursuing partnership and strategic investment for the robotic TCD.
Balance sheet and what to watch
Management reported a stronger balance sheet at 30 June 2026:
- Cash of A$6.1m (FY25: A$2.7m).
- Borrowings of A$13.1m.
- Both bank covenants met: equity ratio 41.7% and debt service cover 1.43x.
The company stated there are no current plans to raise capital. FY27 guidance is for double-digit revenue growth, with EBITDA growing faster than revenue.
On the register, 199.8m shares were on issue, giving a market capitalisation of A$47.9m at A$0.24 per share on 10 November 2026. The founder group held 49.17% at 17 September 2026.
What to watch next for Compumedics
- New US unattended sleep-test codes take effect on 1 January 2027.
- The Somfit® high-complexity 510(k) submission is planned for the December 2026 quarter.
- The Somfit® high-complexity release follows FDA clearance.
- Further deal-maker appointments (2-3) are expected by the end of the March 2027 quarter.
- The half-year result is scheduled for February 2027.
- Somfit® Pro US registration is anticipated in mid-FY27.
- The Somfit® disposable launch in the US, Canada and Australia is expected in FY27.
- US research hospitals are expected to begin ordering MEG in FY27.
Want Alerts Like This on the Healthcare Stocks You Follow?
StockWire X Market Intelligence scores every announcement in our coverage for how significant it’s likely to be for investors, and which way it points, then alerts you on the stocks you follow. The first 1,000 founding members lock in 50% off for life: A$247 a year instead of the standard A$495. Join the founding waitlist today.