The US Federal Reserve and the European Central Bank were both expected to raise interest rates in December, so you might assume the euro would hold its ground against the dollar. It did not. On Friday, 6 November 2026, EUR/USD slid to about 1.1132, erasing its weekly gain and breaking below 1.12, which reshapes the near-term EUR/USD forecast.
Two releases did the damage. October US nonfarm payrolls showed 165,000 new jobs against a forecast of 65,000, while Eurozone retail sales for September fell 0.7% month on month.
The lesson sits in the gap between those numbers and what markets expected. Both central banks were already leaning towards tightening, so the move came from relative surprise, not from simple policy direction.
Here is a repeatable way to trace a data release through to rate expectations and then to the exchange rate. With it, you can judge what Friday’s slide means for the euro-dollar outlook heading into December, and how to read the next release yourself.
What did Friday’s data actually show, and how far did the dollar move?
The US side
The payrolls figure beat consensus by 100,000 jobs. For a number that economists forecast with care each month, a miss of that size tells you the market had badly underestimated how strong US hiring was.
The supporting detail pointed the same way. The US Bureau of Labor Statistics revised September payrolls up to 60,000 from 29,000, and unemployment slipped to 4.1% from 4.2%.
Average hourly earnings rose 0.4% for the month against 0.3% expected. Annual wage growth eased to 3.1% from 3.2% but still beat the 2.9% forecast.
The Eurozone side
Across the Atlantic, the picture was softer. Eurostat reported that September retail sales fell 0.7% month on month, against a forecast fall of 0.1%. Annual growth came in at 0.4%, below the 0.6% forecast and down from 1.3%. Sources disagree on the August figure, so it is best set aside.
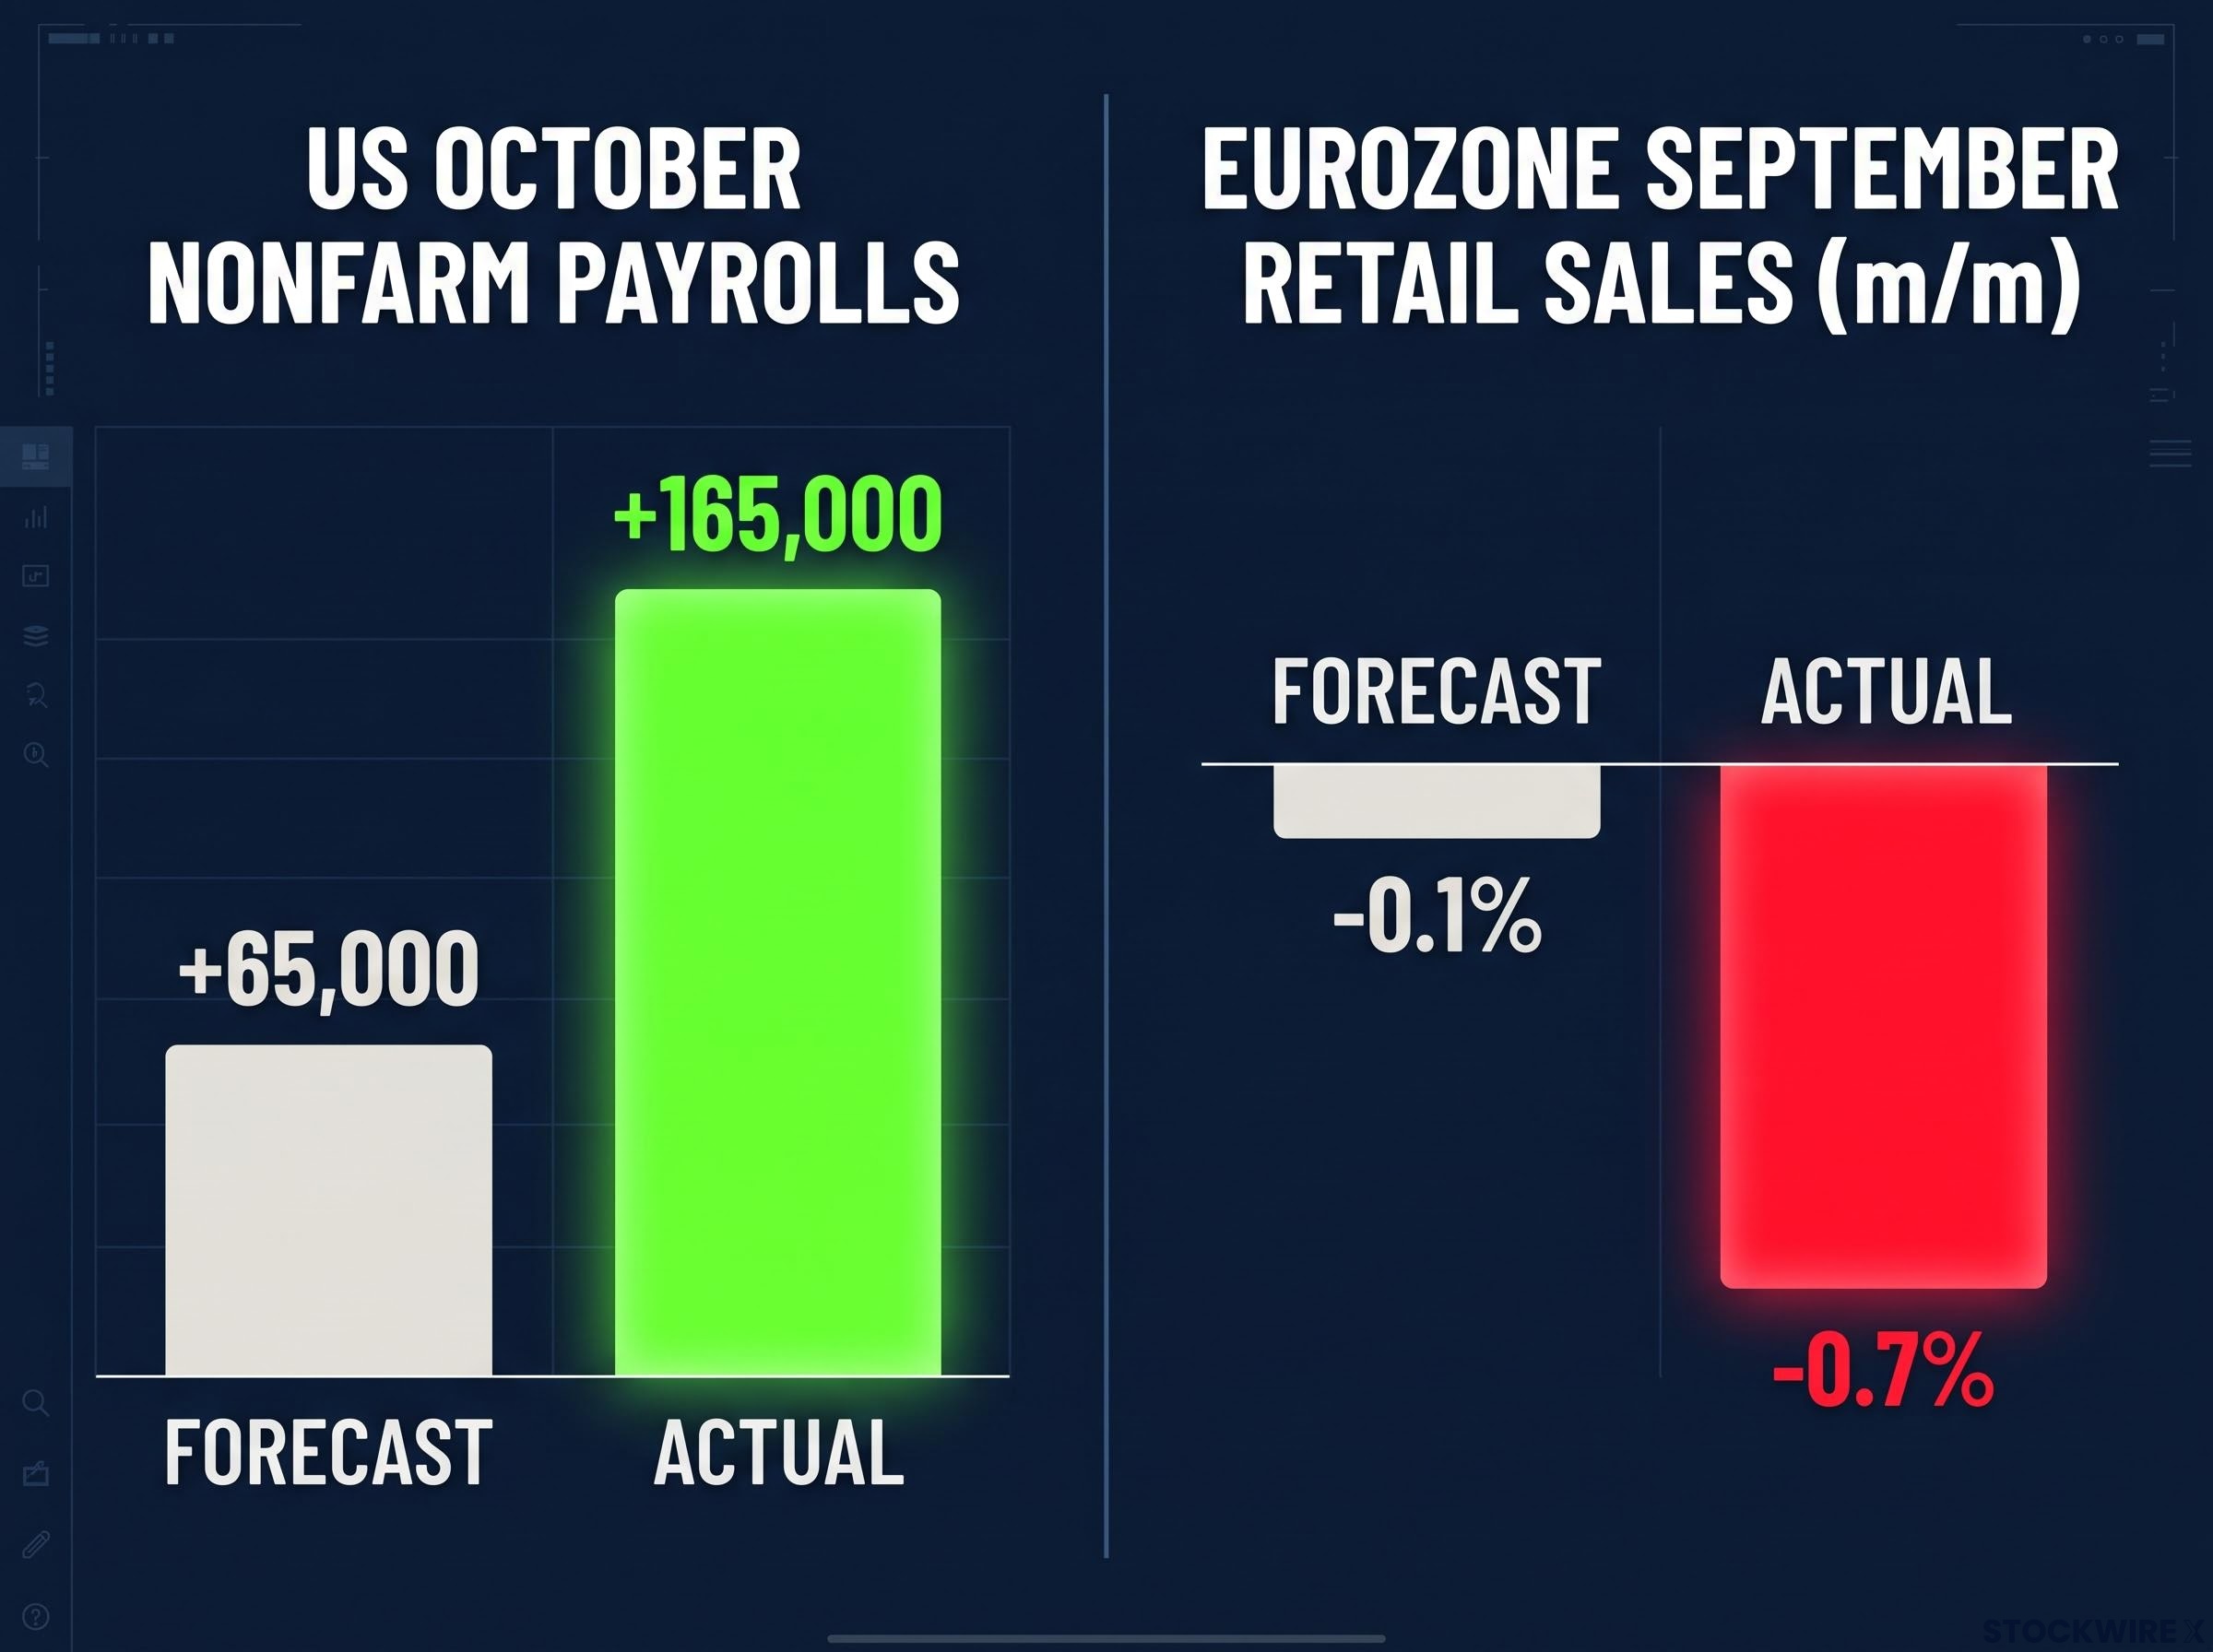
The dollar surged after US nonfarm payrolls added +165,000 jobs against a +65,000 forecast, while Eurozone retail sales dropped -0.7% instead of -0.1%.
| Release | Actual | Forecast or prior |
|---|---|---|
| US October nonfarm payrolls | +165,000 | +65,000 forecast |
| US September payrolls (revised) | +60,000 | +29,000 prior |
| US unemployment rate | 4.1% | 4.2% prior |
| US hourly earnings, annual | +3.1% | 2.9% forecast |
| Eurozone retail sales, m/m | -0.7% | -0.1% forecast |
| Eurozone retail sales, y/y | +0.4% | +0.6% forecast |
Put together, the two releases were a strong US surprise against a weak Eurozone one. The market response went well beyond the euro. The US Dollar Index (DXY), which tracks the dollar against a basket of major currencies, rose about 0.73% to 102.33.
| Currency | Dollar’s daily change |
|---|---|
| New Zealand dollar (NZD) | +1.20% |
| Australian dollar (AUD) | +1.12% |
| Canadian dollar (CAD) | +0.80% |
| British pound (GBP) | +0.79% |
| Euro (EUR) | +0.77% |
| Swiss franc (CHF) | +0.54% |
| Japanese yen (JPY) | +0.40% |
The euro was not singled out. The dollar rose against every major currency, and the euro landed mid-table. For you, that is the tell: this was a dollar story first, which is why a move this large needed no actual change in central bank policy.
When big ASX news breaks, our subscribers know first
How does a jobs report turn into a euro move? A five-step framework
Why should a count of American jobs shift the price of a European currency? The answer is a chain, and once you can see each link, you can apply it to any release.
The key principle Currencies move on surprise relative to expectations, not on the headline figure. If a number arrives exactly as forecast, it is already in the price.
That is why consensus matters so much. Consensus is the average forecast from economists polled before a release, and markets trade on the gap between it and the actual result. Events that are already priced, meaning traders have already bought or sold on the expectation, tend to move currencies far less.
Here is how the chain played out on Friday:
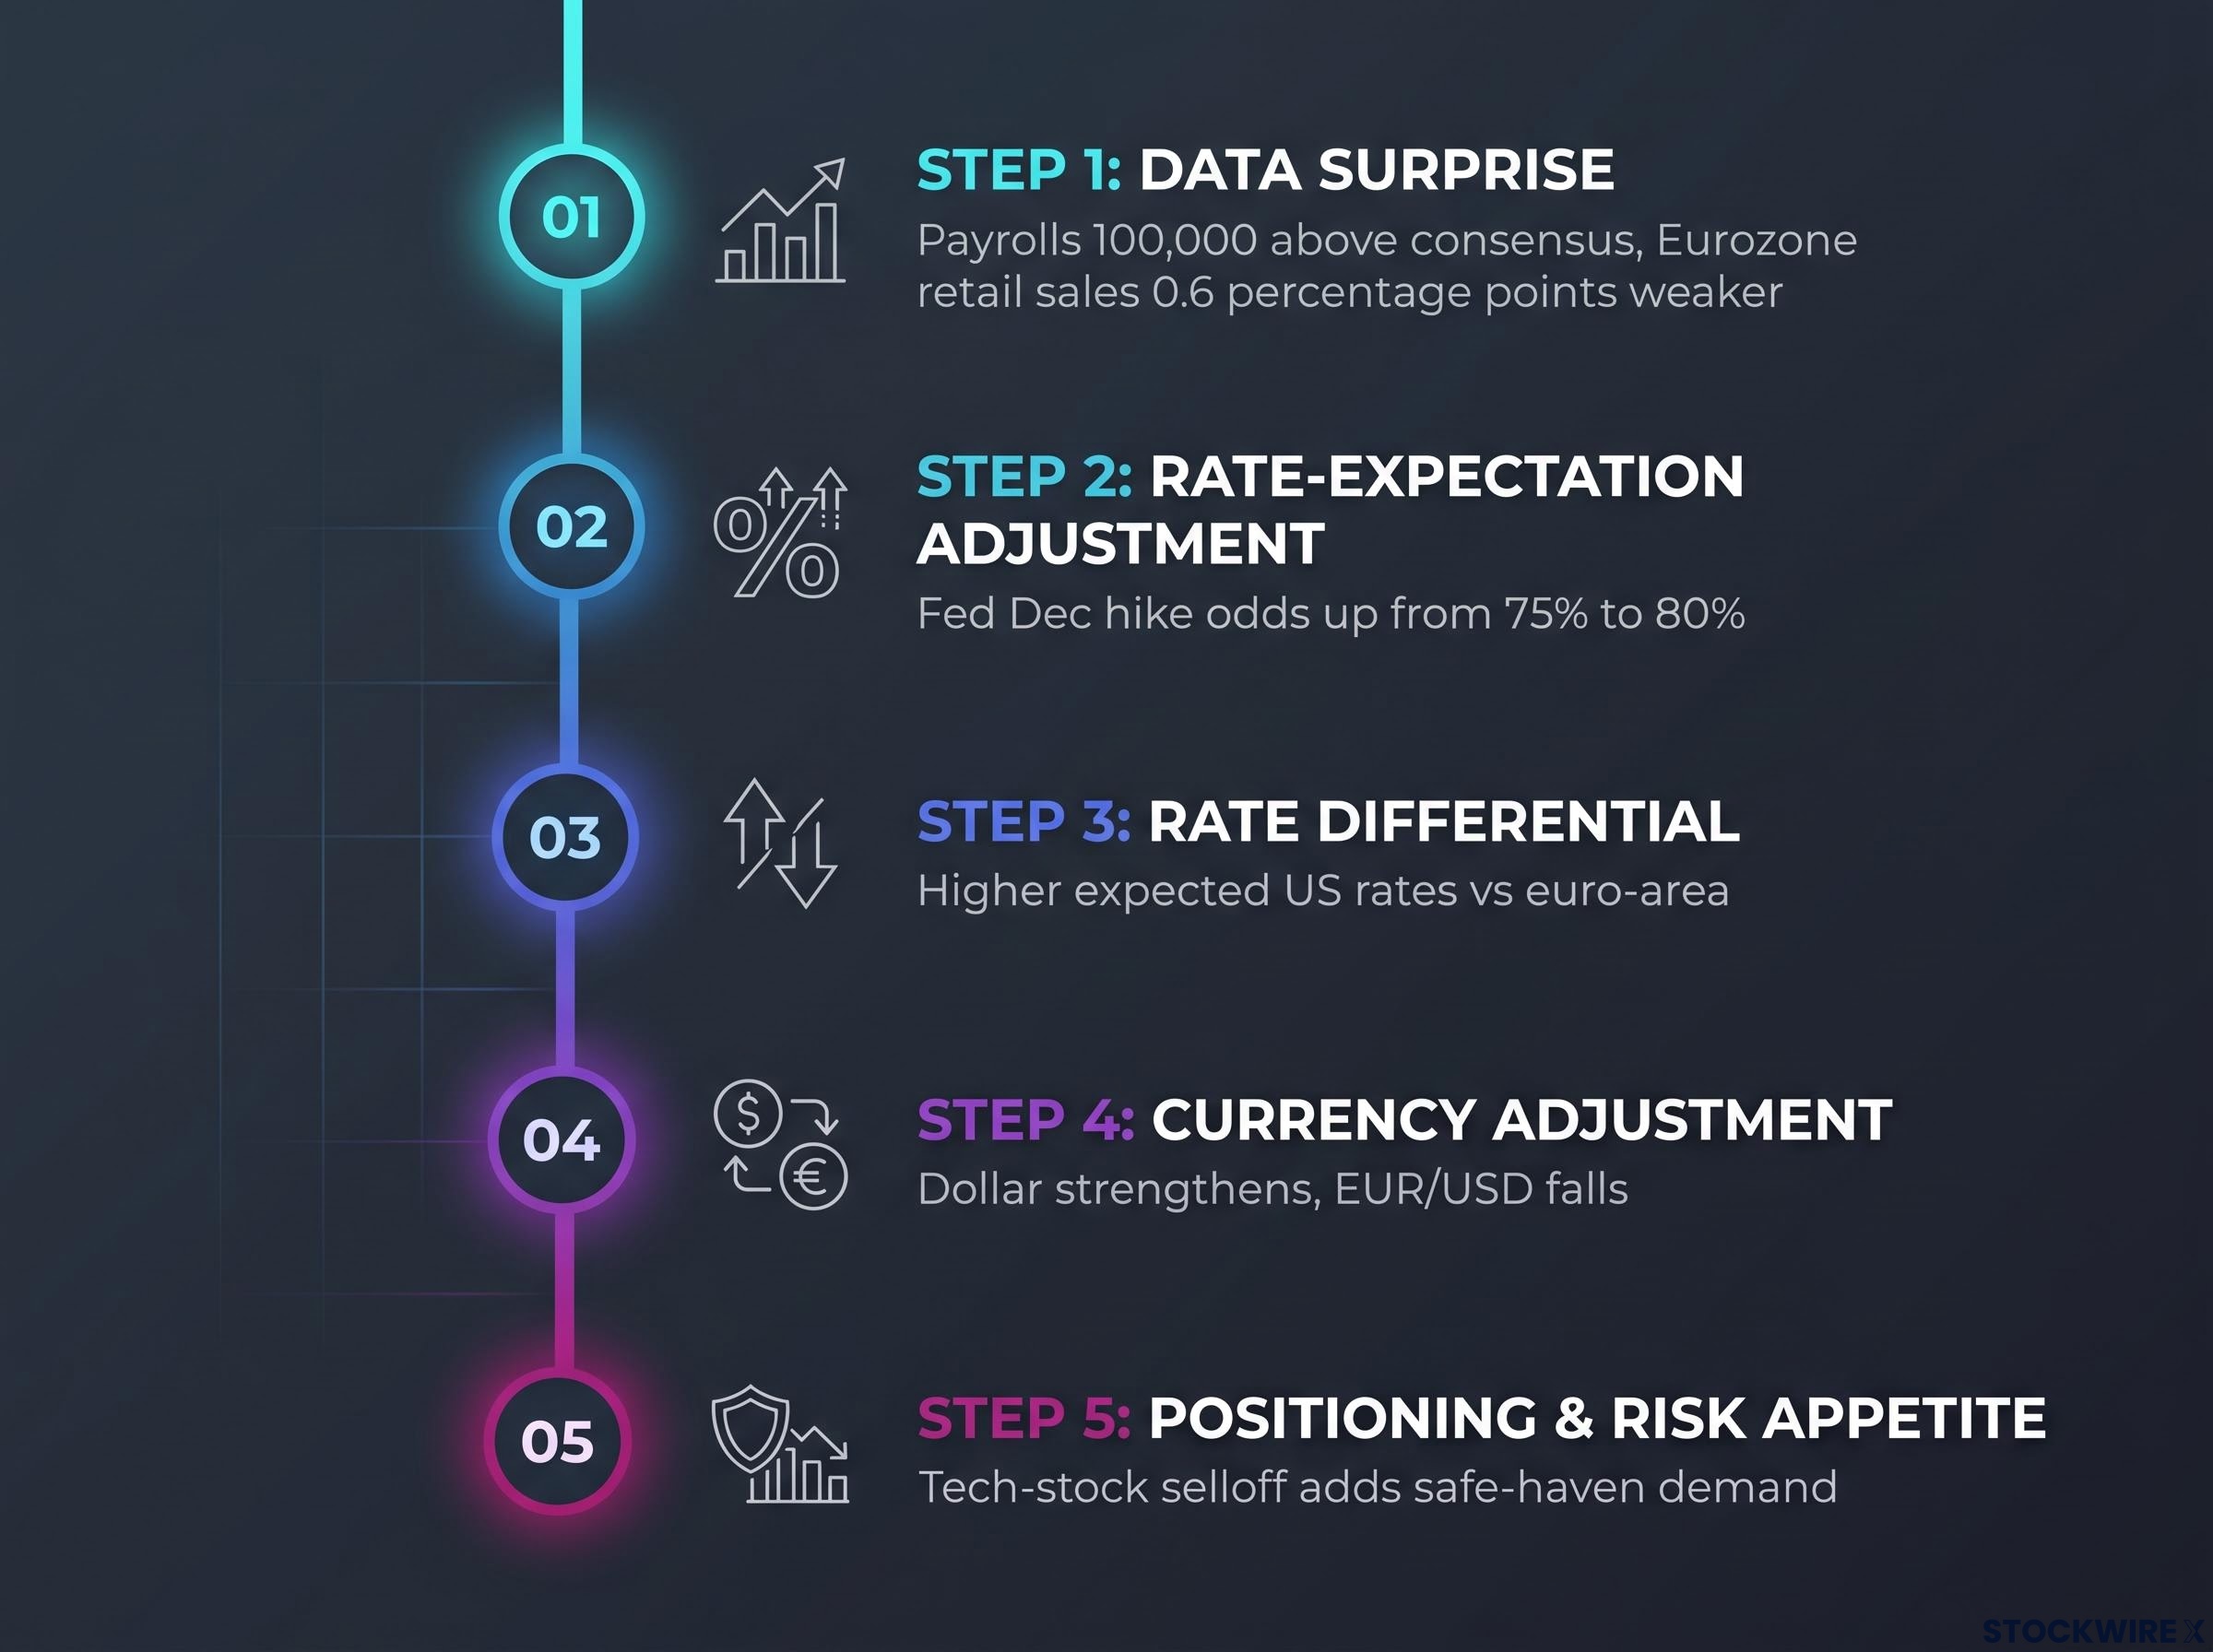
A strong US jobs beat shifted Fed December hike odds from 75% to 80%, widening the rate differential and pushing EUR/USD lower.
- Data surprise. Payrolls came in 100,000 above consensus, and Eurozone retail sales were 0.6 percentage points weaker than the monthly forecast.
- Rate-expectation adjustment. Traders raised the probability of a Fed hike in December to about 80% from about 75%, per Reuters, which said the report gave the Fed more room to focus on inflation. Other market snapshots ranged from about 66% to 79%, so treat the figure as indicative.
- Rate differential. A rate differential is the gap between interest rates in two economies. Higher expected US rates relative to euro-area rates raise the return you could earn holding dollar assets.
- Currency adjustment. Money flows towards the higher expected return, so the dollar strengthens and EUR/USD falls. Before the release, MUFG said its strategy was to buy meaningful dollar dips if payrolls beat expectations.
- Positioning and risk appetite. A global technology-stock selloff added safe-haven demand for the dollar, according to ING and Reuters commentary. ING’s Chris Turner had argued that US Treasuries were resuming their safe-haven role and that decent payrolls would support short-dated US rates and the dollar.
Morningstar described the payrolls gain as materially above forecast, pointing to the lower unemployment rate and upward revision as evidence the labour market was stronger than thought. Those are commentators’ readings, not settled fact, but they line up with each link in the chain.
Treasury yields at their highest since 2007 made the preceding payrolls report unusually sensitive, since each print moved October Fed hike odds and amplified the safe-haven demand now supporting the dollar.
The practical takeaway is simple. When you see a release, ask first how far it missed consensus, and second which central bank it forces to reprice. Those two answers tell you which way the currency is likely to lean.
Fed vs ECB in December: both are priced to hike, so why did the dollar win?
The tidy story you might expect, “Fed tightens, ECB eases”, does not fit the evidence. Both banks were priced for a December hike. The difference lies in how surprised markets were and how much room each bank has to act.
The Federal Reserve
According to Kaohoon International, the Fed set its target range at 3.75%-4.00% at its 29 October decision, a figure not independently confirmed. Most Fed officials view the labour market as resilient, and the bank remains committed to its 2% inflation target.
Inflation risks lean upward, with higher energy costs tied to the Middle East conflict a key concern. Friday’s report shifted December odds from about 75% to about 80%, per Reuters, which suggests the US economy may be able to absorb higher rates.
The European Central Bank
The ECB held rates unanimously on 29 October, saying it was data-dependent and would decide meeting by meeting. Markets still put December hike odds at about 85%-89%, according to Morningstar and Trading Economics.
Its problem is closer to stagflation, where rising prices meet stalling growth. Energy-driven inflation argues for tighter policy, while weak consumption argues for caution.
ECB President Christine Lagarde said in Milan on 5 November that incoming data and updated projections would decide whether a December hike is needed, adding that the energy shock was lifting inflation while weakening growth. On Friday, Chief Economist Philip Lane said inflation must return to target within a year or two, that financial conditions had already tightened, and that policymakers would gather information before December.
| Measure | Federal Reserve | European Central Bank |
|---|---|---|
| Latest decision | 29 October, range reported at 3.75%-4.00% | 29 October, unanimous hold |
| December hike odds | About 80% (Reuters) | About 85%-89% |
| Key concern | Upward inflation risk from energy | Energy inflation against weak consumption |
| Latest official comment | Labour market seen as resilient | Lagarde and Lane: data will decide |
So read the dollar’s rise this way: the US outcome was less anticipated, while an ECB hike was already largely priced in. The euro simply had less fresh news working in its favour.
Central bank divergence has produced large currency swings before: in 2022, the Fed’s faster rate path pushed EUR/USD below parity even as the ECB hiked, because markets priced the whole future path rather than any single decision.
What could change the EUR/USD outlook before December?
The causal story is neat, but several things could unsettle it. Keep these on your watch list:
- Payroll revisions. September jumped from 29,000 to 60,000, so a downward revision to October could soften the apparent strength.
- Slowing annual wages. Growth eased to 3.1%, which offers less support for a wage-driven inflation story than the headline jobs number implies.
- First-estimate retail data. Eurostat’s September figure is preliminary, and one weak month does not prove a lasting slump in household demand.
- The energy shock cuts both ways. It weakens euro-area growth, yet persistent energy inflation could push markets to price more ECB tightening, limiting EUR/USD downside.
- Risk aversion, not just payrolls. Part of the dollar’s gain was attributed to the tech selloff, which could fade independently of the data.
- Technical levels. Market commentary, not independently verified, flags the break below 1.12 as a bearish signal, with a recovery above it weakening that reading, and DXY resistance near 102.00-102.20 with support near 101.50.
Lagarde on the energy shock The ECB President said the duration of the Middle East-related energy shock is hard to assess and that it may last longer than expected.
No close historical parallel to this combination of a big US jobs beat and weak Eurozone retail sales turned up in the research. Treat Friday as a single episode rather than a pattern, and hold any EUR/USD forecast as conditional on revisions, energy prices and the ECB’s meeting-by-meeting stance.
These statements are speculative and subject to change based on market developments. This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
Reading the next release: what Friday’s slide teaches about euro and dollar moves
Friday showed that two hawkish central banks do not cancel each other out. The currency follows whichever side delivers the bigger surprise.
The framework stays the same each time: measure the surprise against consensus, ask which central bank it forces to reprice, follow the change in the rate differential, then check whether risk appetite is amplifying the move.
Between now and the December decisions, run that test on each catalyst:
- The next US payrolls report and any revision to October
- Fresh Eurozone data, especially consumption and inflation
- Further remarks from Lagarde and Lane
- The path of energy prices tied to the Middle East conflict
Each one will tell you whether Friday’s dollar strength had staying power, or whether the euro’s December case is quietly rebuilding.
Readers interested in the energy variables behind ECB policy can turn to our full explainer on the ECB rate outlook, which separates oil as the September driver from gas as the December one.