
Monvia outlines $14m ARR and FY27 growth priorities in investor update
In its 5 November 2026 investor presentation, Monvia outlined annual recurring revenue (ARR) of $14m at 1 July 2026, up 21% year-on-year, alongside FY26 adjusted EBITDA of $6.9m against a $6.6m forecast.
Monvia describes itself as an Australian enterprise SaaS provider for the core operations of life insurers. The presentation noted a private acquisition and business transformation under new leadership in July 2025, that the company completed its IPO and listed on the ASX in July 2026, and that the FY26 results were released after the IPO, reporting performance above forecasts and a stronger balance sheet.
When big ASX news breaks, our subscribers know first
FY26 results beat the prospectus forecast
Financial highlights
Management highlighted adjusted revenue and EBITDA that exceeded forecast. The figures are presented on a pro forma like for like basis to the prospectus financial information, as referenced to the “FY26 Annual Results Presentation” released on 26 August 2026.
| Metric | FY26 result | Comparison |
|---|---|---|
| Adjusted revenue | $27.7m | 1% above prospectus forecast |
| Adjusted EBITDA | $6.9m | Versus $6.6m forecast; 24.9% margin versus 24.0% forecast |
| Pro forma net cash | $5.1m | $11.1m pro forma cash and $6.0m pro forma debt |
| ARR at 1 July 2026 | $14m | 21% year-on-year growth |
Pro forma cash is the reported cash balance adjusted for IPO receipts and payments, the Series B preference shares redemption, and overdue customer receipts due to contract renewal. ARR is contracted revenue at 1 July.
ARR and customer metrics
The ARR scorecard showed existing clients underpinning recurring revenue growth:
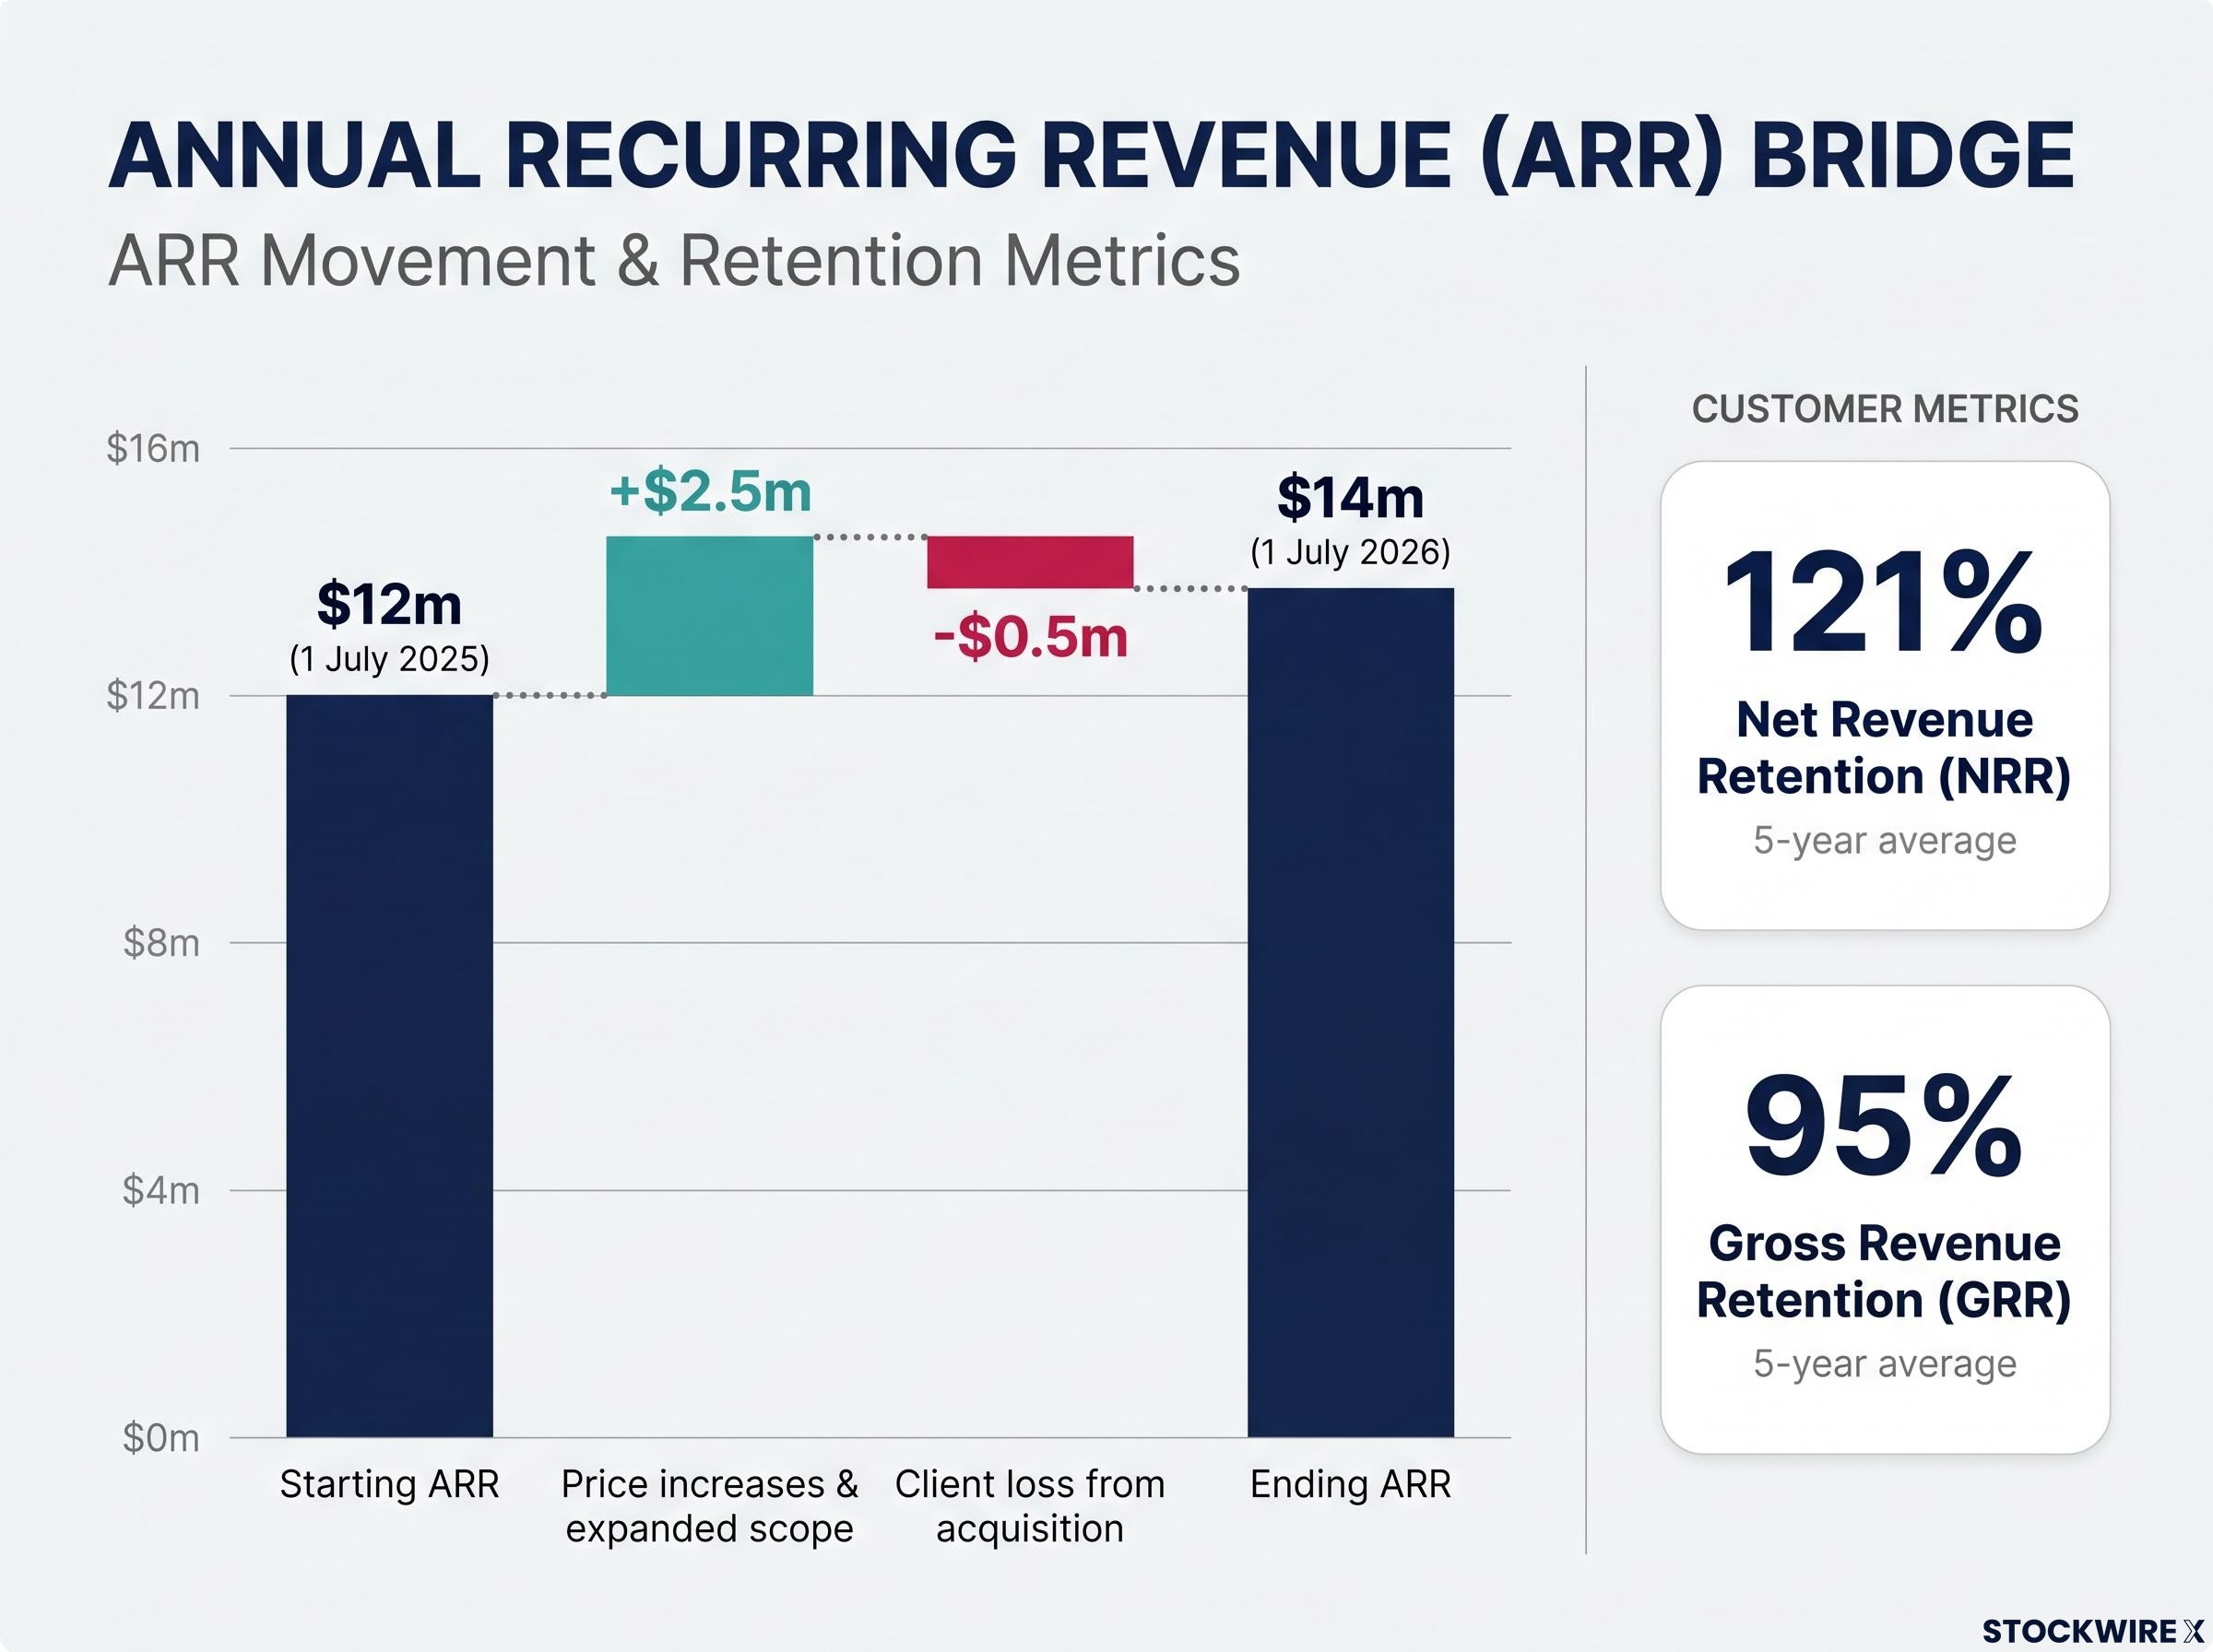
- ARR rose from $12m at 1 July 2025 to $14m, including $2.5m from price increases and expanded scope, offset by a $0.5m reduction from one client loss, where the client was acquired.
- Five-year ARR compound annual growth rate (CAGR) to 1 July 2026 was 28%.
- Recurring revenue was 43% of total revenue in FY26, compared with 39% in FY25.
- ARR per employee in the product and technology team was $404k, flat against 1 July 2025.
The customer scorecard added further detail:
- Net revenue retention (NRR) was 121% and gross revenue retention (GRR) was 95%, both 5-year averages.
- FY26 customer churn (ARR) was 4.1%, described as the first client exit in three years, as a result of the client being acquired.
- Customer concentration (ARR) was 62% for the largest client at 1 July 2026, up from 48% at 1 July 2025.
- MetLife renewed for five years from April 2026 with ARR growth.
Concentration is the key consideration here, alongside the high switching costs the company says are attached to its embedded core systems.
For readers wanting the earnings detail behind these metrics, our full explainer on Monvia’s maiden FY26 results examines the cash flow position and the absence of new-logo ARR in the debut reporting period.
How the Monvia Life Platform works
Three metrics feature heavily in the presentation. ARR is contracted revenue at 1 July. NRR divides ARR at the end of a period by ARR at the start, reflecting expansion from existing customers net of contraction and excluding new-logo customers. GRR divides ARR retained from customers active at the start of the period by their starting ARR, excluding expansion and new-logo ARR.
Switching costs matter because Monvia’s core systems serve enterprise insurance and government clients, and the company says these relationships carry high switching costs.
The Monvia Life Platform is described as one configurable enterprise platform for life insurers, reinsurers and superannuation funds. It comprises:
- New Business
- Policy Administration
- Claims Management
- Hub
Monvia states the platform is native cloud software on AWS, with rules-based configuration for each insurer. Insurers can modernise in stages, building on existing systems. The commercial model is SaaS, with enterprise licences or transaction-based pricing, underpinned by enterprise-grade managed services.
The company was founded in 1997 and has 108 people, with headquarters in Sydney and teams in Australia, New Zealand and the Philippines. It serves 6 enterprise clients with tenure of 5-18 years. The leadership team is the former Empired leadership team, which achieved an A$250m cash exit in 2021.
Four growth pillars and FY27 outlook
Progress and next milestones
Management framed the outlook around four growth pillars.
| Pillar | Progress | Next milestones |
|---|---|---|
| Accelerate ARR Growth | Focused product development and services design leading to 21% ARR growth in the current client base | 1. Launch expanded offers for products and services; 2. Focus on value for existing clients, leveraging AI to deliver more for the same |
| Win New Clients | 3.5x growth in pipeline with multiple new enterprise opportunities | 1. Convert ANZ pipeline; 2. Grow Southeast Asia pipeline; 3. Grow Australian super fund pipeline |
| Strategic Partnerships | Signed Capgemini Teaming Agreement for ANZ insurance and superannuation opportunities | 1. Progress joint opportunities with Capgemini; 2. Add one more partner for market coverage |
| Technology & AI Investment | Monvia Claims Summarisation now in production | 1. Bring to market a multi-channel claims offering; 2. Superannuation ‘single pane of glass’ claims solution; 3. AI connectivity to the Monvia Life Platform |
FY27 outlook as stated by management
The presentation described New Enterprise Client Opportunities and ARR growth as shaping FY27 as a “company-making year”. Formal RFP processes are underway, with the pipeline up 3.5x over FY25. Management’s stated outlook:
- Anticipate strong ARR growth against pcp at full year end.
- FY27 recurring revenue to be up and professional services to be modestly down, leading to flat total revenue against pcp.
- Revenue H2 weighted, providing confidence in FY28 ‘run-rate’ revenue.
- Full year EBITDA expected to be modestly up on pcp, with H1 EBITDA expected to be flat and H2 EBITDA expected to be up on pcp as a result of strengthening recurring revenue in H2.
The company’s stated key focus is to deliver recurring revenue through client expansion and new logos.
The Capgemini teaming agreement runs for an initial three years before renewing in one-year periods, and revenue only becomes committed once opportunity documentation and subcontracting arrangements are executed.
What happens next for Monvia
Several items flagged in the presentation will shape how FY27 unfolds. None carried dates beyond the periods noted.
- FY27 half-year split: H1 EBITDA is expected to be flat on pcp and H2 EBITDA expected to be up on pcp.
- Full year FY27 outcomes: strong ARR growth is anticipated, with flat total revenue and full year EBITDA expected to be modestly up against pcp.
- Product milestones: a multi-channel claims offering, a superannuation ‘single pane of glass’ claims solution and AI connectivity to the Monvia Life Platform.
- Partnerships and pipeline: progress joint opportunities with Capgemini and add one more partner, while converting the ANZ pipeline.
Get Tech News Before the Market Moves
Join 20,000+ investors receiving FREE breaking ASX tech news within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to get the next market-moving update the moment it breaks, and stay ahead of the crowd.