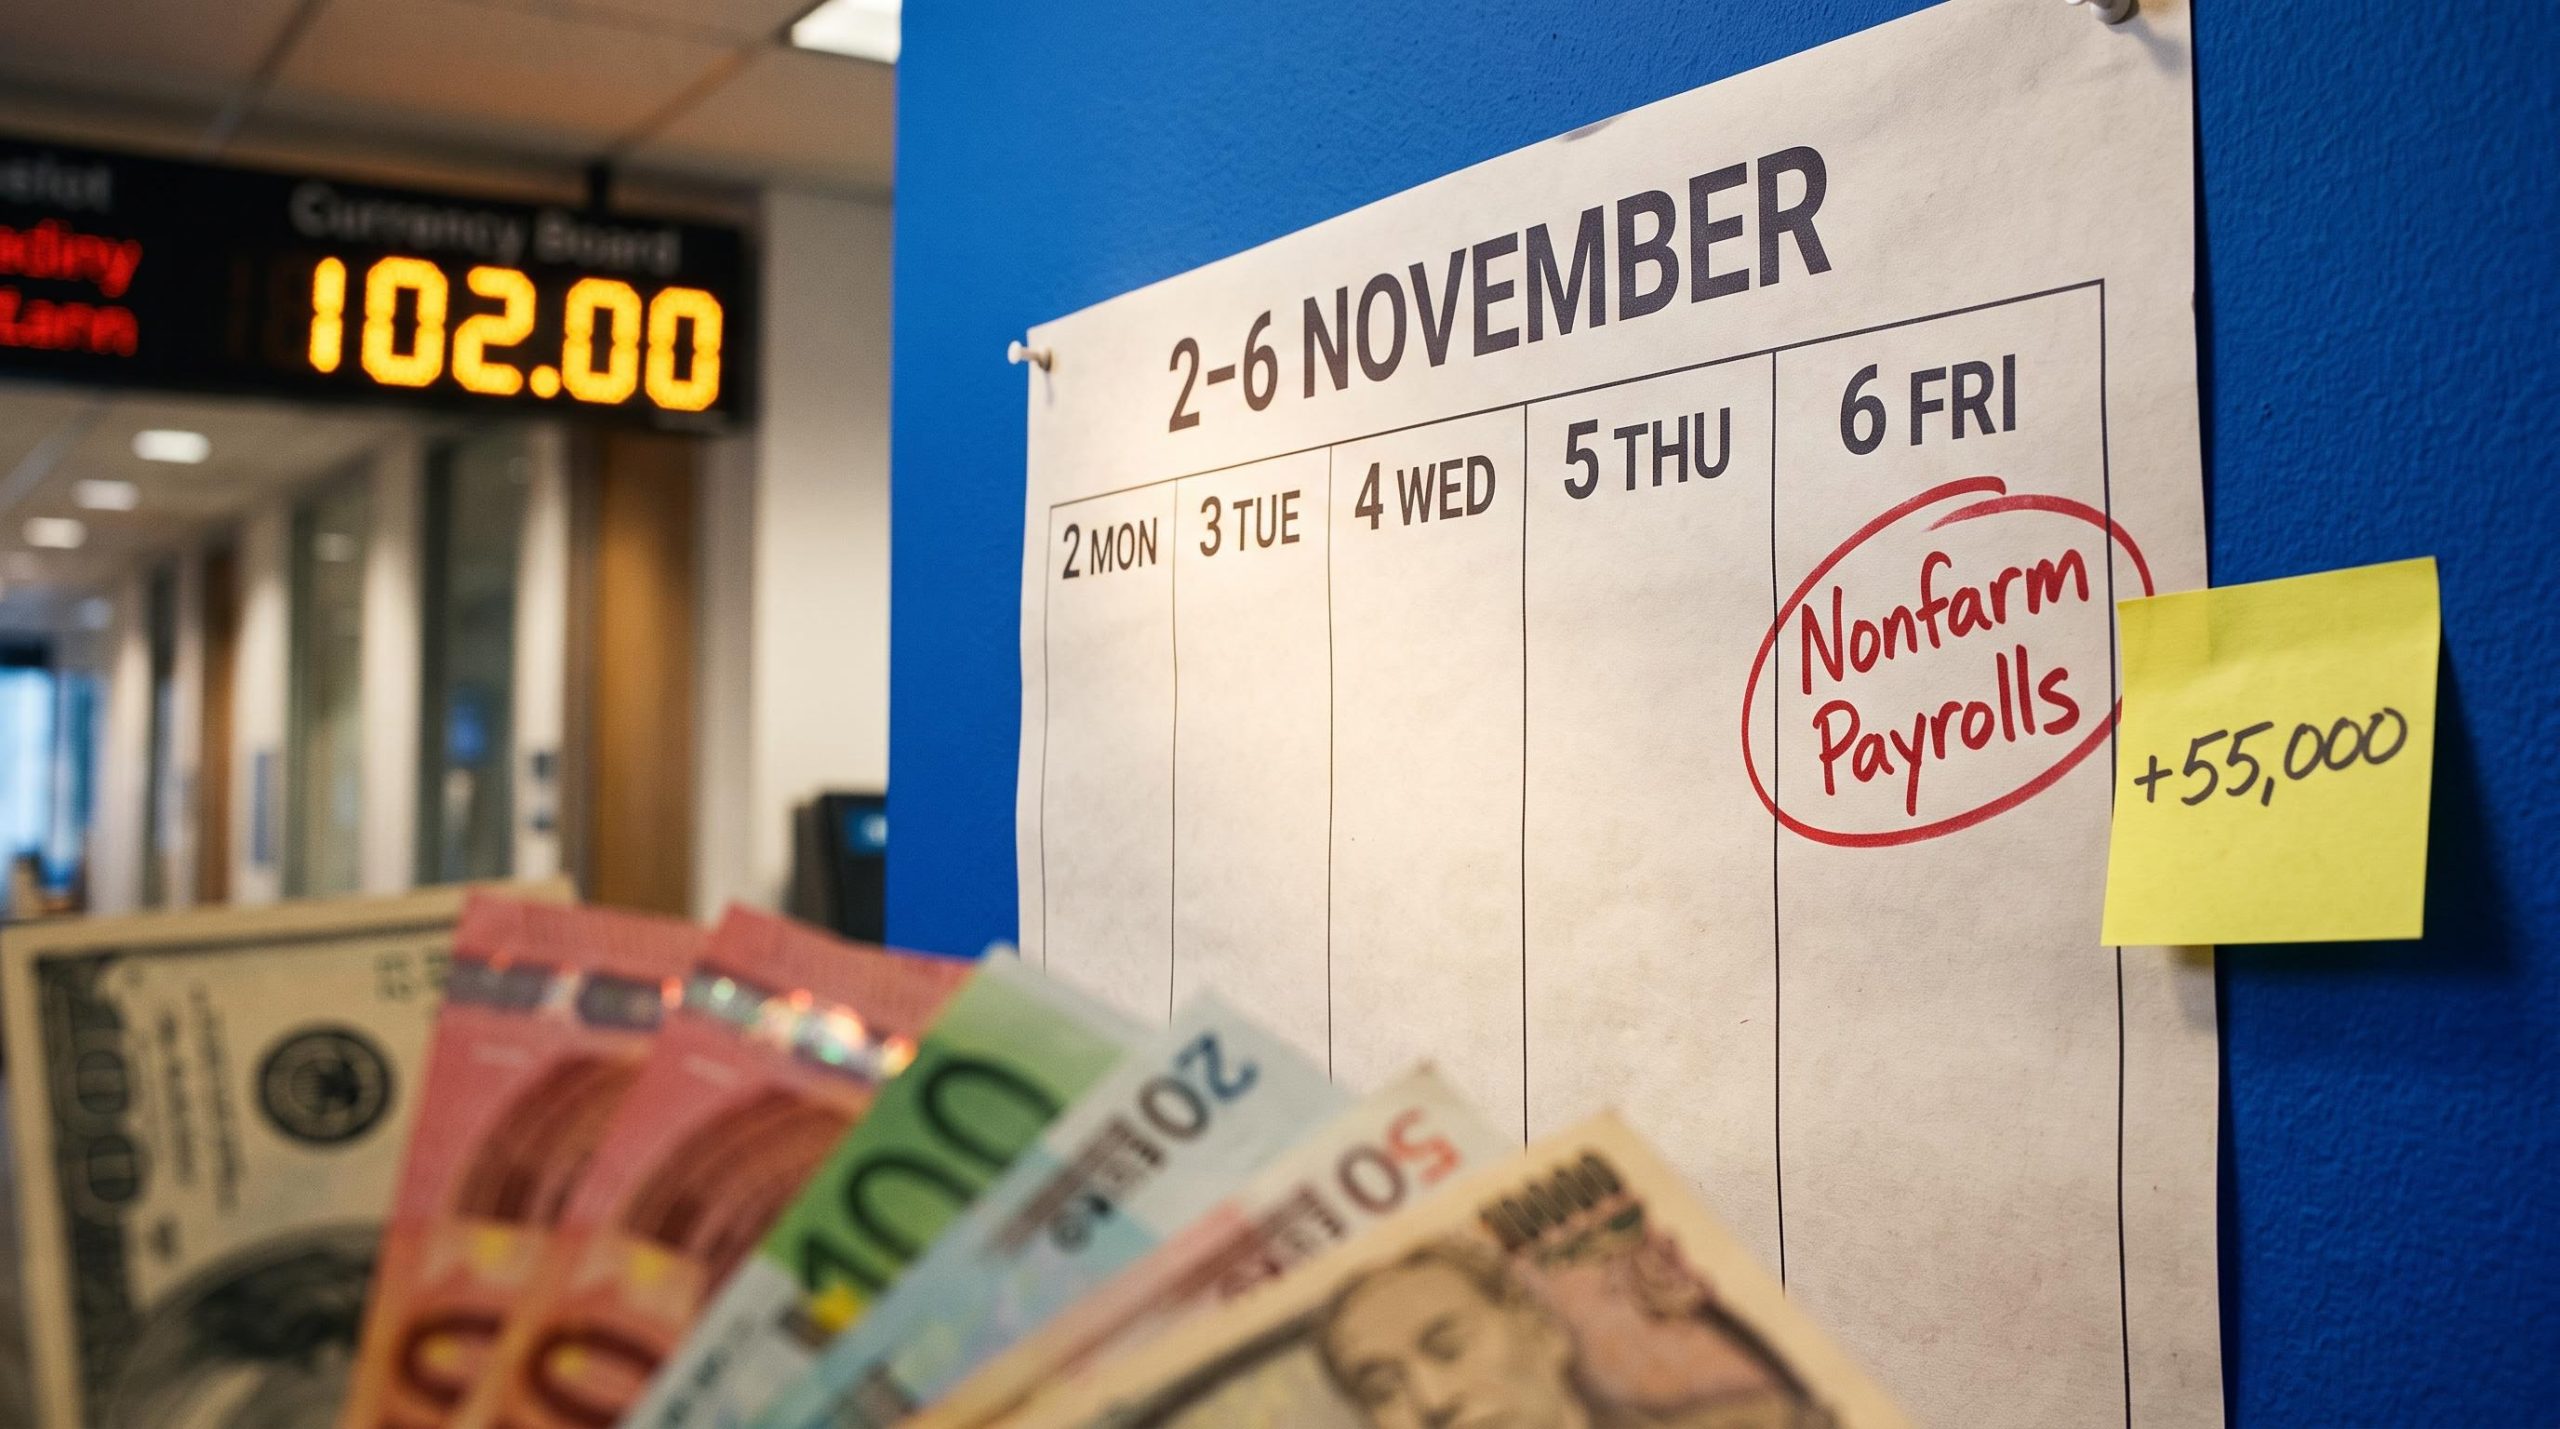
The Federal Reserve held rates on 28 October, and plenty of traders filed that under “dovish”. The currency market read it the other way. The US Dollar Index (DXY), which tracks the dollar against six major currencies, rebounded to roughly 102.00 and finished the week sitting near its 200-week moving average.
That gap between the headline and the market’s reaction is the signal to carry into the week ahead in forex. A pause that comes with two dissenters wanting a hike is not a pause in the usual sense.
The calendar for 2-6 November is crowded. Brent crude sits above US$116, three central banks are expected to raise rates by 25 basis points each, US midterm results start landing on Tuesday and Nonfarm Payrolls close the week on Friday. Each of these events moves different currency pairs in different ways.
Here is a framework for reading each release as it lands, plus the specific setups for EUR/USD, GBP/USD, USD/JPY and AUD/USD. The aim is simple: you go into each session knowing which outcome matters and why.
Why is the dollar rebounding into the week, and what could reverse it?
The dollar ended two weeks of declines with a rebound that took the DXY to a weekly peak near 102.50 before it settled around 102.00. According to TalkMarkets, the 200-week simple moving average sits near 101.6-101.7. This is the average closing level over roughly four years, and it is a level many traders treat as a long-term dividing line.
Three forces are pushing in the same direction:
- Safe-haven demand: The unresolved Middle East crisis lifts demand for dollar liquidity and US assets.
- The oil-inflation channel: MUFG’s Edward Bell and Soojin Kim put December Brent above US$116 after it touched almost US$118 early on 30 October. WTI traded near US$101 on 29 October. Expensive oil raises expected inflation and pushes back hopes of Fed rate cuts.
- The rate differential: The Fed’s hawkish hold raised the perceived odds of another hike, which supports Treasury yields and the dollar.
The detail that turned a pause into a hawkish signal was the vote. The Fed held its target range at 3.75%-4.00% by 10-2, with Lisa Cook and Cleveland Fed President Beth Hammack voting for a 25 basis point hike. The statement also upgraded its view of growth to “strong”.
What the Fed said The statement described inflation as one that “remains elevated”, and Chair Kevin Warsh said the Fed remained committed to its 2% inflation goal.
Goldman Sachs Asset Management’s Kay Haigh expects the pause to be short-lived and sees a possible resumption of hikes in December, according to Newsquawk. If you are positioned long or short the dollar, this rebound tells you markets are pricing more Fed tightening, not a one-off hold.
The rate differential matters because interest rate differentials, together with US growth strength and the dollar’s reserve currency role, explain why the market can keep the dollar bid even when no new hike has been delivered.
What would reverse the rebound
The three drivers reinforce each other, which also means they can unwind together. Oil is the hinge. High oil can be read as inflationary, which helps the dollar, or as a drag on US and global growth, which hurts it.
Three developments would break the case: oil retreating, diplomacy lowering Middle East risk, or markets deciding the October hold is simply a pause. There is a recent precedent. Reuters documented an earlier dollar slip when oil fell back and traders reassessed the Fed outlook.
When big ASX news breaks, our subscribers know first
How do data and policy events move major currency pairs?
The core logic is short. Economic data shifts expectations for growth and interest rates, those expectations move bond yields, and money tends to flow towards the currency offering the better yield.
The headline number matters less than the surprise. Consensus is the average forecast economists publish before a release, and markets price it in ahead of time. A payroll print of 80,000 can lift the dollar if the market expected 55,000, and the same print can sink it if the market expected 120,000.
Central bank decisions work the same way. A rate hike that everyone expects is already in the price, so the guidance on what comes next often moves the currency more than the hike itself.
| Event | Transmission | Likely reaction |
|---|---|---|
| Strong US payrolls | Higher expected growth, yields and Fed tightening | Dollar higher; USD/JPY higher unless intervention fears dominate |
| Weak US payrolls | Lower expected Fed rates and yields | Dollar lower; EUR/USD, GBP/USD, AUD/USD higher |
| Strong ISM | Resilient demand, higher-for-longer pricing | Dollar-positive |
| Weak PMIs | Slowing activity, lower expected rates | Dollar-negative, unless risk aversion lifts safe-haven demand |
| RBA hike | Higher Australian yields, carry demand | AUD/USD higher, though oil-driven risk aversion can offset |
| Riksbank hike | Wider Swedish krona rate differential | EUR/SEK lower; limited EUR/USD effect |
| BoE hike | Higher UK yields if seen as a durable cycle | GBP/USD higher; a dovish hike could push sterling lower |
| Higher oil | Global inflation and risk aversion rise | Possibly AUD-positive at first; dollar-positive if safe-haven demand dominates |
Take the Bank of England. A hike helps sterling only if traders see it as the start of a lasting cycle. A “dovish hike”, where the bank raises rates but signals it may stop there, can push the pound lower on the day.
When the usual rule breaks
Weak data does not always sink the dollar. If fear dominates, investors buy dollars for safety regardless of what the numbers say.
Payroll revisions can also flip the reaction. A weak headline with large upward revisions to earlier months, or a strong headline with downward revisions, can send the dollar the opposite way to the first print.
Before the week starts, write down for each event which outcome would be dollar-positive. You then react to a surprise against your notes rather than to a headline.
Which US releases matter most from Monday to Friday?
Everything from Monday to Thursday is setting the stage for one number on Friday. Here is the US schedule in order:
- Monday 2 November: ISM Manufacturing PMI, final S&P Global Manufacturing PMI, construction spending.
- Tuesday 3 November: JOLTS job openings, factory orders, midterm election results begin arriving.
- Wednesday 4 November: ADP private payrolls, ISM Services PMI, trade balance.
- Thursday 5 November: Initial jobless claims, Challenger job cuts.
- Friday 6 November: Nonfarm Payrolls, unemployment rate, preliminary University of Michigan consumer sentiment.
The three highest-impact releases are the ISM surveys, ADP and Nonfarm Payrolls. The midterms add a separate source of volatility for Treasury yields, fiscal expectations and safe-haven flows.
Midterm results also feed into fiscal credibility concerns, which can move long-end Treasury yields and the dollar independently of the data calendar.
| Indicator | Consensus | Prior |
|---|---|---|
| ISM Manufacturing PMI | 54.7 | 54.5 |
| ADP private payrolls | +75,000 (Economic Weekly); +65,000 (Continuum) | +90,000 |
| ISM Services PMI | 54.7 | 54.9 |
| Nonfarm payrolls | +55,000 | +29,000 |
| Unemployment rate | 4.2% | 4.2% |
| Average hourly earnings (m/m, y/y) | +0.3%, +2.9% | +0.1%, +3.0% |
Payroll uncertainty is unusually high this month.
Conflicting payroll calls Newsquawk puts consensus at +55,000, while Continuum Economics and Barclays expect 50,000. Barclays also sees unemployment dipping to 4.1%, and warns that claims-based models point to stronger hiring while other indicators point to weaker hiring, with seasonal adjustment adding risk.
With the consensus this low, a downside surprise is the single most likely trigger for a dollar reversal. Check the revisions before you trust the headline. Fed speakers fill the week too: Goolsbee on Monday, Hammack and Barkin on Thursday, then Logan, Williams, Musalem and Bowman after the payroll release.
What are the RBA, Riksbank and BoE expected to do?
Three central banks are expected to deliver the same 25 basis point hike. The certainty behind each one is very different.
The Reserve Bank of Australia (RBA) decides on 3 November, with a move from 4.60% to 4.85% expected. Money markets priced about 79% odds of a hike against 21% for no change. It would be the fifth hike of 2026, following a unanimous fourth in September, and Australian inflation supports the case: September CPI ran at 4.3% year on year, Q3 CPI at 3.9% and the trimmed mean (which strips out the most extreme price moves) at 3.7%.
Sweden’s Riksbank follows on 4 November, expected to lift its rate from 1.75% to 2.00%. Nordea, SEB, Handelsbanken and ING all backed a hike, but elevated Swedish unemployment raises the risk of softer language alongside it.
The Bank of England (BoE) decides on 5 November, with a 25 basis point move described as an “inaugural tightening”. The open questions are the vote split and the guidance on further hikes, which makes this the decision with the greatest communication risk.
| Bank | Date | Expected move | Key uncertainty |
|---|---|---|---|
| RBA | 3 November | 4.60% to 4.85% | About 21% priced for no change |
| Riksbank | 4 November | 1.75% to 2.00% | Less-hawkish package given unemployment |
| BoE | 5 November | 25 bp hike | Vote split and forward guidance |
Elsewhere, Poland’s central bank, Norges Bank, Bank Negara Malaysia and Banxico are expected to hold. ECB President Christine Lagarde, Isabel Schnabel and Philip Lane speak on 5 November, and the BoE’s Huw Pill on 6 November.
A hike that is already priced tells you little. Watch the vote split and the guidance, because they decide whether the currency rallies or sells the news.
What are the setups for EUR/USD, GBP/USD, USD/JPY and AUD/USD?
Each pair has a level, a trigger in each direction and its own local calendar. These are conditional scenarios, not predictions, and they can change quickly with market developments.
EUR/USD
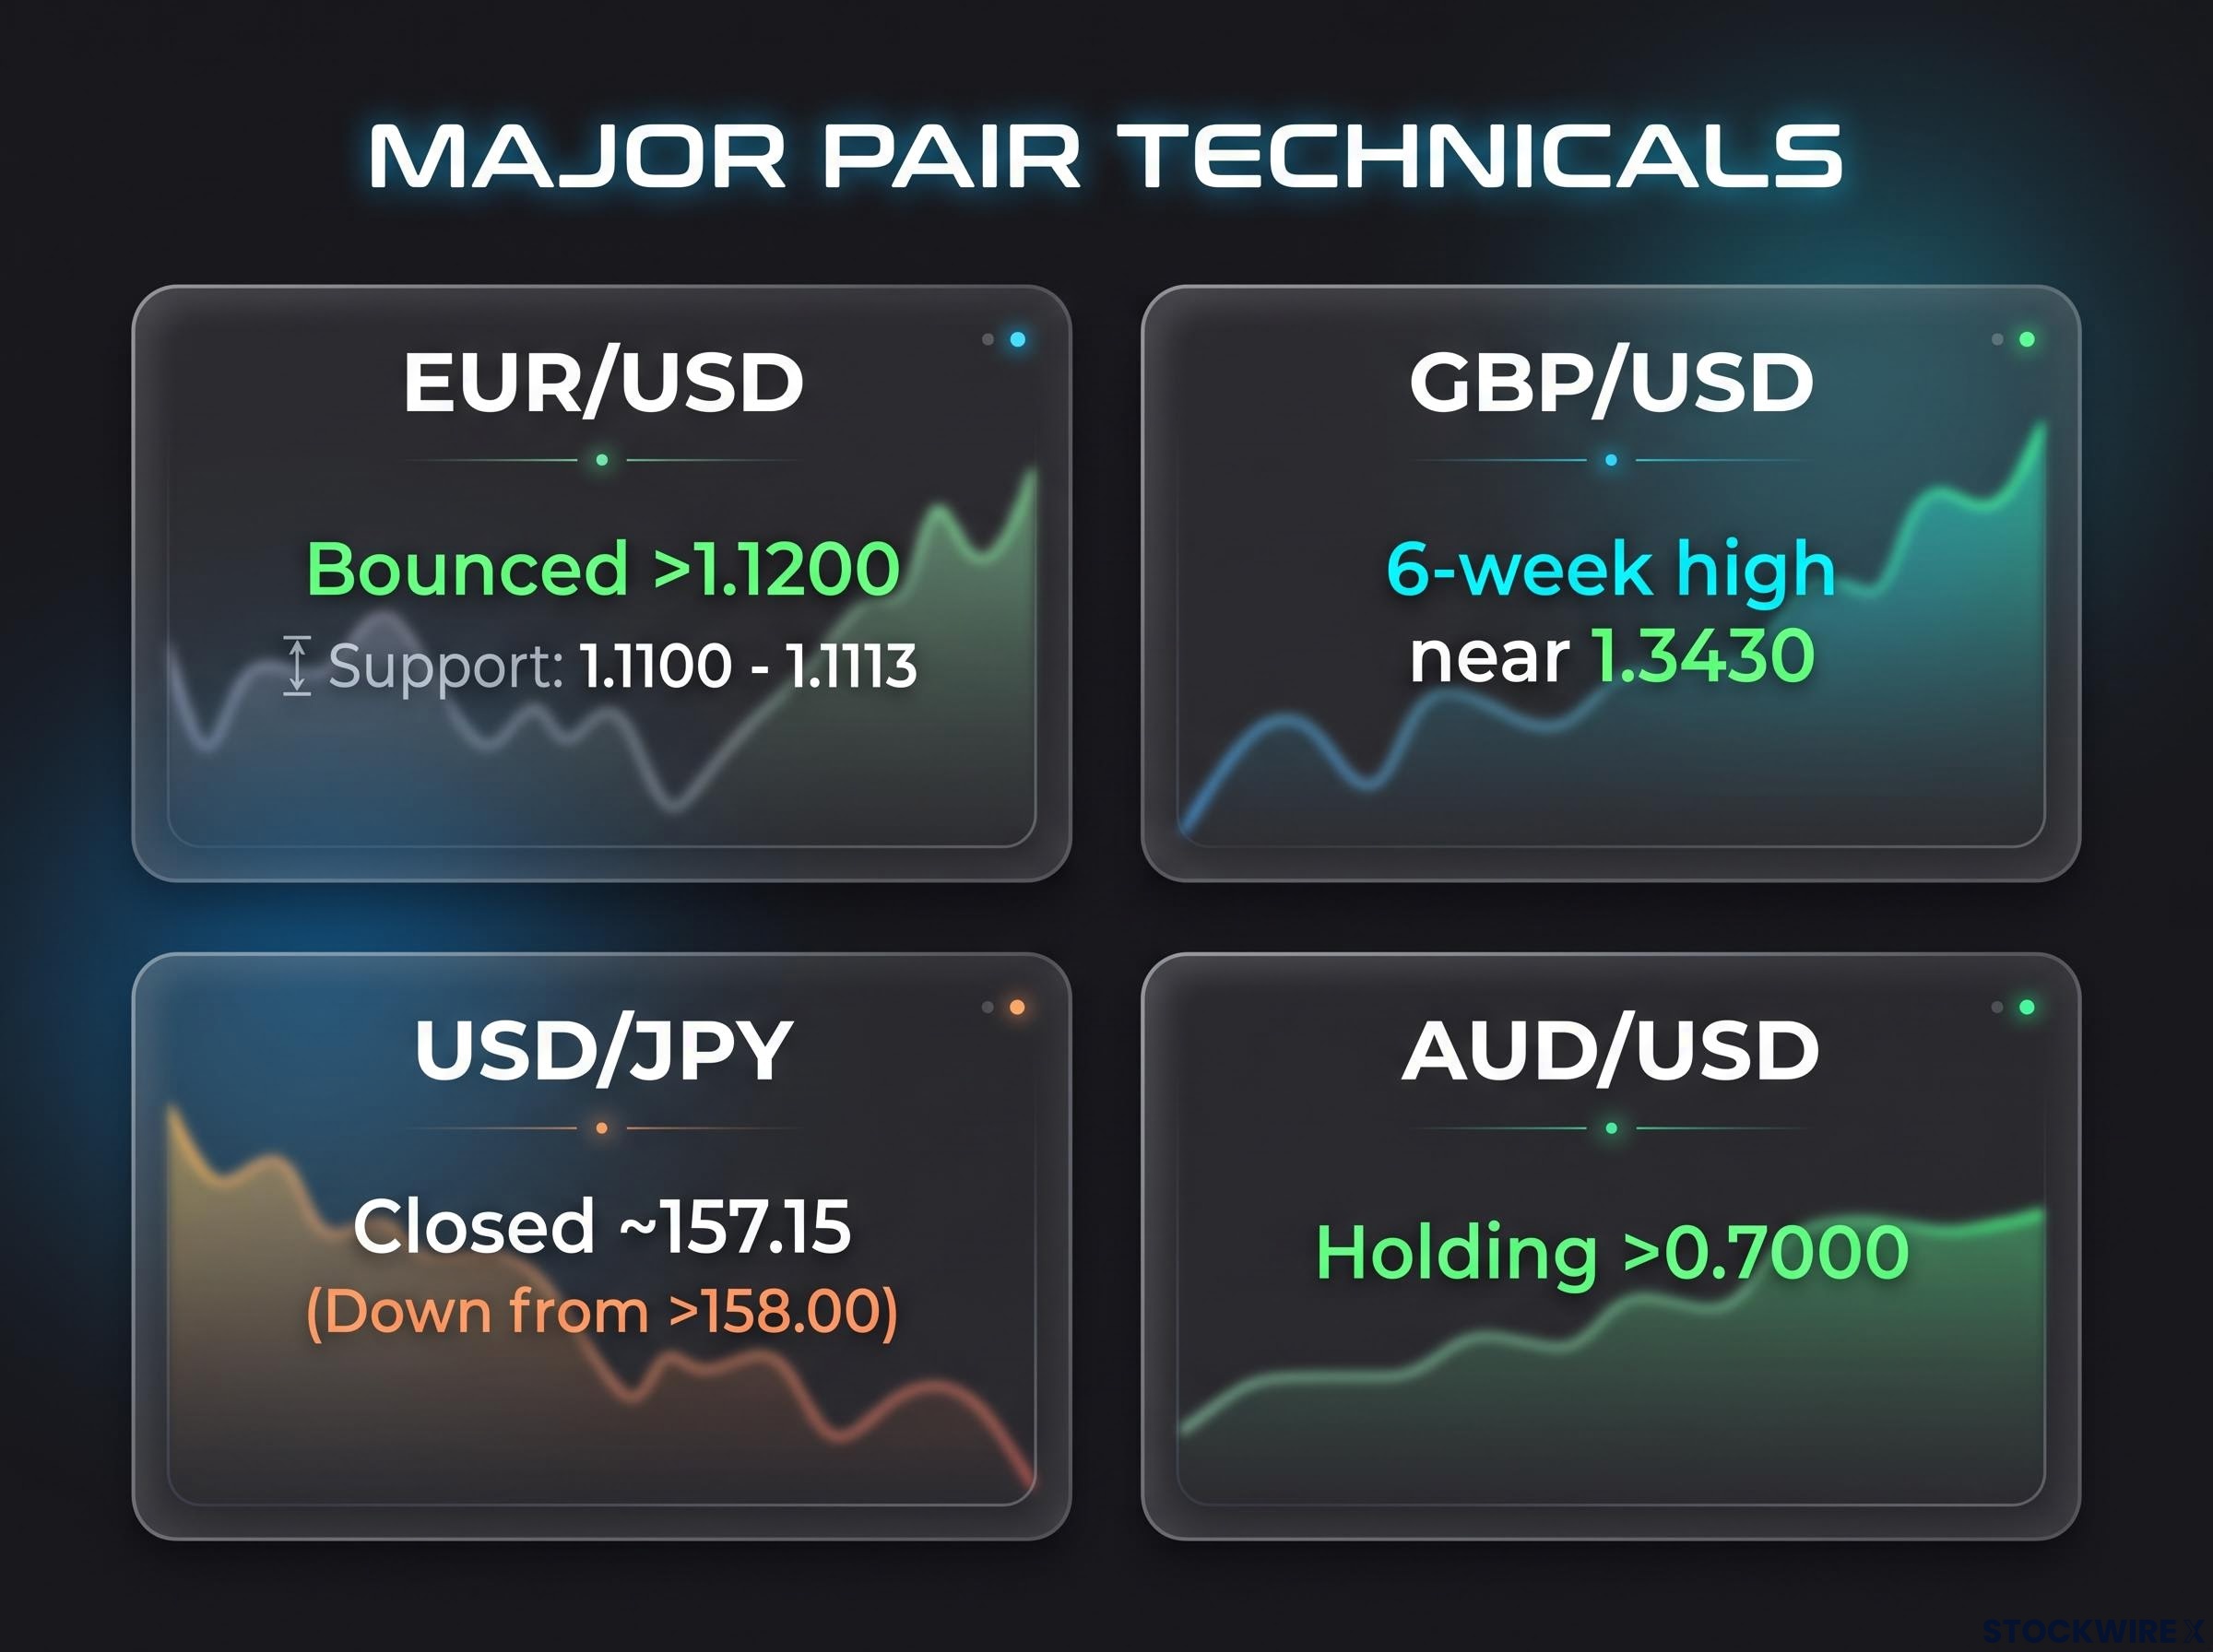
The euro hit near 17-month lows, retested 1.1100 and bounced above 1.1200 on Thursday. This is the most clearly defined technical test of the week.
- Support zone: 1.1100-1.1113, combining the 14 October low and the 200-week average near 1.1105.
- Local catalyst: Preliminary eurozone inflation on 4 November.
A defence of that zone on weak payrolls or lower oil could spark a sizeable bounce. A break would reinforce the bearish trend.
The euro’s weakness reflects Fed-ECB policy divergence, with the US-German 2-year yield spread acting as a key quantitative driver behind EUR/USD alongside local catalysts such as eurozone inflation.
GBP/USD
Sterling rose for a third straight week to a six-week high near 1.3430.
- Local catalysts: UK services PMI on 4 November, BoE decision on 5 November.
A hawkish vote split could extend the run. A dovish hike could erase the rate advantage sterling has been trading on.
USD/JPY
The pair closed around 157.15, per FXStreet, down from above 158.00.
- Local catalysts: BoJ Minutes and services PMI on 5 November.
The wide US-Japan yield gap favours a move higher. Near 157, though, a disorderly yen slide raises the risk of Japanese intervention, which is the main variable here that no data release controls.
AUD/USD
The Aussie edged up and is holding above 0.7000.
- Local catalysts: RBA on 3 November, trade balance on 5 November.
A hike to 4.85% supports carry demand. China or global-growth worries, or a risk-off oil shock, could overwhelm that benefit.
| Pair | Bullish case | Bearish case |
|---|---|---|
| EUR/USD | Weak payrolls, softer ISM or lower oil spark a rebound from 1.1100-1.1113 | Hawkish Fed and safe-haven demand break the 200-week average |
| GBP/USD | BoE hike with a hawkish vote split | Dovish hike or weak growth guidance |
| USD/JPY | Wider yield gap and safe-haven demand push above low 157 | Intervention, weak payrolls or lower yields |
| AUD/USD | RBA hike to 4.85% and price holding above 0.7000 | Growth worries, risk-off oil shock, hawkish Fed |
Use this table to decide in advance which level or data print would change your view on each pair. That beats improvising when volatility hits.
Building your own plan for a heavy-calendar week
The bias for 2-6 November leans towards a supported dollar, particularly against the euro. The two clearest reversal triggers are a weak payroll print or a sharp drop in Middle East risk.
Your edge this week comes from preparation rather than speed. Before each session, check four things:
- Oil and Middle East headlines, which decide whether oil reads as inflation or a growth drag.
- Midterm-driven yield moves, especially on Tuesday and Wednesday.
- Payroll revisions, before you act on Friday’s headline.
- The BoE vote split, which matters more than the hike itself.
If the market moves against your notes, the framework tells you why, and that is what keeps a busy week manageable.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. These statements are speculative and subject to change based on market developments.