
Universal Store lifts FY27 YTD DTC sales 9.3% as Perfect Stranger surges
In its FY27 trading update, Universal Store reports Group direct to customer (DTC) sales up 9.3% versus the prior corresponding period (pcp) for the first 17 weeks ended 25 October 2026. The figures are unaudited.
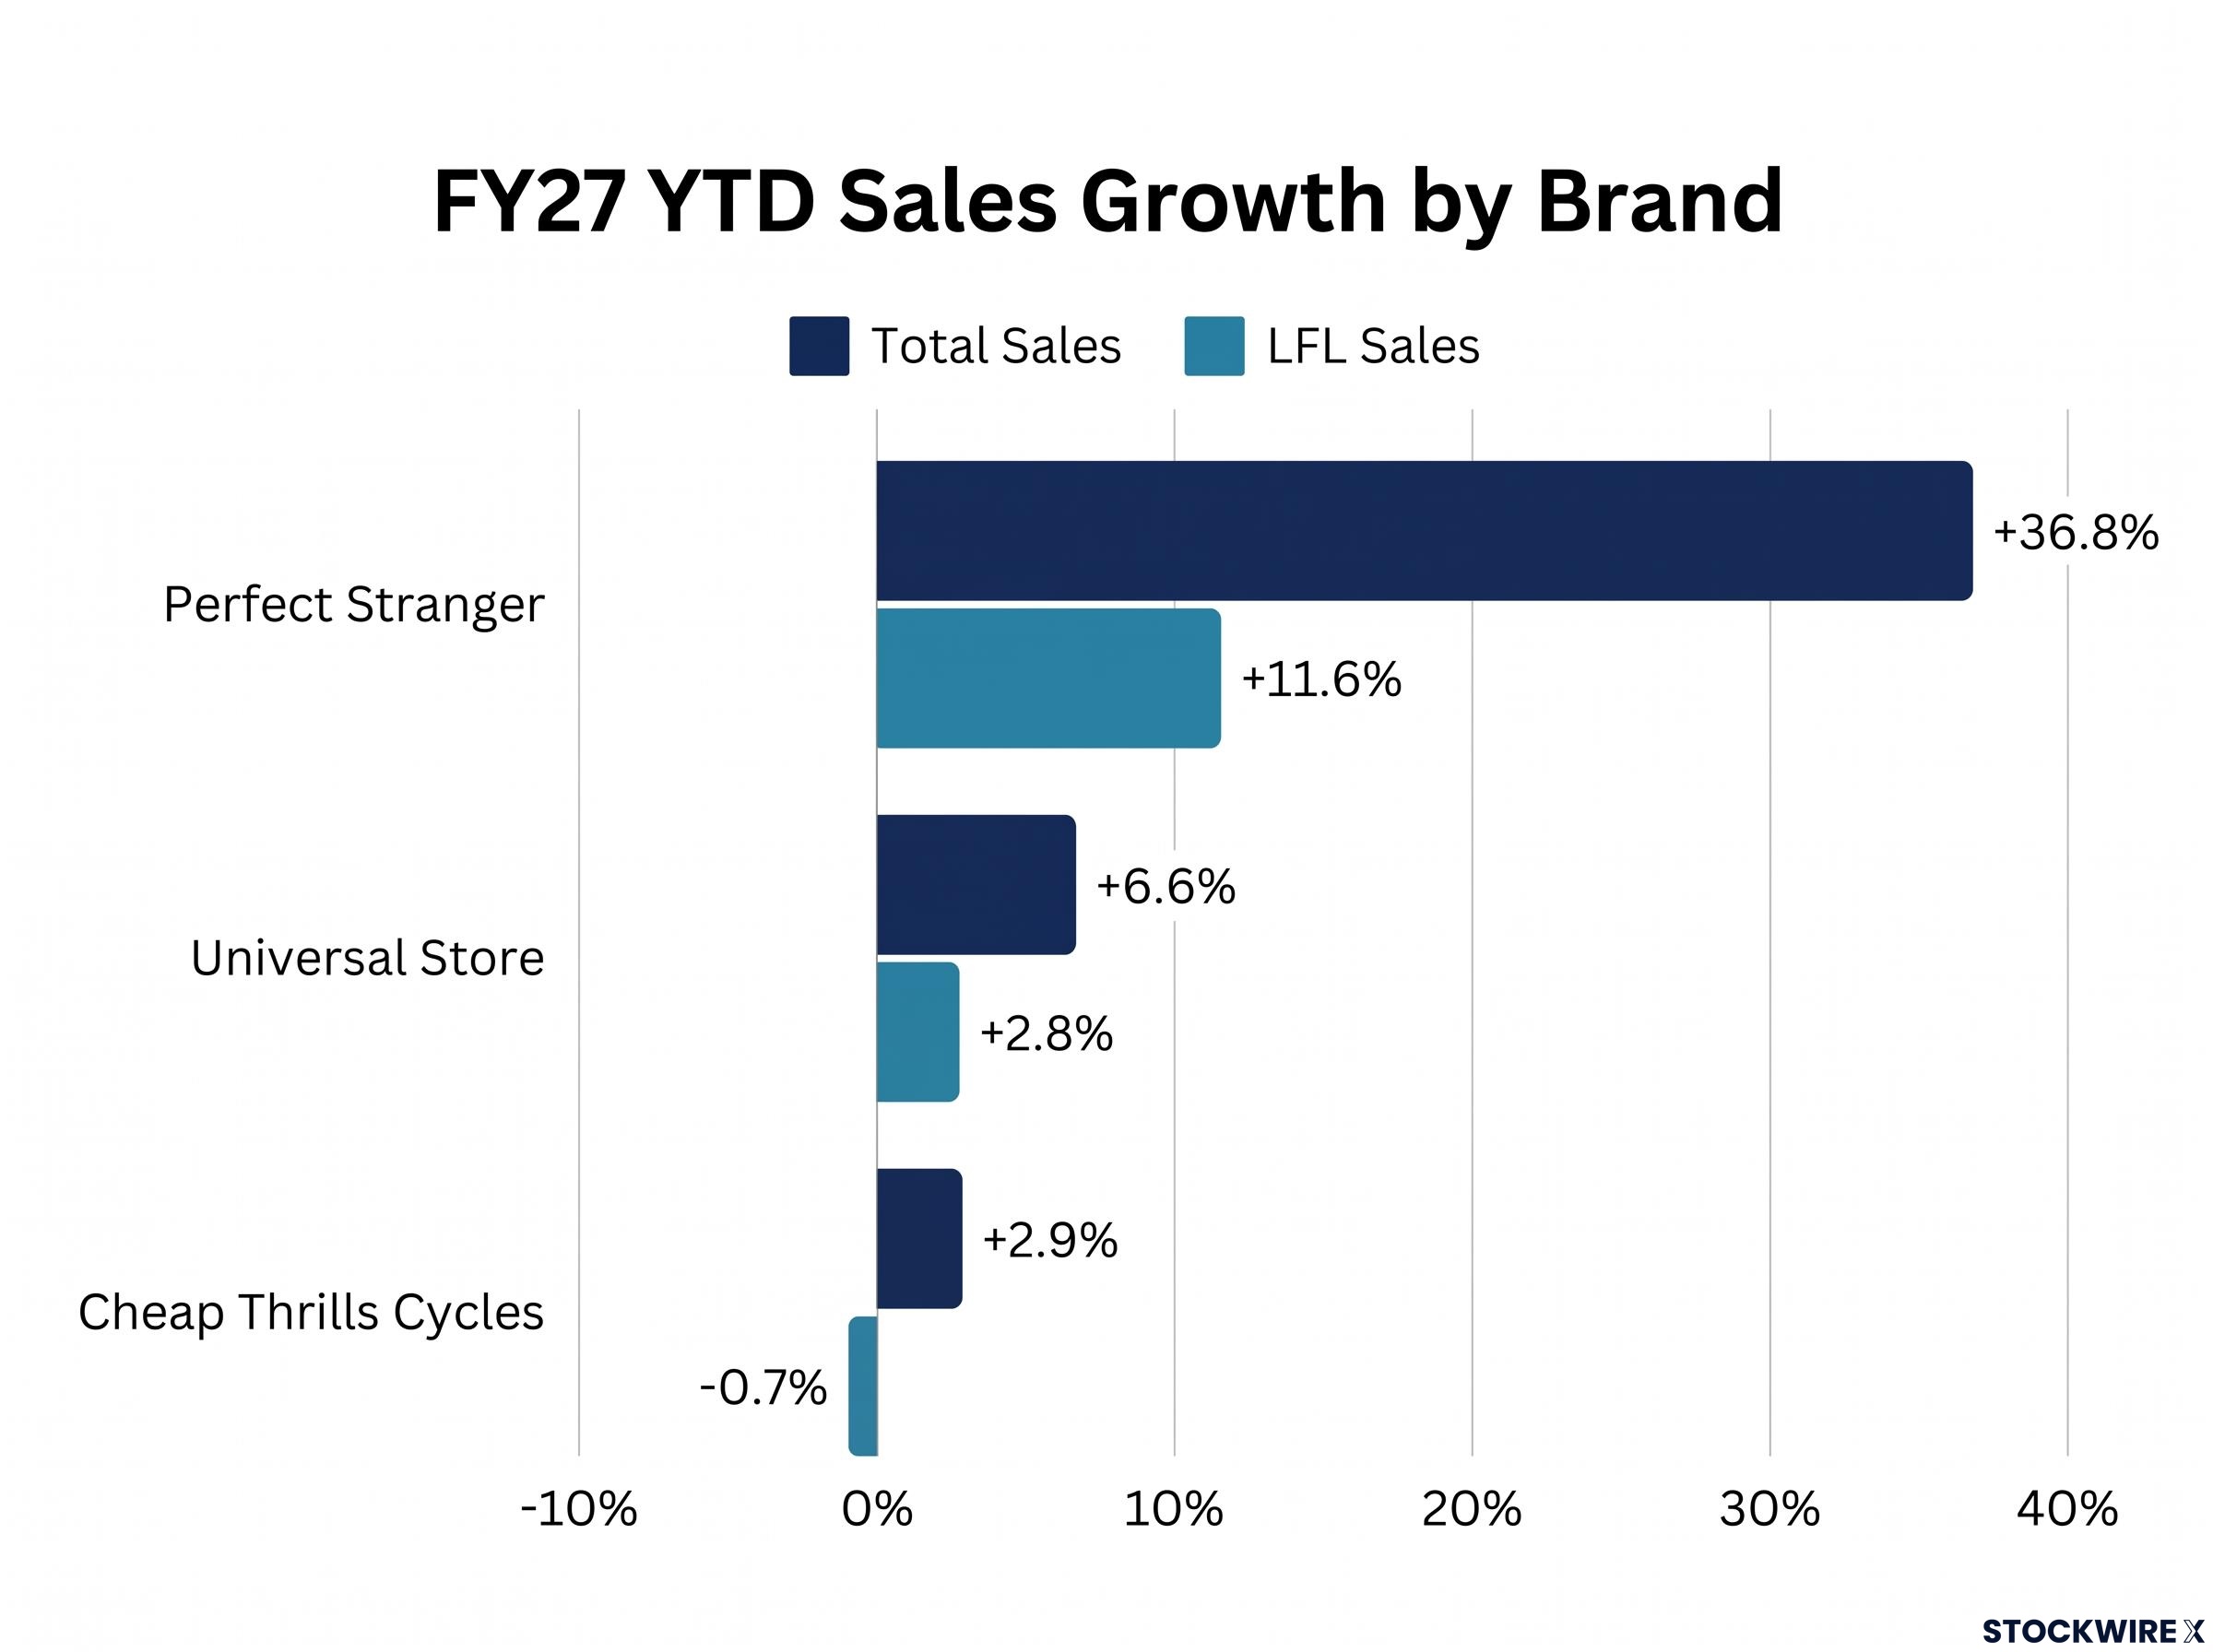
Positive like-for-like (LFL) growth came in a challenging macroeconomic environment and against strong prior year comparatives. Perfect Stranger led the brand results, with total sales up 36.8%.
Alice Barbery, Group CEO
“It has been a pleasing start to the year, with positive LFL growth in a challenging macroeconomic environment and against strong prior year comparatives… The Group is well positioned heading into the peak trading period with healthy inventory and a customer centric mindset.”
The update points to top-line momentum heading into the peak trading period.
When big ASX news breaks, our subscribers know first
Brand-by-brand sales performance
All three brands recorded growth in total sales, though Cheap Thrills Cycles (CTC) posted a slightly negative LFL result. The table below sets out the unaudited FY27 YTD figures versus pcp.
| Brand | Total sales | LFL sales | Cycling |
|---|---|---|---|
| Universal Store (US) | +6.6% | +2.8% | +7.7% |
| Perfect Stranger (PS) | +36.8% | +11.6% | +13.9% |
| Cheap Thrills Cycles (CTC) | +2.9% | -0.7% | +2.3% |
LFL sales are calculated daily from 29 June 2026 to 25 October 2026. The measure excludes closed stores from the day of closure and new stores until they have cycled the first three weeks of operation. CTC’s LFL sales represent DTC sales and exclude the wholesale channel.
Universal Store and Perfect Stranger
US sales were driven by strong third-party and private brand assortments that resonate with customers. Management is pleased with new store performance.
PS sales growth reflects increasing brand awareness and favourable category mix. Management reports little to no discernible cannibalisation of nearby US stores.
Perfect Stranger’s momentum is not new, with the earlier FY26 trading update showing 39.8% total sales growth and 12.9% LFL growth from a store base of only 26 locations.
Cheap Thrills Cycles
CTC in-store execution is progressing well, with YTD LFL growth of +4.1%. Online YTD sales were down 8.8% on the prior year, and management has recently aligned CTC marketing and digital reporting lines into the US team to drive operational improvements.
The wholesale channel remains challenging at circa 4% of total Group sales, net of intercompany eliminations. It is cycling discontinued USA exports and the closure of a small number of key retail accounts in late FY26, consistent with prior guidance.
Margins, store rollout and investment in capability
The growth of Perfect Stranger continues to provide a gross profit % mix benefit to the Group. A favourable effective AUD/USD is currently offsetting higher transport costs.
The Group remains on track to achieve its previous FY27 guidance of 16 to 20 new stores. The rollout breaks down as follows:
- Five stores opened FY27 YTD: three US, one PS and one THRILLS.
- Seven additional stores set to open before Christmas: four US, two PS and one THRILLS.
- One US store will reopen in November after being temporarily closed in FY26.
The Group maintains its prudence in new store and renewal leases, with 19 holdover leases currently under negotiation.
On capability, the new point of sale system was successfully implemented in Q1 FY27. Management continues investing in team and system capability to support future business growth and succession planning.
What a retail trading update tells investors
Total sales include contributions from stores that opened or closed during the period. LFL sales strip those out, giving a clearer read on underlying customer demand in the existing store base.
Here, US LFL growth of +2.8% and PS LFL growth of +11.6% show growth is not coming only from new stores. Gross margin mix also matters: as the PS format expands, it continues to provide a gross profit % mix benefit to the Group.
Key points for readers to weigh:
- Total sales growth includes new stores, while LFL growth reflects existing stores.
- CTC LFL sales were -0.7%, with wholesale remaining challenged.
- PS growth is contributing to the Group’s gross profit % mix.
What happens next for Universal Store
The update outlines the following upcoming steps:
- Seven additional stores are set to open before Christmas (four US, two PS and one THRILLS).
- One US store will reopen in November, after being temporarily closed in FY26.
- The new warehouse management system will be implemented in FY27, after the key peak trading period.
- FY27 new store guidance of 16 to 20 stores remains the target.
Leadership continuity is a factor heading into the peak period, as George Do’s succession takes effect on 1 November 2026 and Alice Barbery moves to a consulting role supporting the CTC business.
Don’t Miss the Next Retail Winner Before the Market Moves
Get FREE breaking ASX consumer news delivered to your inbox within minutes of release, complete with in-depth analysis. Join 20,000+ investors already ahead of the market. Click the “Free Alerts” button at Big News Blast to receive the next market-moving announcement the moment it breaks.