USD/CHF climbed back to about 0.8250 on Friday, up roughly 0.56%, a day after an AI-driven rush into safe assets dragged the pair to a one-month low of 0.8191. The rebound looks more like a correction of Thursday’s move than a change of direction, and the next leg of any USD/CHF forecast now depends on which force wins out.
The rest of the Dollar complex recovered alongside it. The US Dollar Index (DXY), which tracks the Dollar against a basket of major currencies, edged back to about 101.75. The 10-year US Treasury yield drifted back toward 5.00%.
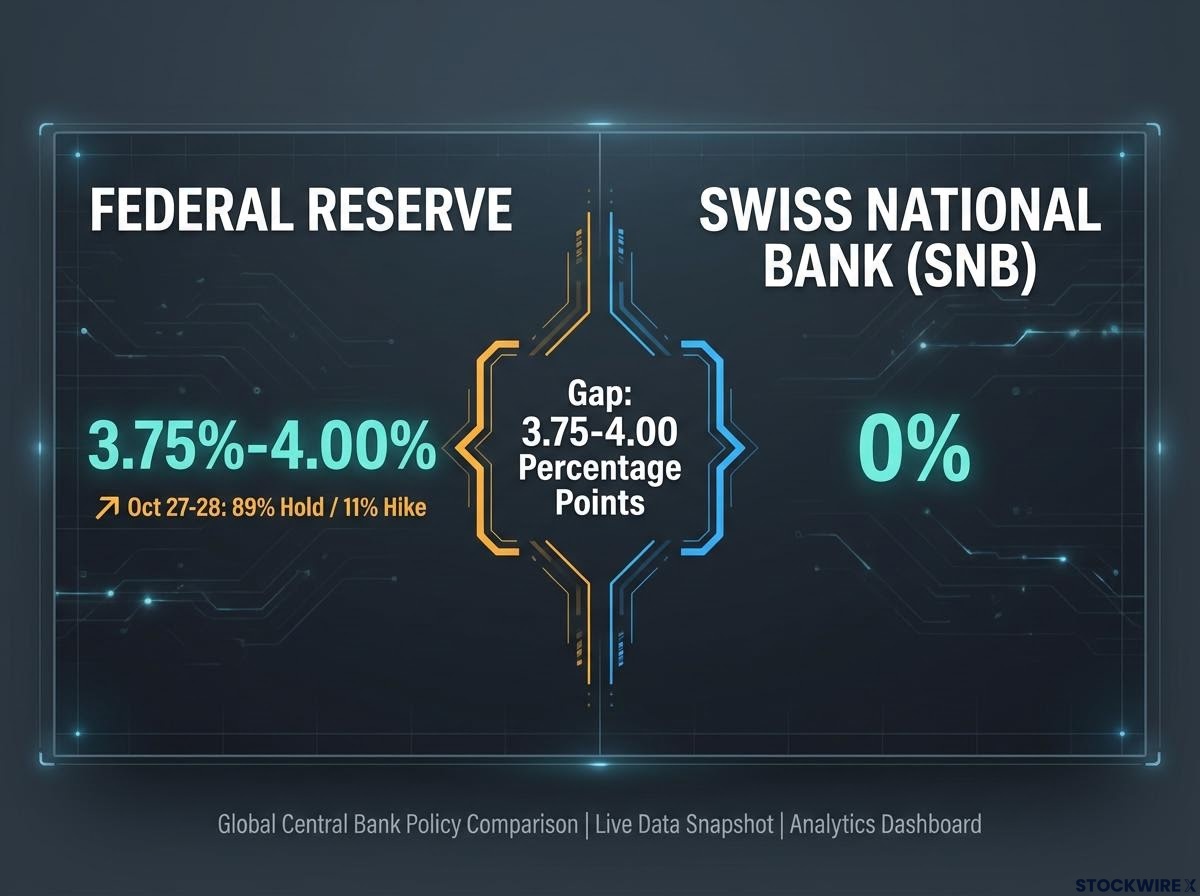
Underneath the daily swings sits a wide policy gap. The Federal Reserve holds its target range at 3.75%-4.00%, while the Swiss National Bank (SNB) keeps its rate at 0%.
Here is what the data says about whether this bounce has legs, and which forces will decide the pair’s next move.
Why did USD/CHF rebound, and how much of it is just a haven unwind?
Thursday’s selling came fast. Worries about whether AI-related investment can be sustained hit equities, and money ran to the usual shelters: the Swiss Franc, the Japanese yen and government bonds. USD/CHF fell to 0.8191, the DXY slid to a three-week low of 101.45, and the 10-year yield dropped 16.6 basis points to 4.95%. Reuters described the move as a rush into US government bonds.
Treasuries rallied while the Dollar fell. That detail matters, because it shows USD/CHF can drop even when US bonds are in demand.
The Franc’s safe-haven status rests on deep FX turnover and large SNB reserves, yet it has limits, including negative carry and a high correlation with the euro during broad European shocks.
By Friday, the haven flow had faded and much of the move reversed.
| Market | Thursday low or move | Friday level | Note |
|---|---|---|---|
| USD/CHF | 0.8191 (one-month low) | About 0.8250 | Up about 0.56% |
| DXY | 101.45 (three-week low) | About 101.75 | Partial recovery |
| US 10-year yield | Down 16.6 bp to 4.95% | Toward 5.00% | Capital.com showed 4.9674% |
Friday’s US data gave the Dollar mixed support:
- S&P Global PMIs: The composite fell to 57.6 from 58.4, manufacturing rose to 56.0 against a 55.6 forecast, and services eased to 57.9 from 58.8.
- Selling prices: Price inflation reached its highest level since August 2022.
- University of Michigan: Final sentiment came in at 48.0, with one-year inflation expectations at 4.7% and five-year expectations at 3.5%.
None of that is fresh Dollar-positive news. The bounce rests on equity markets staying calm, so if the AI jitters return, the support underneath it could disappear quickly.
Can the Fed-SNB rate gap keep the Franc under pressure?
The bigger weight on the Franc is the rate gap. The Fed raised rates by 25 basis points on 16 September, while the SNB held at 0% at its September assessment. According to Fidelity, markets on Friday priced about an 89% chance of no change at the 27-28 October FOMC meeting and about 11% for another hike.
How the SNB moves the Franc
The SNB targets price stability, which it defines as Swiss inflation below 2% a year. Higher Swiss rates usually support the Franc, and the bank has often used its large reserves to buy foreign currency when the Franc becomes too strong for exporters. During energy-driven inflation, it tends not to resist Franc strength, because a stronger currency makes imported energy cheaper.
The SNB’s current figures show how little pressure it faces to tighten:
- Policy rate: 0%
- Inflation forecast at a 0% rate: 0.7% (2026), 0.8% (2027), 0.8% (2028)
- September CPI: 1.0%, up from 0.8% in August
Minutes released on Thursday flagged a short-term rise in inflation from energy prices. The bank also linked the Franc’s roughly 3% trade-weighted fall since June to wider rate differentials. Trade-weighted means the Franc’s value measured against a basket of trading-partner currencies rather than a single one.
The SNB has also changed its tone on intervention:
SNB on intervention The bank said an “increased willingness to intervene is no longer necessary,” while keeping the option to act in currency markets when needed.
That is a smaller threat, not a withdrawal, and SNB commitments can shift without warning. The bank defended a 1.20 EUR/CHF floor from 2011, then scrapped it on 15 January 2015, and the Franc gained about 14.4% in a single day.
The 2015 Frankenshock remains the clearest warning that SNB commitments can vanish overnight, and it is why the bank now declines to broadcast intervention targets that speculators could attack.
For you, a gap of 3.75-4.00 percentage points means holding Francs is expensive. A softer SNB stance also means the safety net under USD/CHF is thinner than it was earlier in 2026, when the bank was actively selling Francs.
What does the USD CHF forecast look like from here, and what could break it?
Forecasts split sharply depending on the time horizon, and the split comes down to which force each forecaster expects to dominate.
| Institution | Outlook | Reasoning |
|---|---|---|
| MUFG (via IBANI) | 0.8480 Q4 2026; 0.8290 Q1 2027; 0.8060 Q2; 0.7840 Q3 | US rate advantage first, then Dollar decline as the cycle turns |
| UBS | About 0.78 by year-end 2026 (range roughly 0.77-0.81) | Eventual Dollar weakening and structural Franc demand |
| Bank consensus | Broadly 0.76-0.80 | Differing views on rate support versus haven demand |
The MUFG and UBS figures come from secondary reports, because the original notes were not publicly accessible.
ING’s Chris Turner has warned that USD/CHF is particularly exposed if the retreat in US tech shares deepens. A disorderly AI-equity sell-off would test the 0.8191 low first.
Risks that favour the Franc
- A renewed AI-driven equity sell-off reviving haven demand
- A geopolitical shock overwhelming the rate gap
- SNB tolerance of Franc strength during energy-driven inflation
Risks that favour the Dollar
- A hawkish Fed, with another hike before year-end still possible
- Energy-driven inflation keeping US yields elevated
- Renewed SNB intervention if the Franc rallies quickly
With targets spread from 0.76 to 0.85, each number is effectively a bet on a particular regime. The triggers will tell you more than any single forecast.
For readers weighing the forecast split, our deep-dive into the USD/CHF outlook examines how safe-haven demand can override a hawkish Fed.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors.
What Friday’s rebound changes, and what it does not
The climb to about 0.8250 corrected Thursday’s haven move without settling the bigger argument. The rate gap and sticky inflation favour the Dollar, while AI-equity stress, geopolitics and a more tolerant SNB favour the Franc.
The next tests are the 27-28 October FOMC meeting, where a hold is heavily priced, further US inflation signals, the SNB’s December assessment and the steadiness of equity markets. Your read on the pair should follow those catalysts rather than Friday’s bounce.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.