The European Central Bank (ECB) says it will not commit to a rate path. Yet a Reuters poll published today found 64 of 73 economists, nearly 90%, expect another hike in December. For anyone tracking the ECB rate outlook, the gap between what the central bank says and what it signals is the whole story.
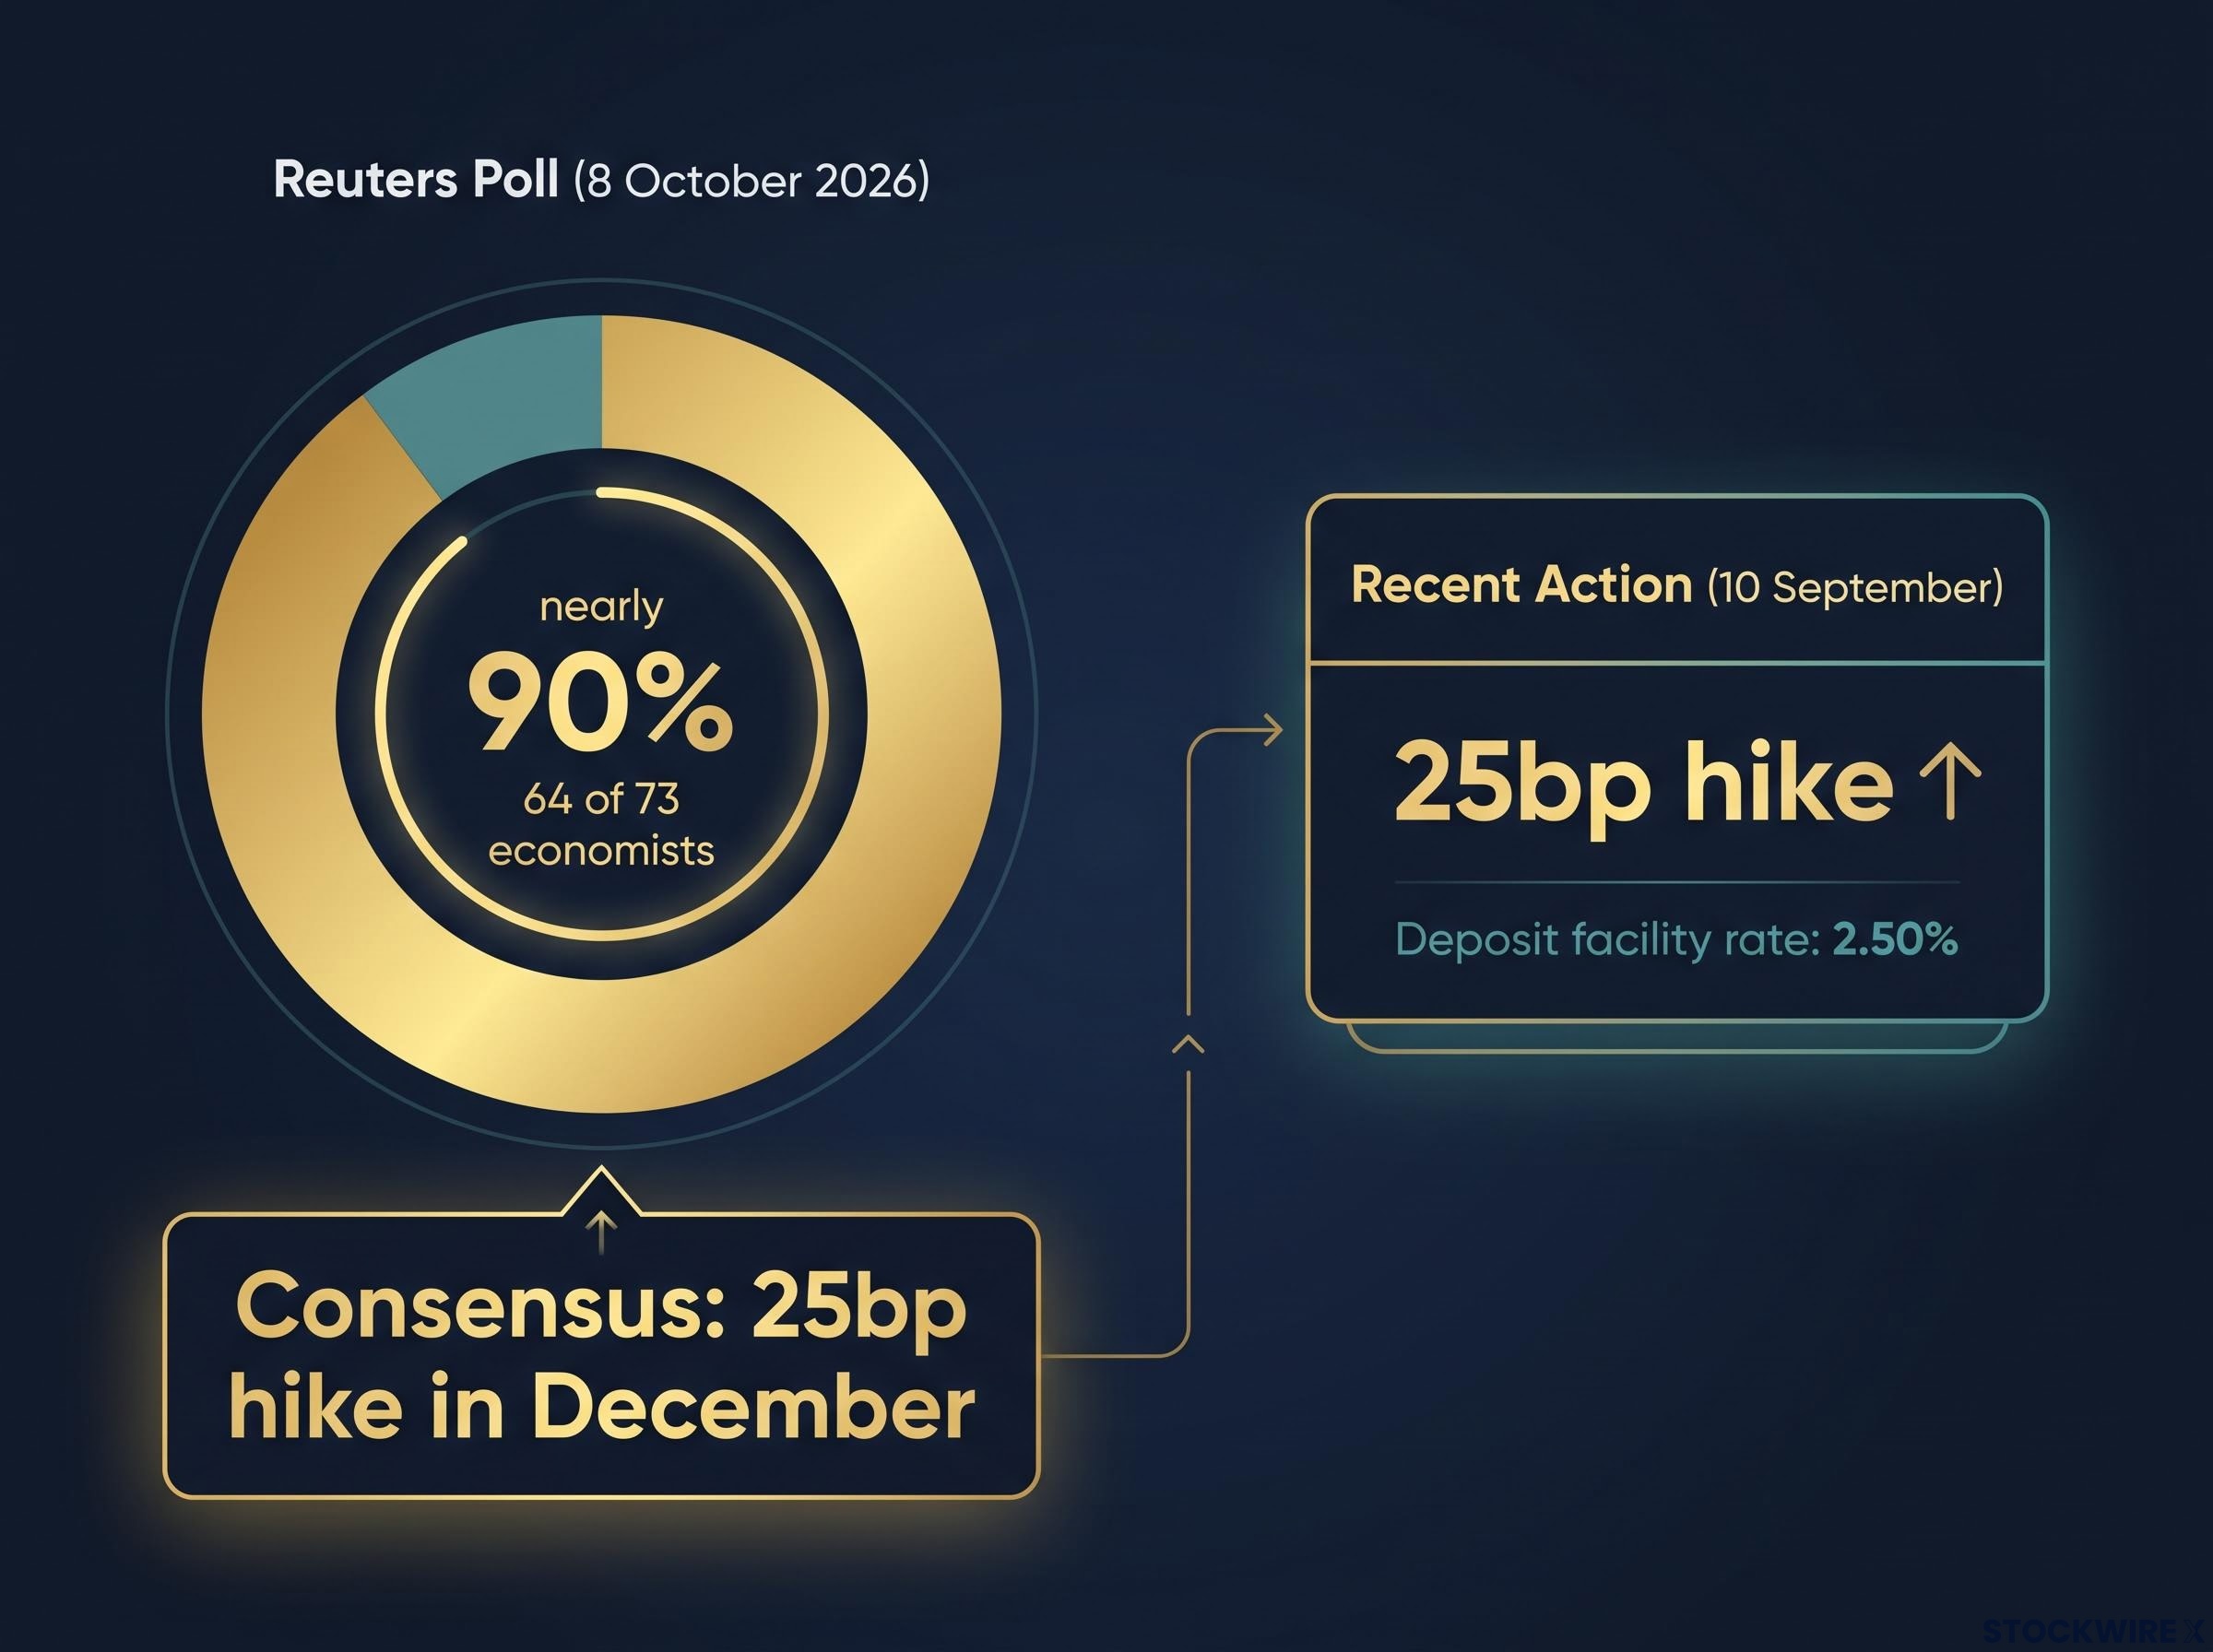
The account of the 9-10 September meeting, published on 8 October 2026, records the reasoning behind a 25 basis point hike on 10 September. That move took the deposit facility rate to 2.50%. A basis point is one hundredth of a percentage point, so 25bp equals 0.25%. The deposit facility rate is the interest the ECB pays banks on overnight deposits, and it anchors borrowing costs across the euro area.
Nordea Chief Analyst Jan von Gerich reads the account as consistent with 25bp hikes in both December and March.
Here is how to read central bank language that refuses to guide, which risks carry the most weight, and what would change the call.
Why does the ECB refuse to commit when its signals point one way?
On the surface, the account looks contradictory. The Governing Council stresses that decisions are taken meeting by meeting and depend on incoming data. It explicitly declined to offer firmer forward guidance, which is a central bank’s public signal about where rates are likely to go next.
That refusal is not neutrality. It is a deliberate choice driven by an outlook the Council describes as highly uncertain and heavily dependent on geopolitics, chiefly the Middle East conflict and Russia’s war against Ukraine. Committing to a path when energy markets can swing on a single headline would risk boxing the bank in.
Forward guidance is one of several ECB policy tools, alongside rate settings and balance sheet runoff, and its absence means markets lean on futures curves and statement wording to infer the next move.
The wording, however, still leans. The account carries three signals worth separating:
- Risks to inflation are skewed to the upside, and upside inflation is named as the Council’s main worry
- Risks to growth are skewed to the downside
- Policy remains meeting by meeting and data-dependent, with no pre-commitment
The September decision statement went further on inflation itself.
ECB decision statement, 10 September 2026 Inflation is expected to stay “well above target for an extended period”.
The Council expects headline inflation to remain well above its 2% target into the first half of 2027. Morgan Stanley read the September meeting the same way, concluding that inflation risks outweigh growth concerns and imply a bias toward further tightening.
What this tells you is that “no commitment” means “no promise”, not “no lean”. Judge the next move by the data the Council says it is watching: inflation, wages, expectations and growth.
What Nordea reads into the account
Von Gerich’s interpretation, published via FXStreet, is that the account fits a baseline of 25bp hikes in December and March even though the ECB refuses to spell out a path. The upside-skewed inflation language and the “extended period” phrasing do the work that formal guidance would otherwise do.
Treat it as a baseline, not a certainty. Nordea’s call rests on the data continuing to confirm the inflation worry, and the second hike carries more conditions than the first.
When big ASX news breaks, our subscribers know first
How big is the energy shock, and are second-round effects really limited?
The account’s most comforting observation is that the energy shock has produced only limited knock-on and second-round effects so far. Broad-based price pressure is not yet visible.
Policymakers do not treat that as comfort. Central banks rarely respond to an energy spike itself; they respond to the risk that it becomes embedded in wider inflation. That embedding typically runs through three channels:
- Pass-through: firms facing higher energy bills raise prices on non-energy goods and services, spreading inflation beyond fuel and power.
- Wages: workers seek pay rises to cover higher living costs, and faster wage growth feeds back into prices.
- Expectations: if households and businesses come to expect higher inflation for longer, their price and wage decisions reinforce the original shock.
The Council’s fear is specific. If energy costs stay high and the economy holds up, those channels could in time start to open. Hawkish members have flagged wage effects and drifting inflation expectations as the danger points.
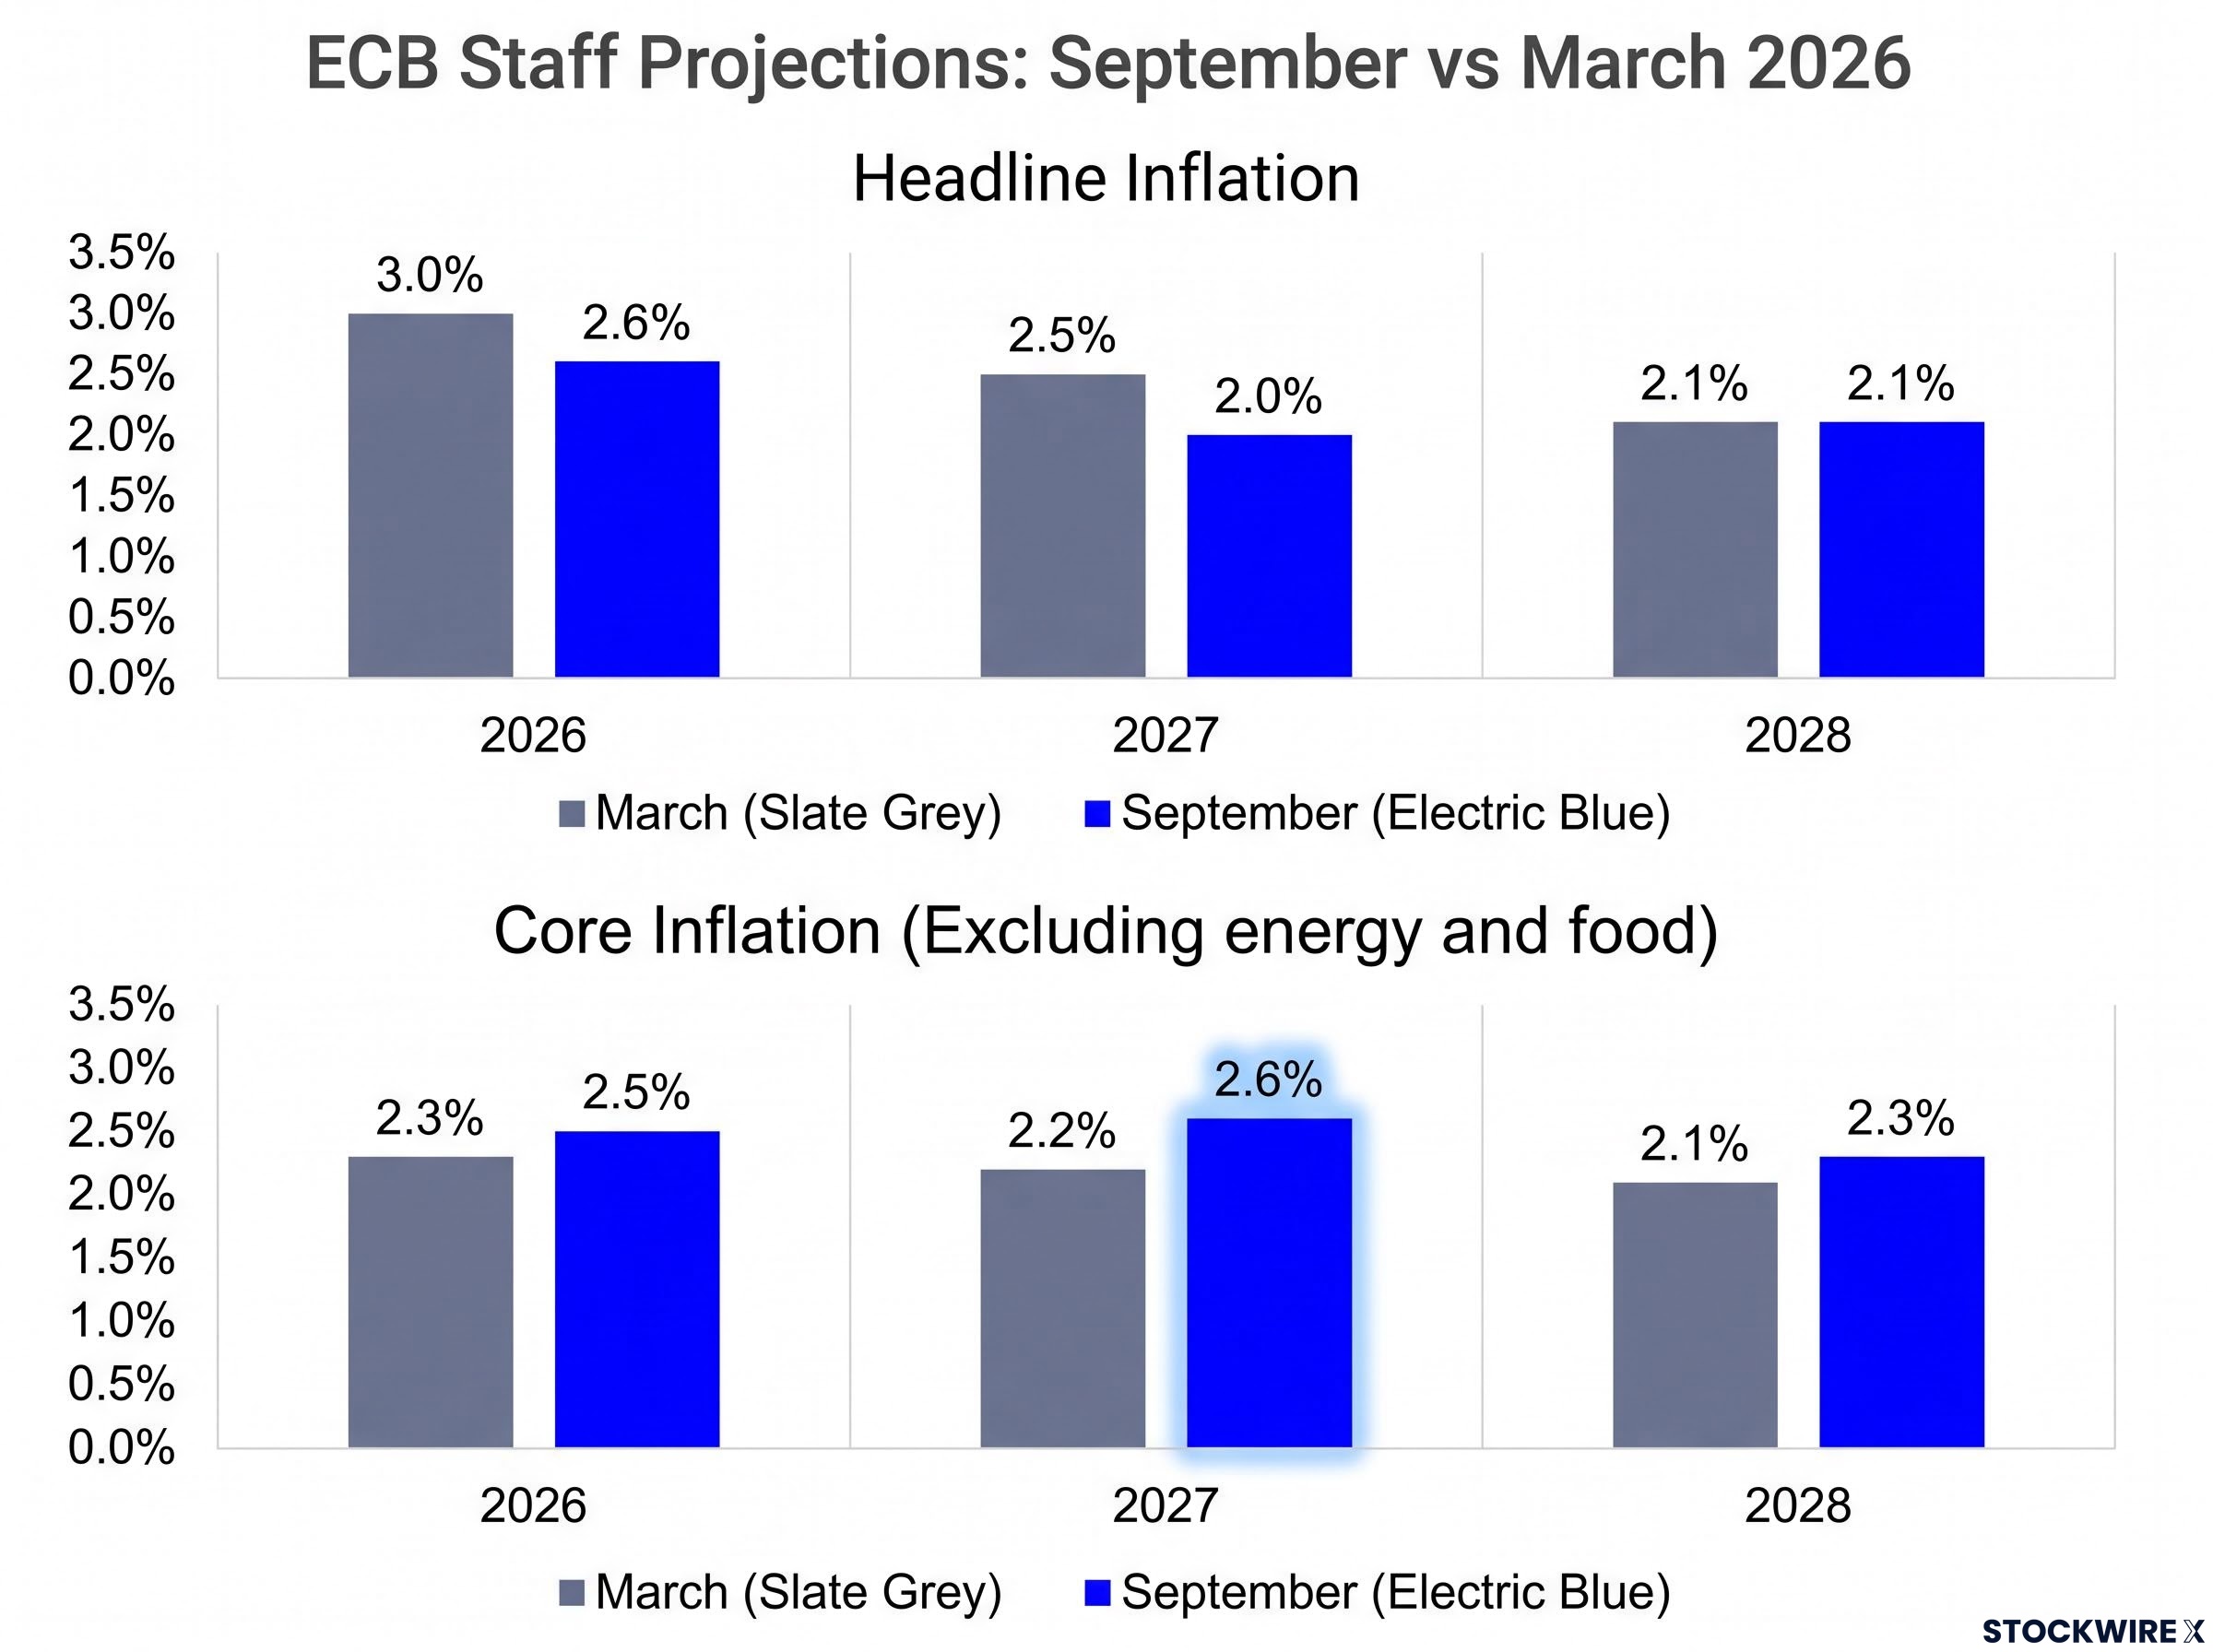
The staff projections show the quantitative case for caution.
| Measure (September / March 2026) | 2026 | 2027 | 2028 |
|---|---|---|---|
| Headline inflation | 3.0% / 2.6% | 2.5% / 2.0% | 2.1% / 2.1% |
| Excluding energy and food | 2.5% / 2.3% | 2.6% / 2.2% | 2.3% / 2.1% |
The revisions are upward across almost every cell. European Parliament analysis has put energy’s contribution to euro-area inflation at around 1.3 percentage points in August 2026, though that figure has not been independently confirmed. ECB materials also reportedly describe energy costs feeding gradually into core and food prices, while wage and inflation expectations have not yet signalled a break from the medium-term goal.
Forecasters disagree sharply here: Rabobank projects inflation peaking near 4.4% in early 2027 against the ECB’s 2.5% for the year, a gap driven almost entirely by differing energy price assumptions rather than core dynamics.
The sharpest number is core inflation for 2027, revised from 2.2% to 2.6%. That tells you the ECB already expects some spillover, so the December debate is about how much, not whether. Core, wages and expectations are the data that will decide it.
What did the France repricing change, and has the market come back to Nordea’s baseline?
Before pricing settled, French fiscal worries briefly muddied the hike path. The episode followed a familiar sequence:
- A budget dispute raised doubts about France’s fiscal trajectory.
- The OAT-Bund spread widened. This is the extra yield investors demand to hold French government bonds (OATs) rather than German ones (Bunds).
- Officials moved to reassure, with Finance Minister Lescure saying France is not experiencing a dysfunctional bond market, according to Newsquawk on 8 October 2026.
- Markets then tested whether anything about the fiscal path had actually changed.
That type of official language usually surfaces once the spread has become politically visible. In past episodes, ECB backstop frameworks limited disorderly spread moves while still letting investors reprice France-specific fiscal risk against Germany.
Precise spread magnitudes and market-implied hike probabilities are not available, so the size of the detour cannot be measured here. Its direction is clearer. Nordea says pricing has drifted back near its baseline of December and March hikes, and economists’ views line up with the market.
Reuters poll, 8 October 2026 64 of 73 economists expect a December hike, with the consensus at 25bp.
The quick reversion tells you markets treat France as a spread story, not a reason to rewrite an inflation-driven policy path. A renewed widening would test that assumption, which leads directly to the risks.
What could break the December and March call?
The consensus is confident about December. March is a different matter, because more data, and more things that can go wrong, sit between now and then.
Hawkish and dovish triggers
The dovish case rests on growth. The ECB and the European Parliament both describe growth risks as skewed to the downside, citing tighter financing conditions, weaker demand and the drag from energy. The minority in the Reuters poll favouring a hold argue exactly this: more hikes could deepen a slowdown.
The dovish counterargument is well established: critics argue rate rises are the wrong tool for a supply-side problem, since higher rates cannot produce more energy or reopen disrupted shipping lanes.
The hawkish case rests on energy. Further escalation, renewed supply disruption or a cold winter pushing gas prices higher could produce the wage and core effects the Council fears, though those winter-supply risks are not independently confirmed. In that scenario, the ECB could deliver both hikes and hold restrictive rates for longer.
| Scenario | What would change | Likely effect on December/March |
|---|---|---|
| Energy escalation | Higher, longer energy prices; clearer wage and core effects | Supports both hikes and restrictive rates for longer |
| Growth slowdown | Weaker demand and tighter financial conditions | Strengthens case for pausing after December |
| French fiscal stress | Renewed OAT-Bund spread widening | Raises odds of stopping sooner, mainly in March |
Easing tensions or better energy supply would work in the other direction, reducing inflation pressure and the need for further hikes. Treat December as the consensus call and March as the contingent one, and track energy prices, wage data and French spreads as the three variables that decide between them.
Past performance does not guarantee future results. Forecasts cited here are subject to market conditions and may change as data arrives.
Reading an uncommitted ECB: what to watch before December
The ECB’s refusal to commit is a feature, not a flaw. It preserves room to respond to a shock it cannot forecast, while the account’s wording still leans clearly toward inflation risk. Second-round effects remain limited but closely watched, and market pricing has returned near Nordea’s baseline after the France detour.
December is the better-supported call. March depends on data that has not arrived yet. Before the December meeting, monitor:
- Core inflation readings for signs of energy pass-through
- Wage growth and inflation expectations
- Energy prices, particularly gas into winter
- The OAT-Bund spread
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
—