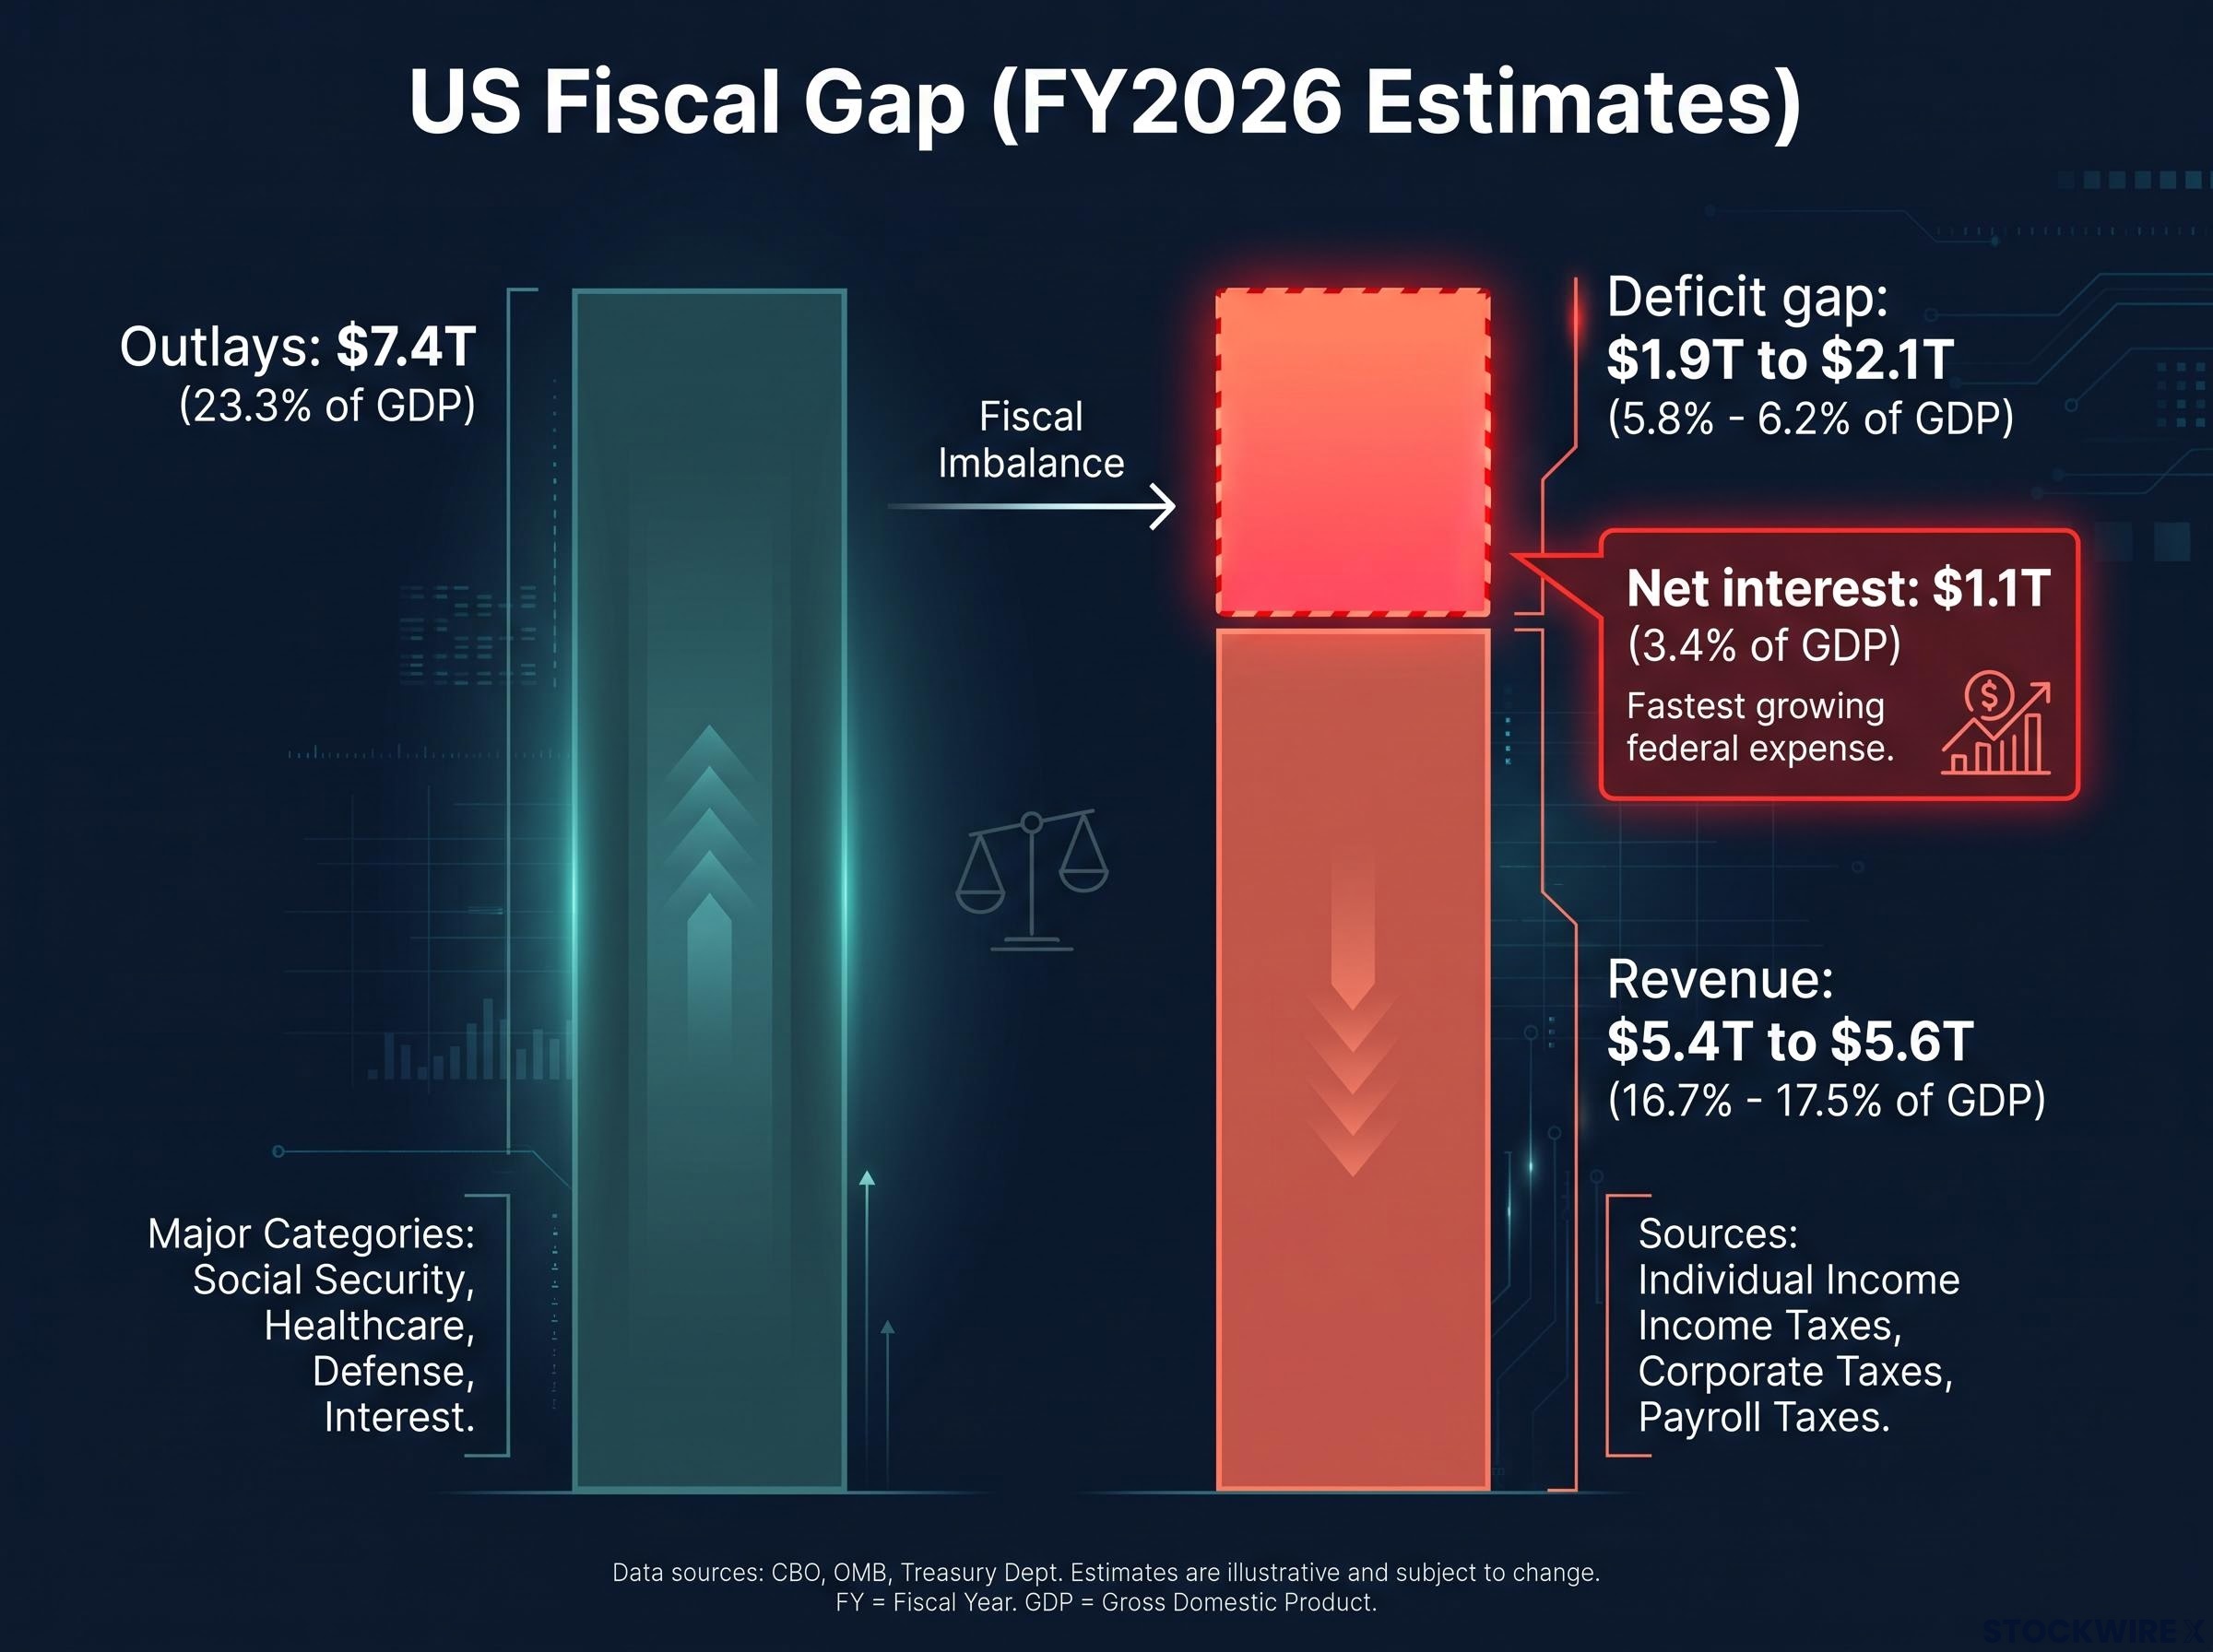
The US government is on track to spend about $7.4 trillion this fiscal year while collecting roughly $5.4 trillion, and the 10-year Treasury yield is sitting near 5.3%. Many investors treat those numbers as background noise. Ray Dalio treats them as the starting point for his whole portfolio strategy.
Dalio founded Bridgewater Associates. Speaking with Julia La Roche at the Greenwich Economic Forum this week, he said global debt supply and demand are out of balance. He warned they could spiral into a crisis “somewhere in the next two years.”
The headline is alarming. The reasoning underneath is more useful, because it shows you which parts of your portfolio would feel pressure first and which might hold up.
Here is the full line of reasoning, from the debt arithmetic to how markets price it to Dalio’s specific positions. You also get the strongest counterarguments, so you can decide for yourself how much weight his view deserves.
What is Dalio actually claiming about a US debt crisis?
At its most alarming, the claim runs like this. The US issues more debt than buyers want. Yields rise until credit is rationed, meaning some borrowers simply get priced out. Markets take the first hit, and the wider economy follows.
The detail matters, though. Dalio says the US is on the brink of the later stage of the debt cycle, not past it. He calls the present a risky period, which is a different thing from a certain collapse.
| Item (FY2026) | Amount | Share of GDP | Source |
|---|---|---|---|
| Outlays | $7.4T | 23.3% | CBO, 11 February 2026 |
| Revenue | $5.4T-$5.6T | 16.7%-17.5% | CBO; Dalio |
| Deficit | $1.9T-$2.1T | About 5.8%-6.2% | CBO baseline (higher monthly estimate unverified) |
| Net interest | About $1.1T | 3.4% | CRFB, 1 October 2026 |
| Debt held by the public | $32.1T-$32.3T | 100%-101% | CBO |
The Congressional Budget Office (CBO) and the Committee for a Responsible Federal Budget (CRFB) figures line up closely with Dalio’s own. The key number is interest. Roughly half of the $2 trillion gap is interest on existing debt, so borrowing creates interest, which creates more borrowing.
That is why Dalio treats this as a cycle rather than a one-year budget problem. The gap feeds itself.
The buyer side is the other half. Treasury International Capital (TIC) data for July 2026 shows Japan holding $1,103.9 billion, the UK $998.3 billion and China $618.0 billion. Dalio puts the foreign share of public debt at roughly 29%-30%, though that figure is his own and is not confirmed in CBO or TIC data.
The five forces behind the warning
Dalio built his framework from studying roughly 500 years of history. He argues most issues people discuss fall into five buckets:
- Debt and money cycle: debt service crowds out other spending. This is the force driving his current warning.
- Internal conflict: wealth and values gaps fuel populism and division.
- Geopolitical order: he sees the post-1945 rules-based system giving way to a power-based one.
- Acts of nature: droughts, floods and pandemics.
- Technology: AI, which he says is certain to change the world.
He adds a political overlay. He expects the midterms to sharpen internal conflict and sees the period through 2028 as more vulnerable.
Dalio’s five forces framework treats debt stress, polarisation, geopolitics, nature shocks and AI as interacting pressures, and you can see why correlations tend to spike when several of them turn disruptive at once.
When big ASX news breaks, our subscribers know first
Why Dalio says this looks like a bubble: wealth versus spendable cash
Paper wealth is easy to create. Dalio’s example is simple: raise $50 million at a $1 billion valuation, and you are a billionaire on paper. You cannot spend that billion without selling something.
That gap between paper wealth and spendable cash is the core of his bubble thinking. High prices alone do not end a bubble. Forced selling does.
The sequence usually runs like this:
- A world-changing technology attracts enthusiasm and borrowed money.
- Valuations climb, creating large amounts of paper wealth.
- A need for cash appears, such as debt repayments or wealth taxes.
- Holders must sell to raise that cash, and prices fall faster than buyers can absorb.
History supplies the pattern. Before 1929, investors borrowed to bet on electricity, cars, radio and aircraft. In the late 1990s, the internet was real, yet many high-valuation tech stocks lost most of their value.
Dalio says current conditions meet his bubble indicators. AI is today’s world-changing technology, he views the big AI leaders as expensive, and both governments and large tech companies are issuing debt, partly to fund AI spending. Stocks have also risen while bonds fell, leaving the expected extra return from owning shares over bonds very low.
Dalio’s stance on bonds He told the forum he is “short debt,” meaning he is positioned to profit if bond prices fall.
What this means for you: the thing to watch is financing, not just price-to-earnings ratios. Ask who borrowed to own an asset, and who might be forced to sell it.
How weak Treasury demand could reach stocks, mortgages and the wider economy
So how would forced selling actually spread? Dalio’s answer runs through the Treasury market, and the chain has five links:
- Higher yields and term premia. The term premium is the extra yield investors demand for holding a long-term bond instead of rolling short-term ones. If buyers step back, it rises.
- Equity discount rates. Higher yields reduce what future profits are worth today. Long-duration growth and AI stocks, whose profits sit far in the future, are hit hardest.
- Mortgages and corporate credit. Both are priced off Treasuries plus a spread, so borrowing costs climb.
- Leverage and margin calls. Losses at banks, pensions and leveraged funds can force sales, pushing yields higher still.
- Macro slowdown. Tighter credit slows growth, softens hiring and raises recession risk.
The first link is already visible. The 10-year yield sat between 5.27% and 5.32% in the first week of October 2026, and Dalio says China and Japan are pulling back from Treasuries.
For a US household, the same force that compresses stock valuations also lifts mortgage costs and weakens the job market. Dalio says borrowers such as mortgage holders are the most likely to be squeezed out. You do not need to own bonds to be exposed.
The chain has broken before.
| Episode | Trigger | Market effect | Relevance |
|---|---|---|---|
| UK gilt crisis, 2022 | Unfunded tax-cut proposals | Gilt yields spiked; pension funds hit margin calls | Leverage turned a yield jump into forced selling until the Bank of England stepped in |
| 1929 | Credit-fuelled speculation | Correction became systemic crisis | Matches Dalio’s forced-selling logic |
| 1970s | High nominal and real rates | Weak equity multiples; commodities and gold strong | Shows how real assets behave in that regime |
The UK case is the clearest. Pension funds using liability-driven investment (LDI), a strategy that uses borrowed exposure to match future payouts, had to dump government bonds to meet collateral calls.
Treasury market risk now spreads through shared leverage and collateral chains, which is why a dislocation in US yields can transmit quickly to gilts, eurozone bonds and Japanese government bonds.
Do other experts agree? Where the debate splits
On the long-run trajectory, Dalio has plenty of company. The CBO lists interest among the fastest-growing budget items. The International Monetary Fund (IMF) says advanced-economy debt, including US debt, is on an unsustainable path without policy changes.
Federal Reserve Chair Jerome Powell has called the long-run fiscal path “unsustainable,” while stressing that fixing it is Congress’s job. Investors Stanley Druckenmiller and Bill Gross have argued that big deficits bring higher rates and volatility.
The split comes over timing.
| Camp | Who | Core argument | Implied timeline |
|---|---|---|---|
| Alarmed | Ray Dalio | Supply outruns demand; credit gets rationed | Possible crisis within about two years |
| Concerned | CBO, IMF, Powell, Druckenmiller, Gross | Path is unsustainable; bond markets will push back | Rising pressure, timing open |
| Sceptical of near-term crisis | Paul Krugman, Olivier Blanchard, Jason Furman | US borrows in its own currency; reserve demand stays strong; debt ratio can stabilise if growth holds | Gradual adjustment possible |
| Structural, medium-term | Bank and market strategists | Deep Treasury market and domestic buyers absorb supply | Valuation and growth drag, not an emerging-market-style crisis |
The sceptics’ sharpest point is that sustainability is a policy choice, not a mechanical trigger. Reports of an earlier, similar Dalio warning are undated, so they offer no guide to timing.
What this tells you: nearly everyone agrees the trajectory is a problem. The argument is about when and how it bites, and that should shape how aggressively you act.
What a Ray Dalio portfolio strategy looks like in practice, and where it carries risk
Dalio’s core answer is diversification, because the future is uncertain. Every specific idea sits beneath that principle, and every one carries a downside.
The same diversification principle underpins Bridgewater’s All Weather Portfolio, which balances risk across rising and falling growth and inflation rather than betting on a single macro outcome.
Dalio’s positions and their risks
| Asset | Dalio’s view | Main risk | Common mainstream range |
|---|---|---|---|
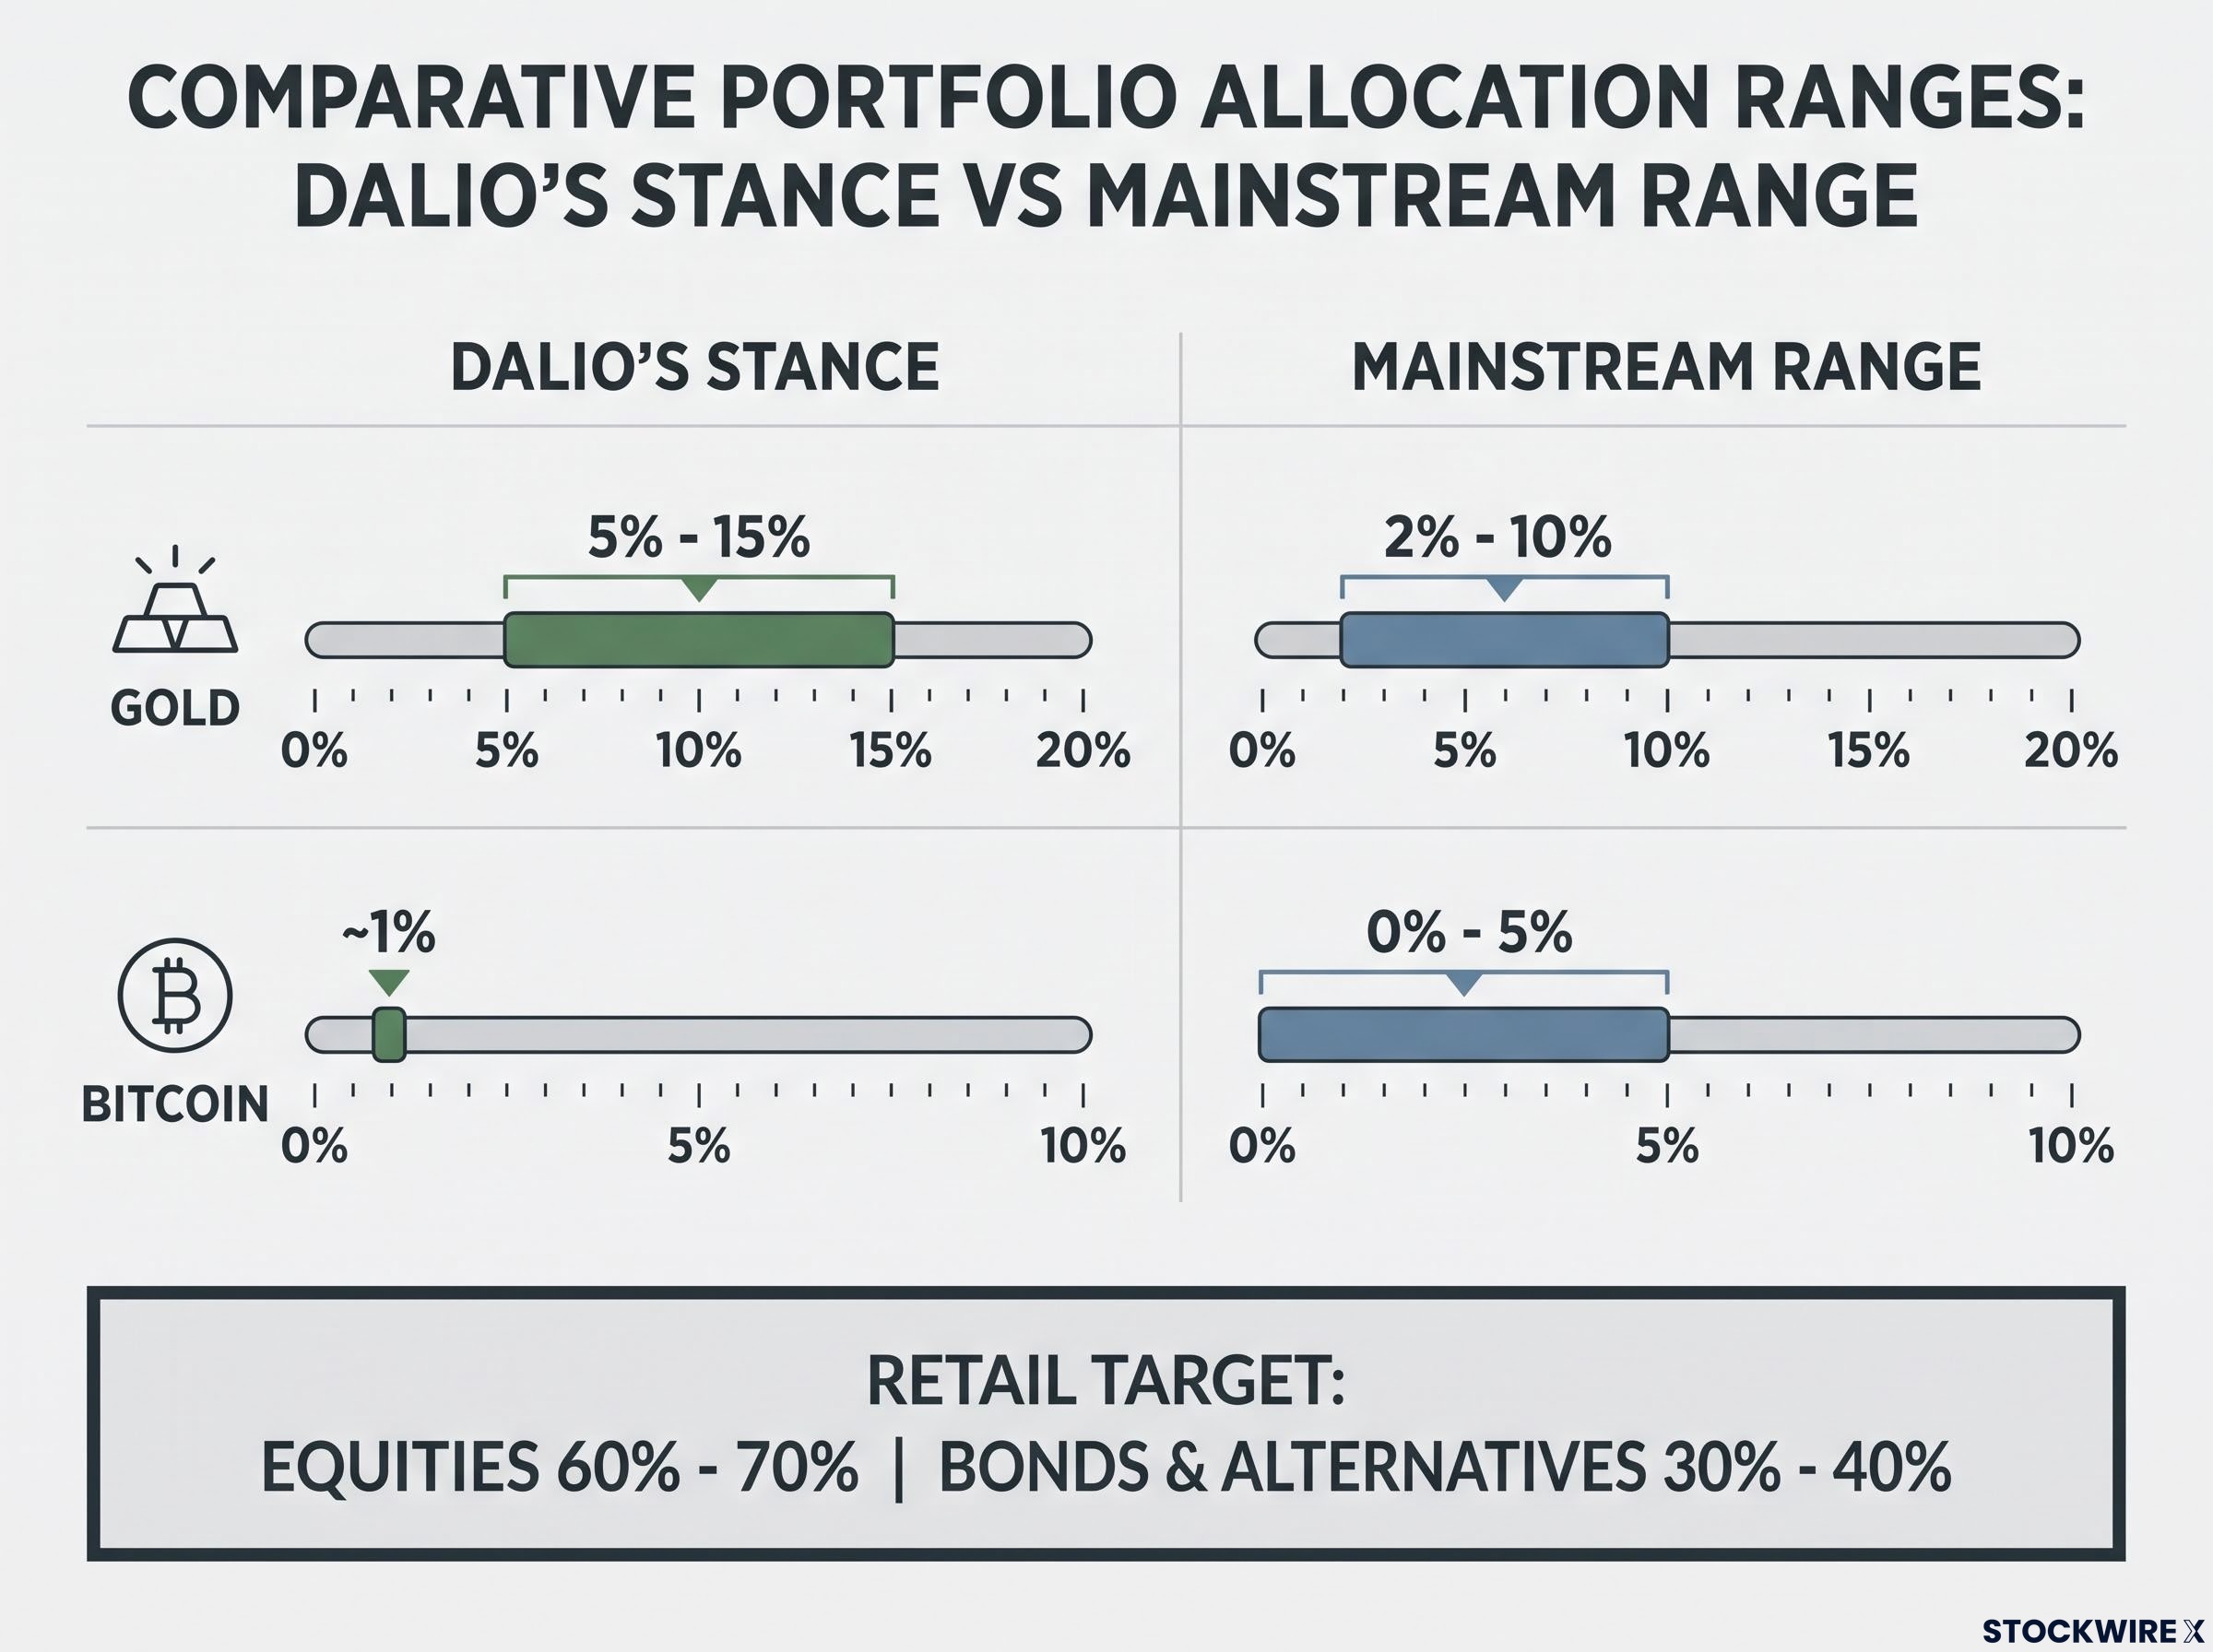
| Gold (about $4,120-$4,146/oz, 8 October 2026) | 5%-15% as hard money and diversifier | No income; weak when real rates are high | Often 2%-10% |
| TIPS (real yield about 2.91%-2.92%) | Favoured, possibly leveraged | Duration risk; tax on inflation gains in taxable accounts | Moderate slice of the bond mix |
| Bitcoin | About 1% of his own holdings, not recommended | Extreme volatility; regulatory and technology risk | Often 0%-5% |
| AI equities | Leaders expensive; prefers companies using AI to cut costs or lift sales | Stretched valuations; mega-cap concentration | No standard range |
| International | Mostly US, plus Singapore, UAE, ASEAN, selective Europe | Currency and country risk | Selective exposure |
Treasury Inflation-Protected Securities (TIPS) are US government bonds whose principal rises with inflation. Breakeven inflation, the rate at which they match ordinary Treasuries, sits near 2.36%. Dalio picks countries on financial health (favouring capital-surplus nations), innovation and position on the technology wave.
The biggest tension is gold. The top of Dalio’s range is 15%, while many strategists call that high for retail investors. Bridgewater frames gold as one piece of a balanced mix, not the centrepiece.
On Bitcoin Dalio holds a small position but says he is “not a supporter,” citing government influence, traceability and possible vulnerability to AI.
Turning it into a retail plan
Planners translating these ideas for individual investors tend to land on six steps:
- Build a low-cost core of broad US stock and investment-grade bond index funds.
- Add developed and emerging-market equity funds for international exposure.
- Hold about 5%-15% combined in inflation hedges such as TIPS funds, commodities and modest gold, with no leverage.
- If you use crypto, ring-fence it at roughly 1%-3%, with no borrowing.
- Set target ranges (for example 60%-70% equities, 30%-40% bonds and alternatives) and rebalance periodically.
- Adjust for your age, income stability and risk tolerance, and hold TIPS in tax-advantaged accounts where possible.
Dalio’s leveraged TIPS idea is not a retail-friendly step. The lesson that carries over is cutting your reliance on US nominal debt and a narrow set of US equity themes, not copying his exact allocations.
Weighing the warning against your own portfolio
Dalio’s case rests on three things: debt supply outrunning demand, forced selling after a leverage build-up, and rising political strain. Credible sceptics accept the trajectory but argue the US can adjust gradually.
You do not have to pick a side today. You can watch the signals: the 10-year yield, foreign demand in TIC data, mortgage rates, the midterm results and AI-related debt issuance.
Then ask one question of your own holdings. How much of your portfolio depends on long-duration nominal assets and a single equity theme? If the honest answer is “most of it,” broader diversification is a reasonable response whichever camp proves right.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and forward-looking views are speculative and subject to change.