If you think bond market stress is a distant, technical story for traders, the numbers say otherwise. The US 30-year Treasury yield climbed to its highest in over twenty years today, the UK 10-year gilt sits at its highest since 2007, and the US 10-year touched 5.34% earlier this month, a level last seen in 2002. This global bond selloff is already moving the borrowing costs that sit behind your mortgage, your pension and your share portfolio.
What makes this episode different is that it is happening everywhere at once. Washington, London and Paris are all paying more to borrow, and when government debt reprices across several markets together, the effects reach well beyond bond desks.
Yesterday’s release of the Federal Reserve’s September meeting minutes added another layer, hinting that US interest rates may rise again before the year is out.
Here is how to read the signals behind the headlines: what is driving yields higher, how FedWatch odds and yield spreads work, and why the link between bonds and stocks deserves your attention right now.
What is driving the global bond selloff right now?
Start with the screen. A yield is the annual return you earn for lending money to a government by buying its bonds, and when bond prices fall, yields rise. Right now, the readings across three major markets look like this.
Because a bond’s coupon is fixed, the maths is automatic: when bond prices fall, the same payment represents a higher return on the lower price you paid, and that is why yields rise whenever buyers step back from a market.
| Market | Benchmark | Latest level | Historical context |
|---|---|---|---|
| United States | 10-year Treasury | About 5.327% (8 October premarket); peak 5.34% | Highest since 2002 |
| United States | 30-year Treasury | Near 5.64%-5.72% earlier in October; new high on 8 October | Highest in over twenty years |
| United Kingdom | 10-year gilt | About 5.44%-5.47%; some readings near 5.51% | Highest since 2007 |
| France | 10-year OAT | 4.77% (6 October) | Spread over Germany recently at widest since 2011 |
A strong 10-year Treasury auction largely steadied US bonds today, yet the 30-year still pushed to a fresh multi-decade high. Even good news on demand did not stop long-term borrowing costs from rising.
Widen the lens and three national stories become one. France supplied the European trigger: an unpopular budget proposal sent its yields higher and pushed the gap over German bonds to its widest since the euro-zone debt crisis, before it narrowed to 129.79 basis points on 6 October. A basis point is one-hundredth of a percentage point. Deutsche Bank described France as central to the worldwide selloff and warned that European contagion risk had returned.
The repricing in one number The US 10-year yield’s rise was the largest quarterly increase since 1994, a sign that investors are demanding more to hold long-term debt, not just reacting to the next rate decision.
For you, the takeaway is simple. When yields climb together across countries, the pressure is global rather than local, so spreading your bond holdings across different governments offers less protection than you might expect.
When big ASX news breaks, our subscribers know first
Why are US, UK and French yields rising together?
No single cause explains the move. Several pressures are pushing in the same direction, and each one reinforces the others.
- Inflation and higher-for-longer rates. Borrowing costs from the US to Germany and Japan have hit multi-decade highs on worries that inflation will keep interest rates elevated.
- Fiscal and debt-load worries. Governments carry large debts, and investors want more compensation to keep lending.
- Heavy issuance. A flood of new government bonds, plus a wave of corporate AI debt, means more paper competing for the same buyers.
- Oil as a swing factor. Energy prices feed inflation expectations, and inflation feeds yields.
- Quarter-end rebalancing. The steep selloff left multi-asset portfolios out of balance, and the trades to correct that can amplify moves across markets.
Put those pieces side by side and the description Reuters used starts to make sense: a “toxic mix” of weakening government finances, an issuance glut and rising inflation.
Oil shows how these drivers interact. Prices eased on 6 October, helping calm markets after the previous week’s turmoil, then gains returned by 8 October on Middle East supply concerns. Coverage did not give a specific price.
That back-and-forth matters for you. Because supply and inflation pressures are both at work, a single soft oil day is unlikely to end the pressure on borrowing costs.
How AI financing adds to bond supply
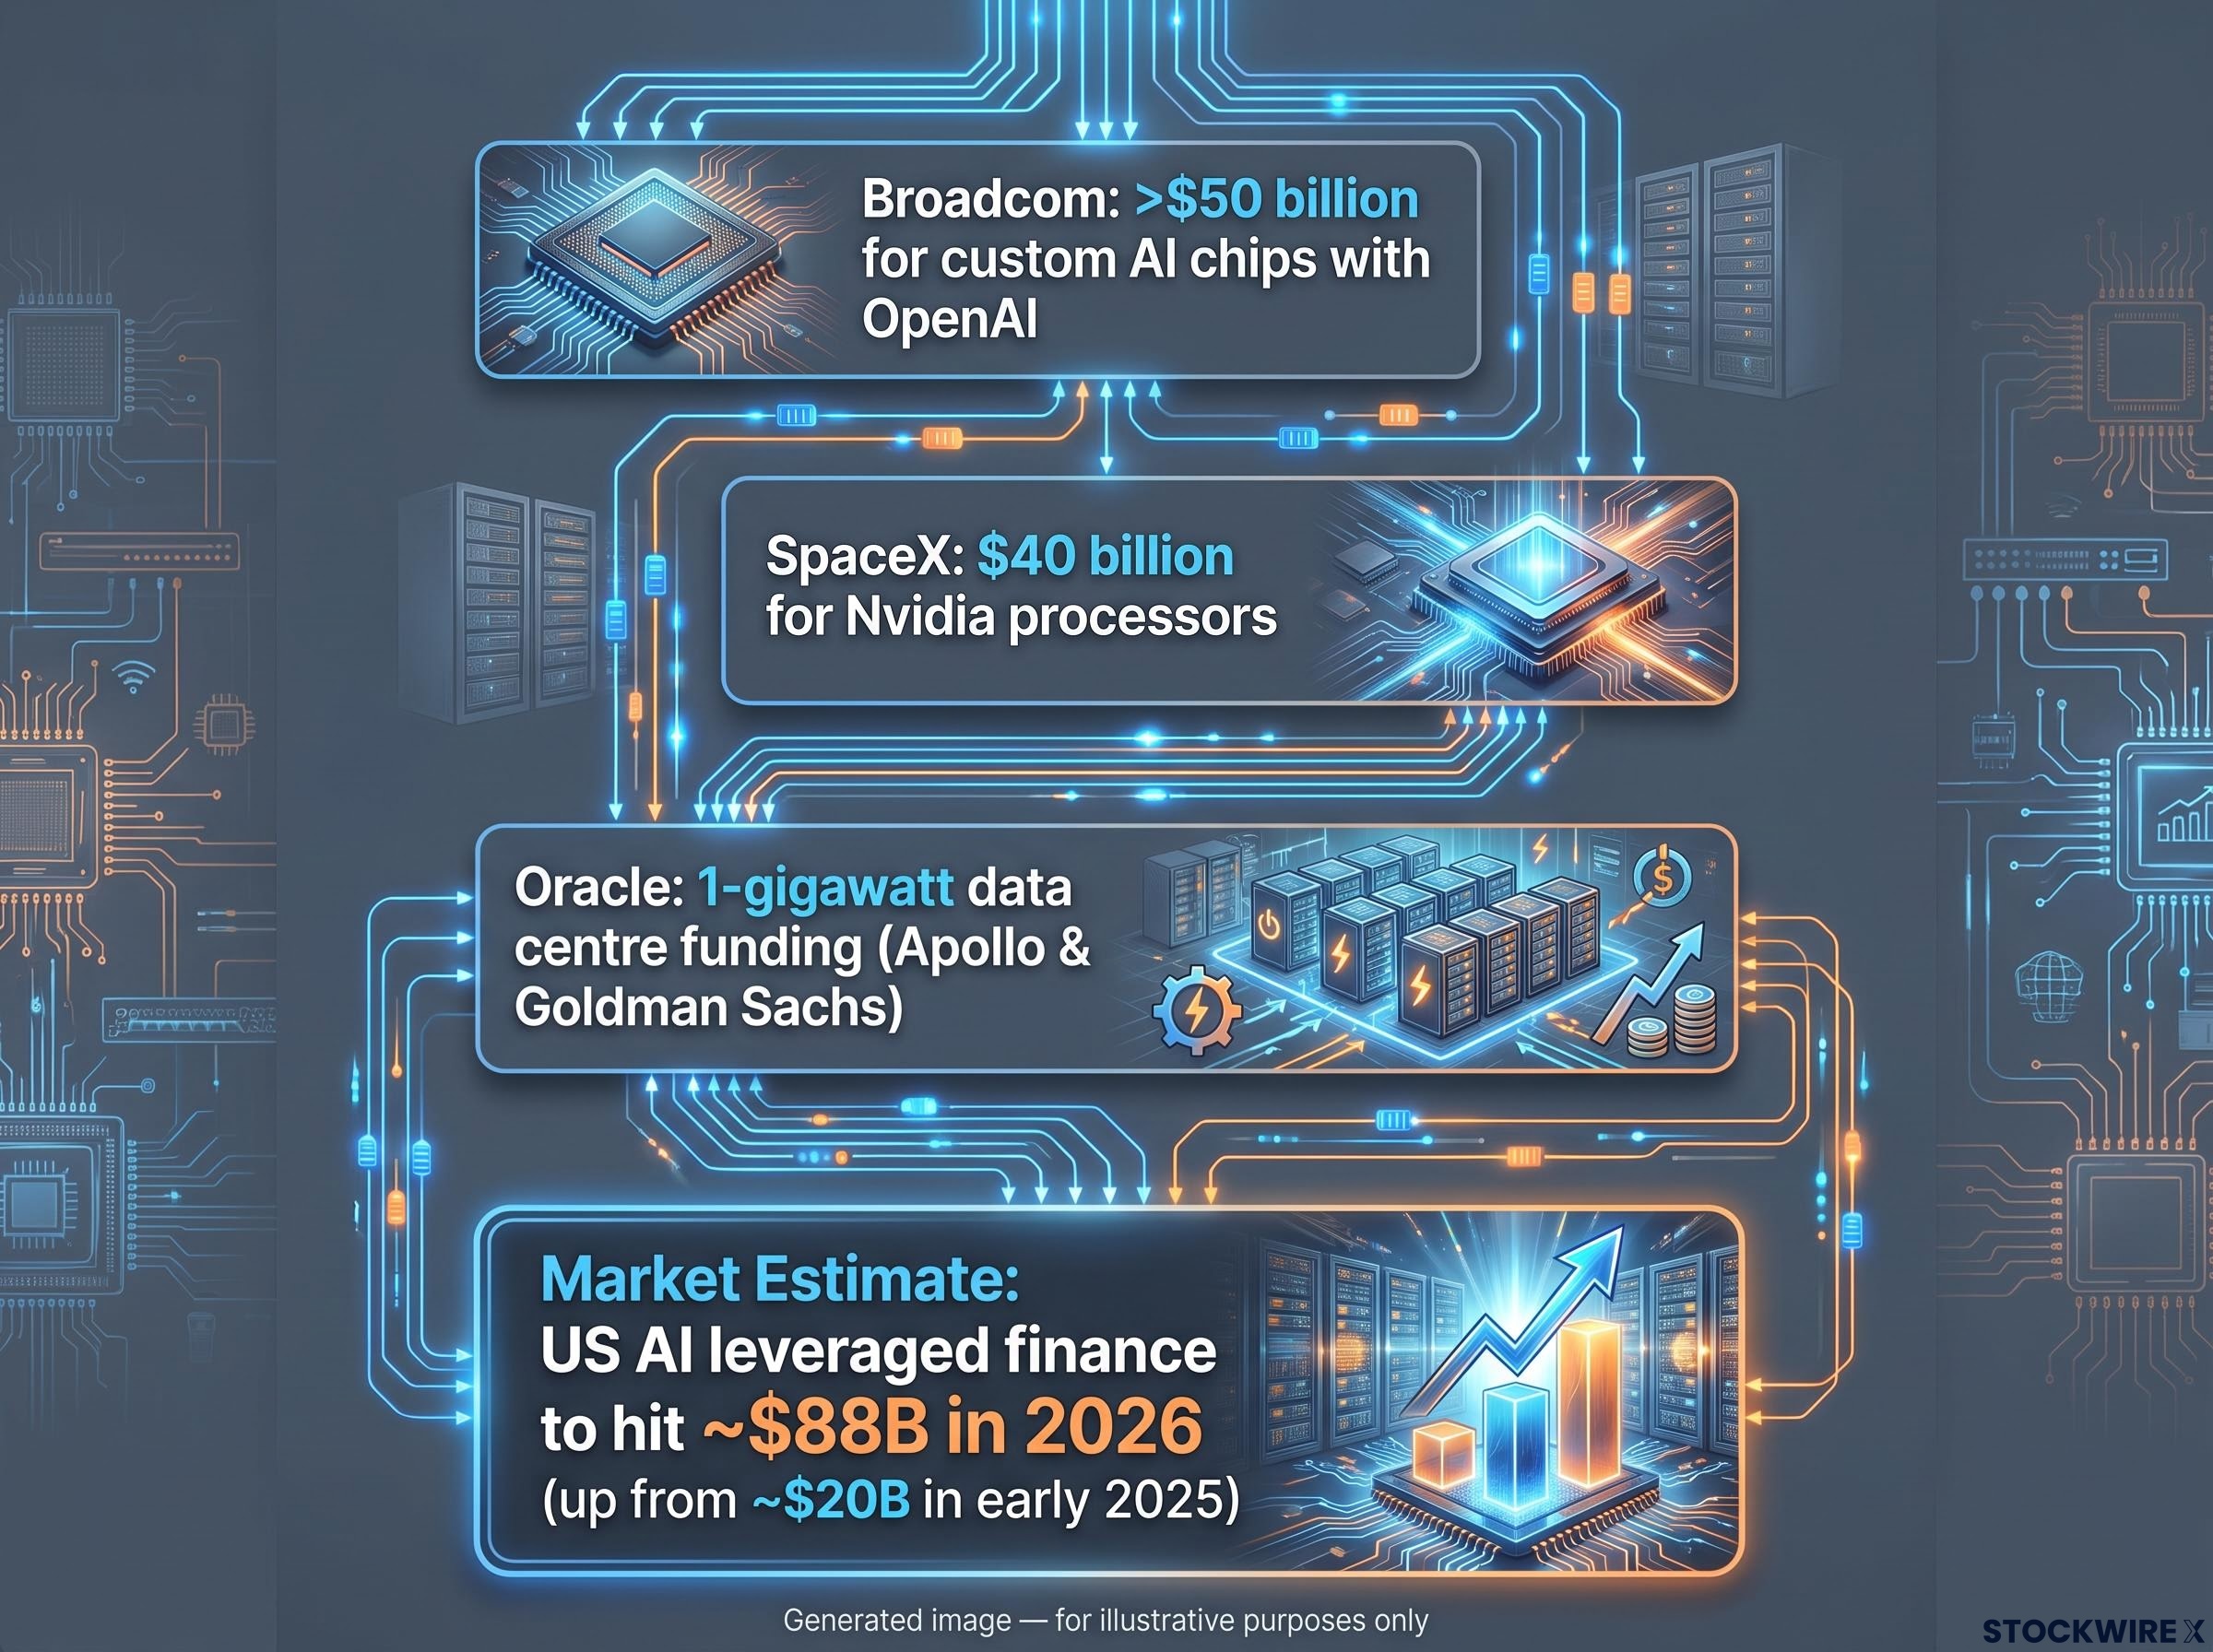
Building AI infrastructure takes enormous sums, and much of it is being borrowed. Broadcom is assembling a debt package exceeding $50 billion to fund custom AI chips co-developed with OpenAI. SpaceX has engaged lenders on a $40 billion debt structure to acquire Nvidia processors. Oracle is in talks with Apollo and Goldman Sachs on financing hardware for a 1-gigawatt data centre, with no precise figure reported.
Every dollar raised through these deals is a dollar of investor capital that might otherwise have bought government bonds. When borrowers compete for the same pool of money, lenders can demand higher returns, and yields rise.
Major institutions increasingly describe this pattern as a structural regime shift, driven by large deficits and AI capital spending competing for the same pool of money, rather than a cyclical pause that will quickly reverse.
Research firm Vital Knowledge said the volume of AI debt makes lower Treasury yields difficult until that momentum fades. One unverified estimate puts AI-related US leveraged finance at roughly $88 billion in 2026, up from about $20 billion in early 2025, though that figure has not been independently confirmed.
What do the Fed minutes and FedWatch odds actually tell you?
The Fed raised rates at its 15-16 September meeting, its first hike since 2023, taking the policy rate to 3.75%-4.00%. The minutes released yesterday added detail on what officials were thinking.
- They said: there was no rush to hike again in October.
- They said: most participants saw another increase as likely appropriate by year end.
- They said: future decisions depend on incoming data.
- They did not settle: whether the September hike was precautionary or aimed at demand-driven inflation, as views differed.
Markets turn that kind of signal into odds through the CME FedWatch tool. FedWatch calculates probabilities from the pricing of 30-day fed funds futures, which are contracts traders use to bet on where the Fed’s rate will land.
| Date | Meeting or event | Probability |
|---|---|---|
| 2 October 2026 | October hike | 17% |
| 5 October 2026 | October hike | About 25% |
| 8 October 2026 | October hold (27-28 October) | About 78% (implies about 22% hike) |
| 8 October 2026 | December hike | About 67% |
Notice how far the October number travelled in under a week. FedWatch shifts with data such as jobs reports and with trader positioning, so treat it as a moving snapshot, not a prediction, and always check the latest reading.
Even so, the current picture is clear. A roughly two-in-three chance of a December hike tells you markets expect higher rates to persist, so your borrowing costs are more likely to stay elevated than fall in the near term.
Educational section: How do yield spreads signal stress, and what does it mean for risk assets?
Yield levels tell you what borrowing costs. Spreads tell you where investors see danger.
Reading a spread: level versus daily change
A yield spread is the extra return investors demand to hold one borrower’s debt instead of a safer benchmark. In the euro area, German government bonds, called bunds, are that benchmark.
When France’s 10-year yields 4.77% and the gap to Germany is 129.79 basis points, that gap is the premium investors want for French risk. Italian yields also rose, which is why analysts watch whether stress spreads beyond one country.
Headlines describe two different measures, and you should keep them apart. The spread’s level recently reached its widest since 2011. Separately, its one-day jump on 8 October was heading for the largest since the 2020 pandemic period before partly reversing.
Higher government yields then travel outward through several channels:
- Mortgages: home loan rates often track longer-term government yields.
- Corporate credit: companies pay more to borrow when the risk-free rate rises.
- Equity valuations: higher yields make future company earnings worth less today.
- Currencies: the bond rout has already spilled into currency markets.
Specific mortgage or credit-spread figures were not available, but the direction is consistent. US stock futures fell this morning, with Dow futures down 262 points (0.5%), S&P 500 futures down 23 points (0.3%) and Nasdaq 100 futures down 154 points (0.5%). Stocks had been lingering near record highs while bonds slumped, a tension you should monitor rather than ignore.
The discount-rate channel explains why your shares can lose value even when company profits are unchanged: higher yields shrink what each future dollar of earnings is worth today, compressing price-to-earnings multiples across the market.
Two readings of the selloff: structural or overdone?
The structural case holds that weaker government finances, large debt stocks and heavy issuance mean investors will keep demanding a higher term premium, the extra yield for locking money up over long periods.
Others see an overshoot. Yields did retreat at points as buyers returned, and FedWatch odds have swung quickly on data.
The cyclical view Oliver Pursche of Wealthspire Advisors described the global bond selloff as “probably overdone”, arguing that yields have reached attractive levels.
History offers some comfort. Unlike the 2010-12 euro-zone crisis, France’s stress is tied to a budget proposal, and the European Central Bank’s tools and euro-area governance are more developed today.
What the selloff changes, and what it does not
The core picture holds steady: pressure on borrowing costs is global, driven by inflation, heavy debt supply and fiscal worries, while the Fed is signalling a possible December hike. What has not changed is how quickly sentiment can move, as the FedWatch swings show.
Keep these signals on your radar:
- The Fed’s 27-28 October meeting and any shift in tone
- FedWatch readings after each jobs report
- French budget developments and the French-German spread
- Oil prices and Middle East supply news
- Quarter-end rebalancing flows
Treat each as a dynamic indicator rather than a verdict. Check the latest data before acting, and match your response to your own time horizon: a five-year mortgage decision and a twenty-year pension allocation call for very different reactions to the same headline.
If yields keep climbing, your equity exposure may matter as much as your bond holdings, because past episodes of defensive sector rotation saw capital move out of technology and cyclicals into staples and healthcare.
Past performance does not guarantee future results. Financial projections and market probabilities are subject to change based on market conditions and various risk factors.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.