US jobs data came in soft, Fed-hold odds rose, and the dollar should have eased. Instead, USD/IDR sits near 17,950 in early European trade on Monday, 5 October 2026, a sign that the Indonesian rupiah is under pressure from forces the US data cannot touch.
The pair has hovered around the 18,000 area, after a 90-day peak near 18,073 in July. Investors are now waiting on Indonesian September reserves and August retail sales.
Misreading the source of this weakness is the costly error. Treat a global fear trade as an Indonesian crisis and you overreact; treat a deeper problem as a passing squeeze and you underreact.
Here is how to separate the global drivers from the Indonesia-specific ones, so you can judge whether this is a temporary risk-off squeeze or something more durable.
Why does the US dollar rise when geopolitical stress builds?
On a day of flare-ups, the screen tells a consistent story: the dollar climbs, emerging-market currencies slide, and the move has little to do with US economic strength. It is driven by fear.
How safe-haven flows work
In risk-on mode, investors are optimistic and buy riskier assets. In risk-off mode, they retreat to assets seen as safe, and the US dollar is the main beneficiary.
That status rests on structure, not sentiment. The dollar is the world’s reserve currency, US markets are deep and liquid, and much of global trade and debt is invoiced in dollars.
| Asset or currency | Risk-on tendency | Risk-off tendency | Why |
|---|---|---|---|
| US dollar | Softer | Stronger | Reserve currency; US debt seen as safe |
| Japanese yen | Softer | Stronger | Japanese government bonds are largely held domestically |
| Swiss franc | Softer | Stronger | Strict banking laws protect capital |
| AUD, CAD, NZD, ZAR | Stronger | Weaker | Reliance on commodity exports |
| Bonds and gold | Less favoured | Favoured | Perceived stores of safety |
Why emerging-market importers suffer most
Emerging-market companies and governments often borrow in dollars. In stress they hedge or repay, which adds to dollar demand and pushes local currencies lower.
Indonesia faces a second pressure. Its non-oil exports must keep offsetting large oil and gas import bills, so firm oil prices and uncertain export demand leave it exposed to terms-of-trade shocks.
What this tells you is that the rupiah’s weakness on a soft US data day is not a contradiction. The safe-haven bid runs on fear, not on American strength.
When big ASX news breaks, our subscribers know first
Soft US jobs data, yet a firm dollar: what the Fed signal does and does not change
On paper, last week’s payrolls report should have hurt the dollar. The numbers, attributed to MUFG/BTMU and CME FedWatch and not independently verified, were weak:
- September nonfarm payrolls rose 29,000, against a consensus of 90,000
- August payrolls were revised down to 133,000
- Unemployment rose to 4.2% from 4.1%
MUFG/BTMU analysts said the report weakened the argument for an October Fed hike. In their view, hiring and firing are both subdued rather than the economy heading into a steep decline, and unemployment edged up because the workforce expanded faster than employment.
Fed-hold odds: CME FedWatch shows roughly an 82% probability of a hold at the October meeting, up from 74% before the report.
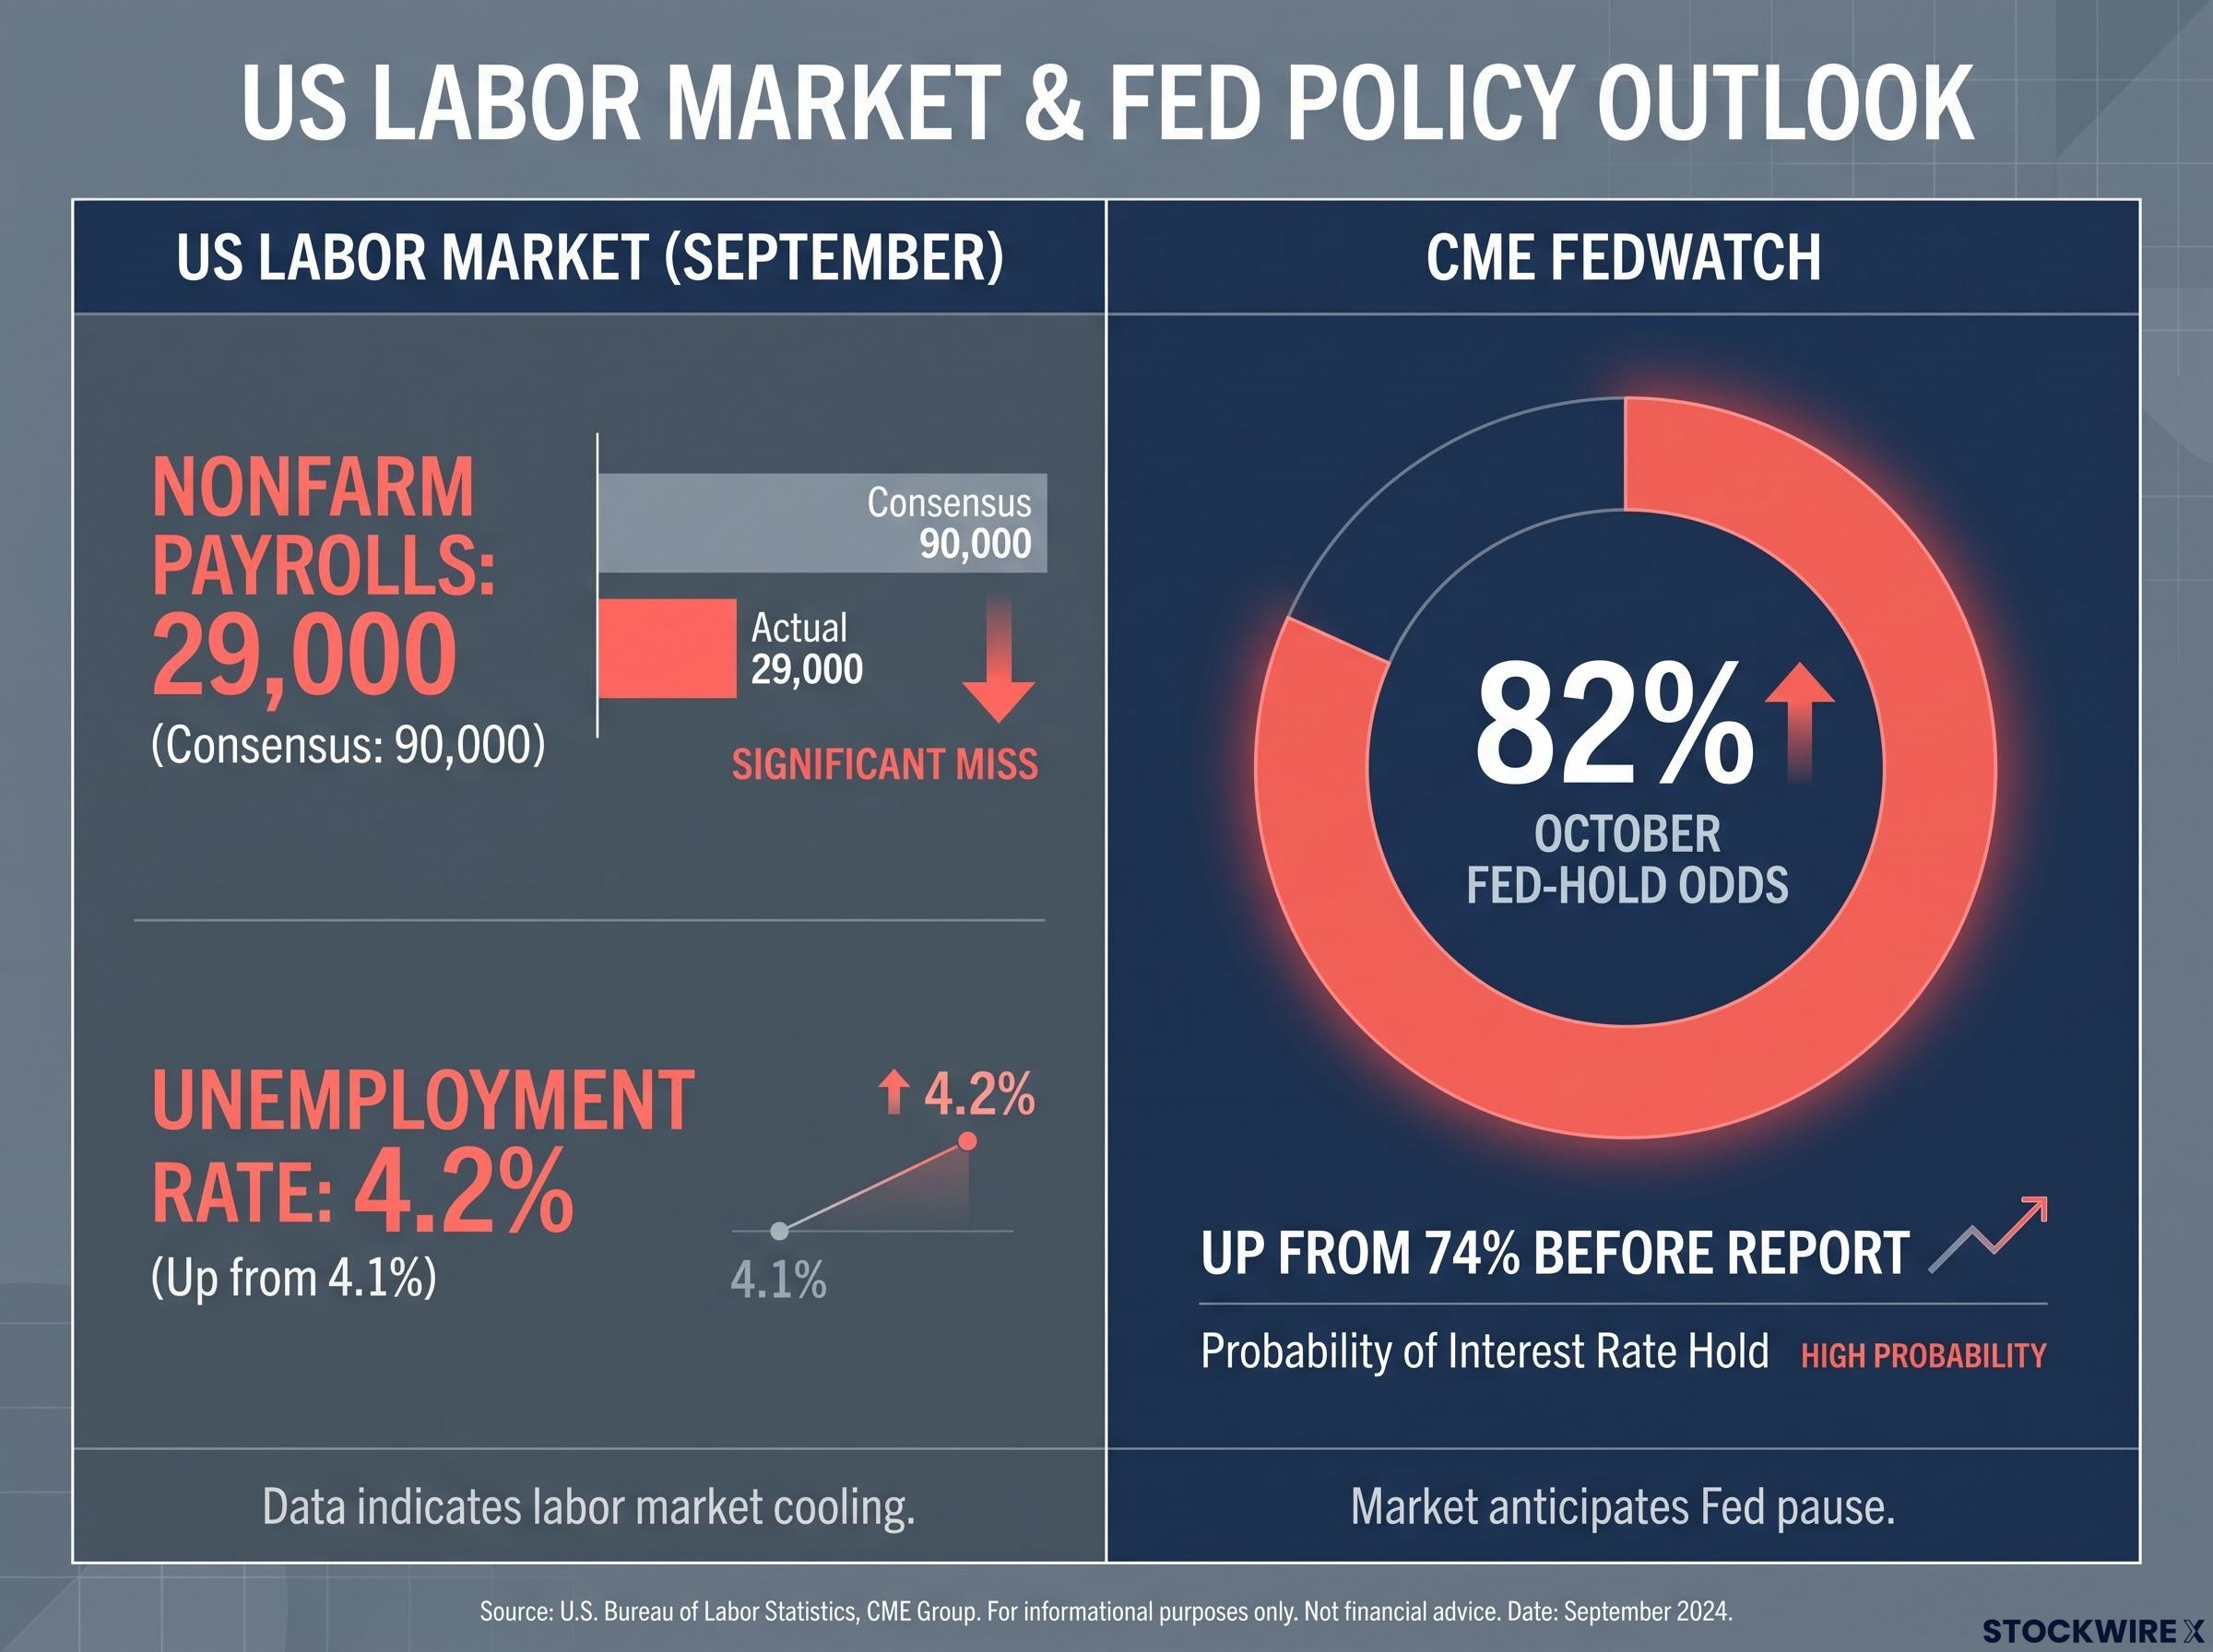
The Fed signal moved in the dollar-negative direction. Yet the dollar held, because Middle East tensions kept the safe-haven bid alive.
One caution applies. Trading Economics refers to expected further Fed tightening, a claim that could not be confirmed and sits oddly beside a hold expectation, so treat it carefully.
For you, the point is that Fed expectations are only one input to USD/IDR. A dovish US surprise does not automatically relieve rupiah pressure while geopolitical risk stays elevated.
For readers wanting to see how rates and the balance sheet shape the dollar, our full explainer on the Fed’s three policy tools details the five transmission channels and their lags.
Middle East tensions and the energy channel into Indonesia
The link from a distant chokepoint to Jakarta’s import bill runs in clear steps.
The geopolitical trigger
Yemeni forces backed by Saudi Arabia have started a large-scale push to win back ground held by the Houthis. The Iran-aligned Houthis have reportedly taken control of the Bab el-Mandeb strait, between the Red Sea and the Gulf of Aden.
The strait is significant because it gives regional oil exporters a way to ship crude without passing through the Strait of Hormuz. AGBI reported on 14 September 2026 that the Houthis were escalating against Saudi Arabia, taking coastal territory and intensifying attacks on Saudi oil infrastructure.
How it reaches Indonesia
- Houthi control of the strait threatens an alternative crude route.
- Tankers from Saudi Arabia to East Asia face longer routes.
- Shipping times and costs rise, and crude supply security becomes a bigger worry.
- Indonesia’s fuel and freight import costs climb.
- A wider trade and current-account gap raises capital outflow risk, weighing on the rupiah.
Indonesia’s exposure is concrete. Its August oil and gas deficit was $2.54 billion, against a non-oil and gas surplus of $6.09 billion.
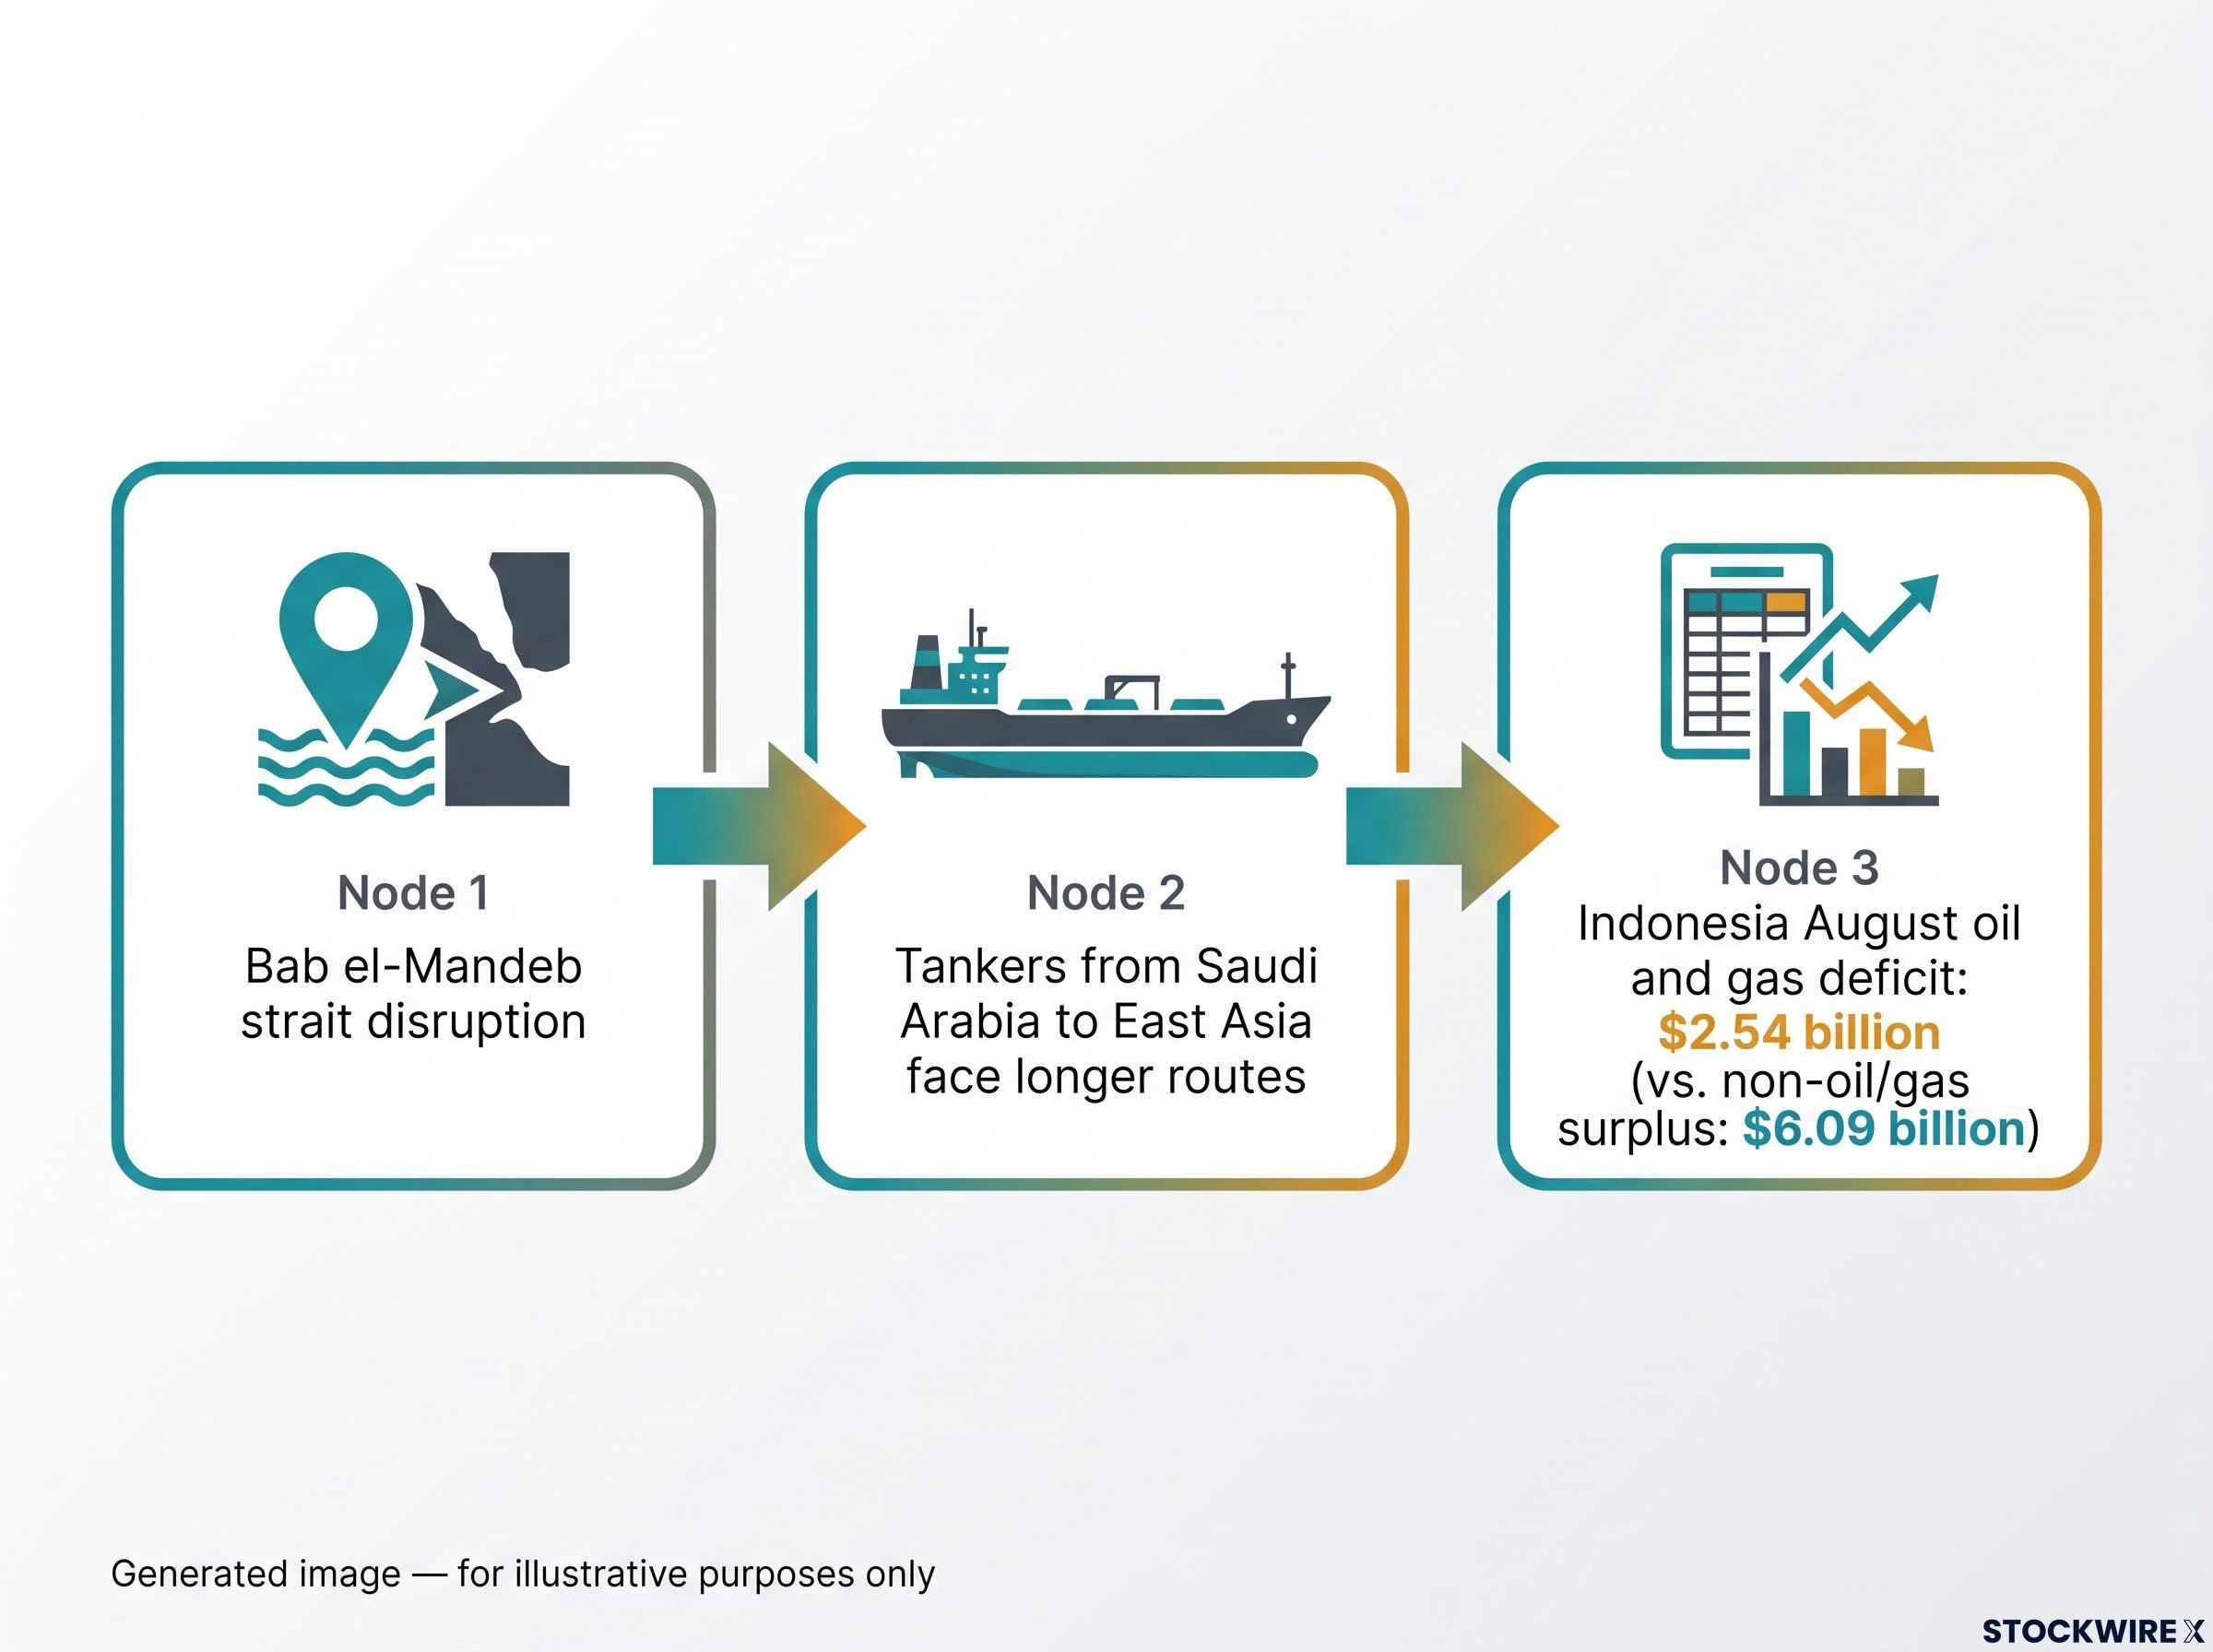
That dependence turns a regional conflict into a direct balance-of-payments risk, which is why the rupiah can react more than many peers.
Brent above $101 carries an oil price premium that Goldman Sachs puts near $14 per barrel, so any energy shock from the Red Sea feeds quickly into import bills for net buyers such as Indonesia.
Is Indonesia’s cushion strong enough? Reserves, the trade surplus and the cracks beneath it
The headline numbers look reassuring. Reserves stood at $146.5 billion at end-August, about 5.4 months of imports against an adequacy threshold of roughly three months.
August’s trade surplus came in at $3.55 billion, far above the roughly $0.6 billion expected. Bank Indonesia (BI) held its policy rate at 5.75% in August and September, citing its commitment to rupiah stability.
Then the details complicate the picture. Imports jumped 19.09% year on year to $23.06 billion, outpacing exports, which rose 6.72% to $26.61 billion.
The January-August cumulative surplus is only about $7.25 billion. Jakarta Globe noted the surplus coincided with a slump in raw-material and capital-goods imports, which raises questions about future production and investment.
| Indicator | Latest figure | Supportive or risk | Why it matters |
|---|---|---|---|
| FX reserves (end-August) | $146.5B | Supportive | Scope to intervene |
| August trade surplus | $3.55B | Supportive | Beat expectations |
| Import growth | +19.09% | Risk | Erodes the surplus |
| Oil and gas balance | -$2.54B | Risk | Energy-price sensitivity |
Some analysts argue the sell-off overshoots fundamentals and reflects broad emerging-market positioning rather than a country-specific problem. Others warn that high global rates and elevated oil can quickly turn adequate buffers into insufficient ones.
Strong reserves make a disorderly collapse less likely, but they do not stop gradual weakness while global risk appetite stays low. No current account figure was available, which leaves a gap in the picture.
Portfolio inflows explain why the rupiah held through a record second-quarter current account deficit, but the same flows can exit faster than they arrived if global risk appetite stays weak.
What to watch next
- Indonesian September reserves (unpublished as of 5 October; release date not confirmed)
- Indonesian August retail sales (date not confirmed)
- The October Fed meeting, with markets leaning towards a hold
- Yemen and Bab el-Mandeb developments, which are open-ended
Reading the rupiah from here: what eases the pressure and what extends it
Three drivers are working together: a safe-haven dollar, an energy channel into Indonesia’s import bill, and a thinning external cushion.
Pressure would ease with de-escalation around Bab el-Mandeb, a clearer Fed path, and reserves that hold up. It would extend if tensions spread, oil costs bite harder, or imports keep outrunning exports.
The likely outlook, if current conditions persist, is continued upward pressure on USD/IDR until tensions ease and US rate expectations stabilise. Reserves and BI’s commitment offer protection.
Treat the 18,000 area as a sentiment gauge, not a verdict on Indonesia’s fundamentals.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. These statements are speculative and subject to change based on market developments.
—