Banxico held its benchmark rate at 6.50% for the third consecutive meeting on 24 September 2026, exactly what markets expected. What markets did not fully price is what came next.
The central bank quietly dropped its forward guidance, severing the earlier signal that rates would stay put and leaving the peso’s next move dependent on structural forces that most coverage has not examined carefully.
That guidance removal is a meaningful shift in policy communication. It signals that the Bank of Mexico (Banxico) is moving from a predictable easing cycle into a data-dependent holding pattern, which changes the analytical framework for anyone watching the Mexican peso.
Whether the currency holds up or gives ground from here depends less on the next rate decision and more on the interaction between Mexico’s real yield advantage, its balance-of-payments fundamentals, and a cluster of external risks centred on US trade and fiscal policy.
This piece builds the framework for assessing whether the peso’s structural supports are durable enough to matter, or whether the risks are the real story. By the time you finish, you will be able to read the currency’s position without leaning on a single carry-trade heuristic.
What Banxico actually signalled on 24 September
The headline was a non-event. Banxico’s five-member board voted unanimously to hold the overnight interbank funding rate at 6.50%, the level it has occupied since May 2026.
Reuters characterised the decision as coming “as expected,” confirming that the hold itself surprised no one.
To understand why the hold mattered, it helps to trace how the rate got here. The 2026 path was a compressed easing cycle followed by an abrupt stop:
- 26 March 2026: a 25 basis point cut, from 7.00% to 6.75%.
- 7 May 2026: a further 25 basis point cut, from 6.75% to 6.50%.
- 25 June 2026, 6 August 2026, and 24 September 2026: three consecutive holds at 6.50%.
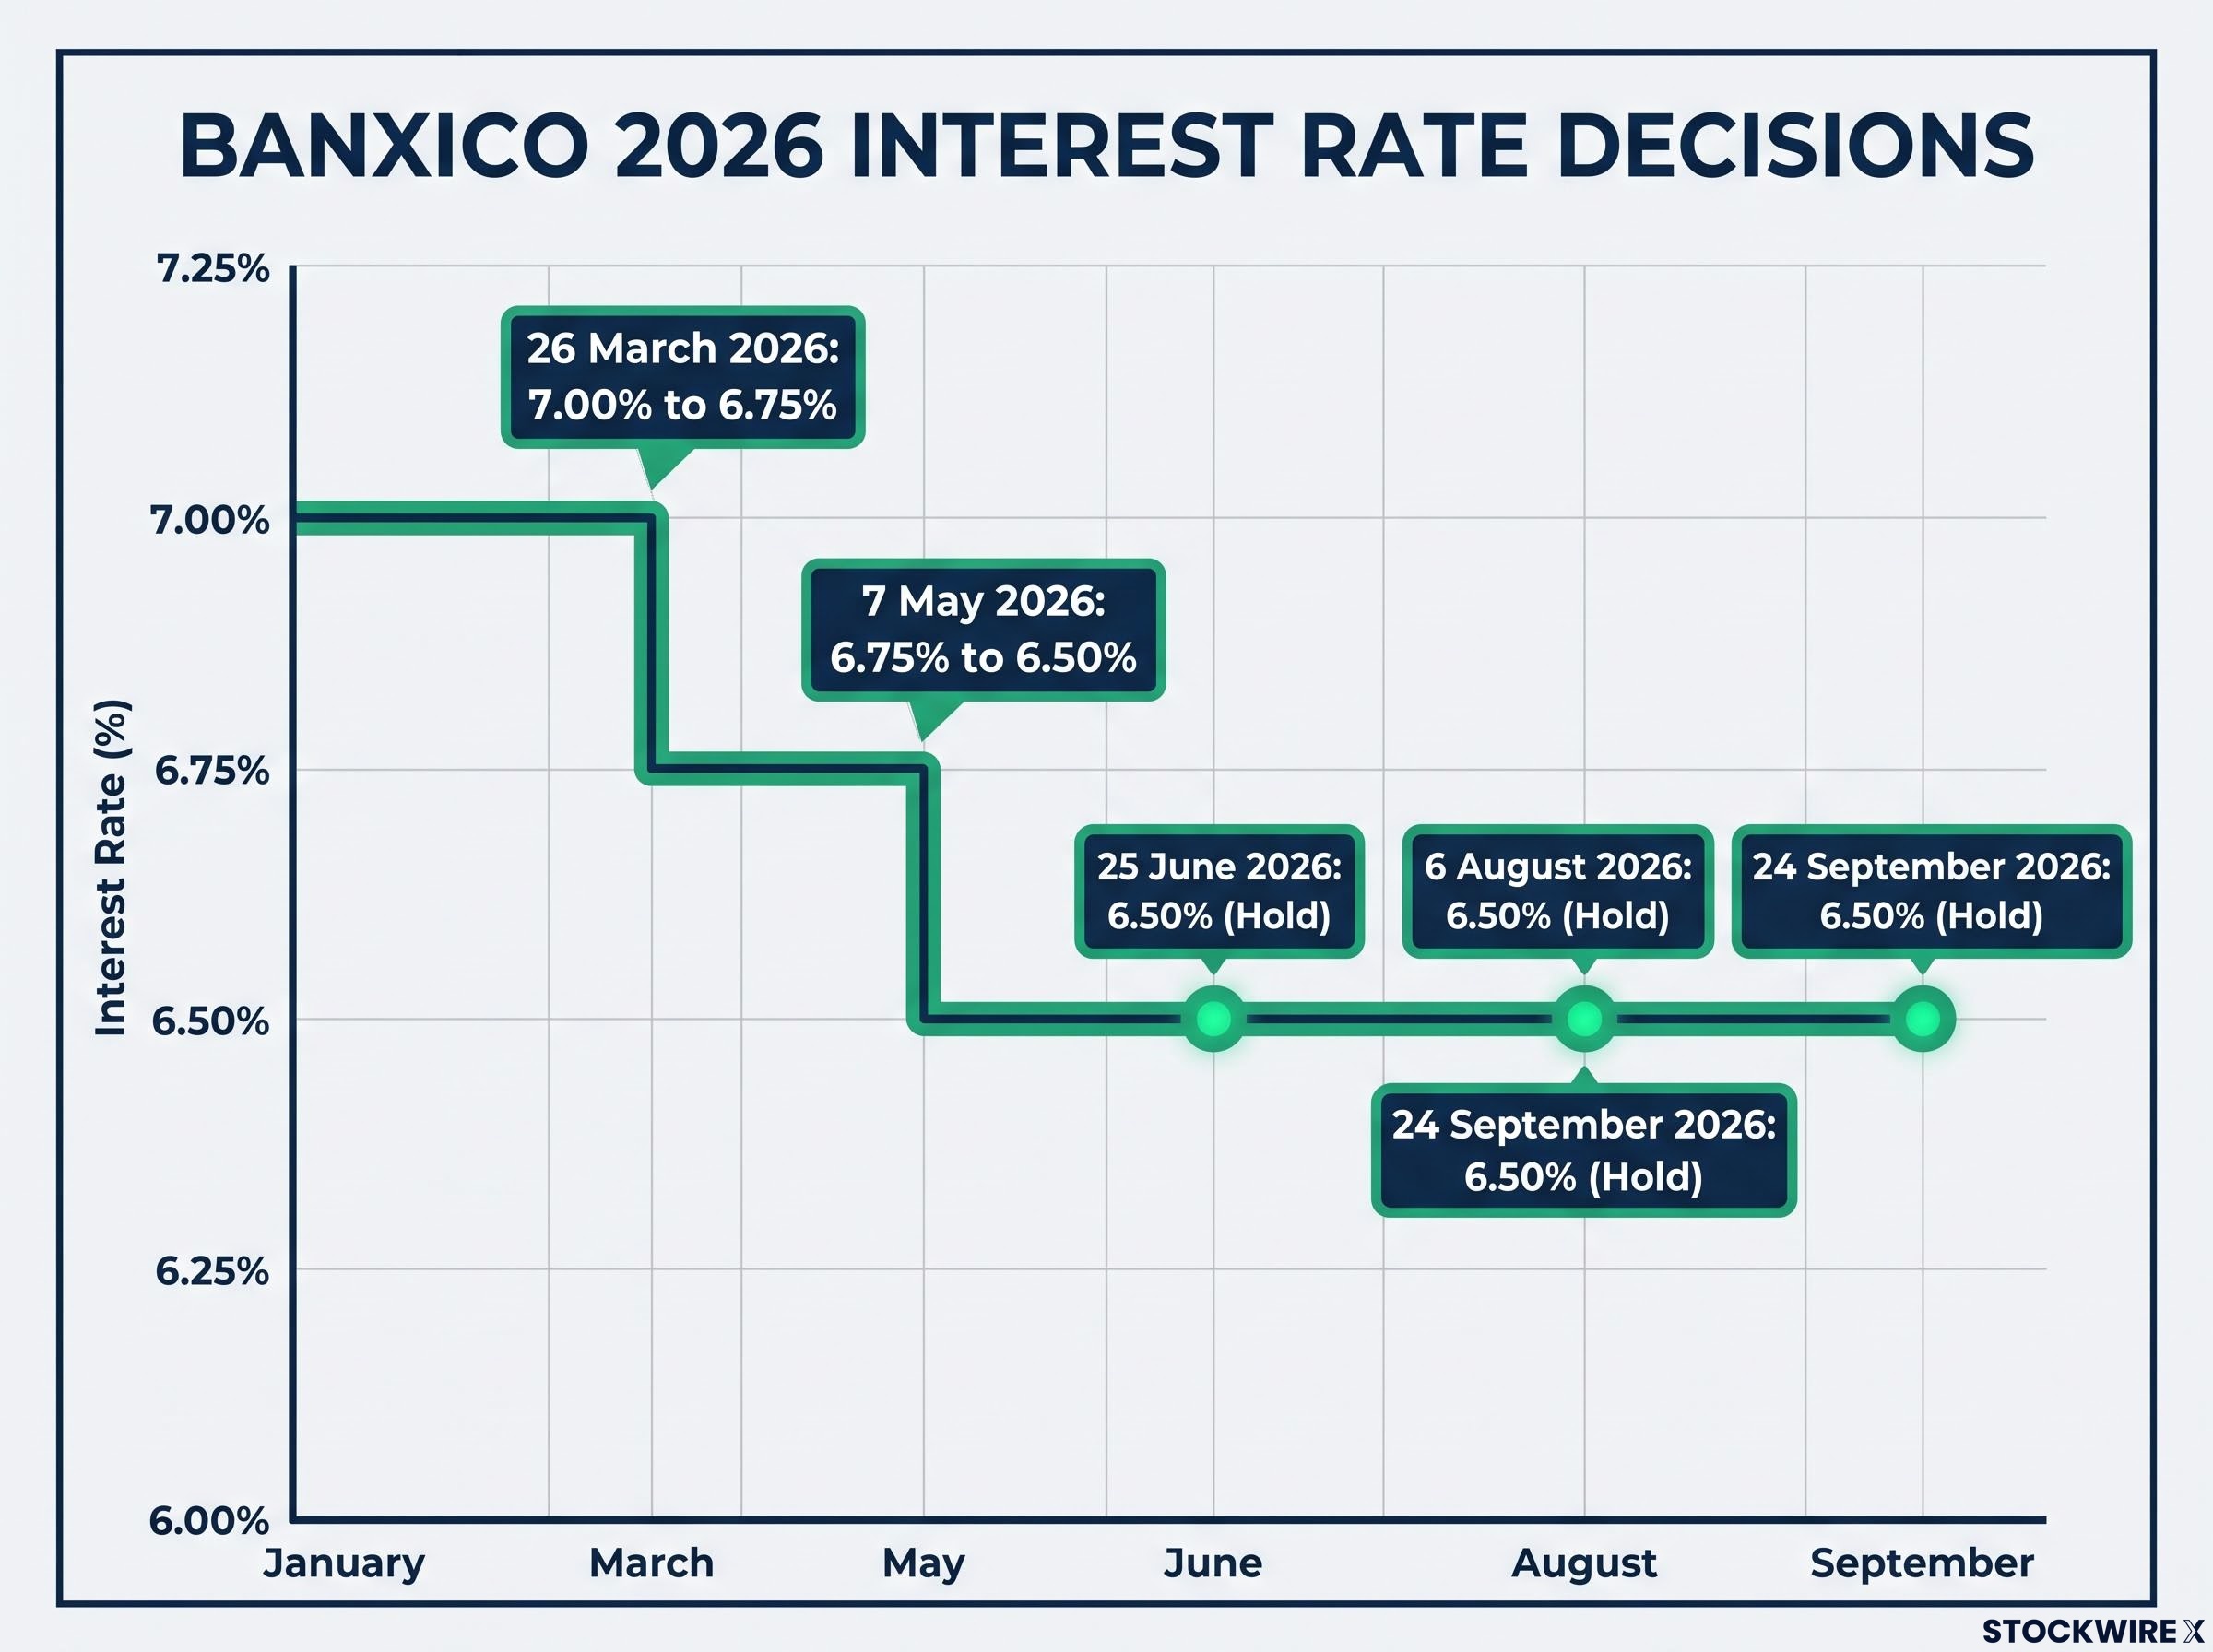
CentralBanking read the June hold as the formal end of the easing cycle. The September meeting is where the communication story actually turned.
Alongside the hold, Banxico dropped the language that had previously suggested policymakers would keep borrowing costs at the current level going forward. Removing that signal is the real news, because it frees the bank to move in either direction without appearing to break an earlier promise.
The bank also affirmed its independence from the US Federal Reserve, indicating it is not obligated to mirror anticipated moves in US rates. Future decisions are now framed as state-contingent rather than date-contingent, tied to what the bank calls an orderly and sustained convergence of inflation to its 3% target.
Here is what that means for you. Swap market pricing at the time of the decision implied roughly 125 basis points of tightening over the following twelve months. That tells you professional money has not closed the door on rate hikes, and the dropped guidance is precisely what makes that repricing possible. Read the September decision as a simple hold and you miss the inflection that opens the door to a more volatile rate path than the prior messaging implied.
When big ASX news breaks, our subscribers know first
Real yields, carry, and why they matter for the peso
Before the structural case makes sense, two concepts need to be clear, because most casual commentary conflates them.
The six Mexican peso drivers operating across different time horizons include the rate differential, remittance flows, nearshoring FDI, oil revenues, US economic conditions, and global risk sentiment, and each operates on a distinct timeline that determines whether any given peso move is structural or cyclical.
The first is real yield. A real yield is simply the nominal interest rate minus inflation, the return an investor actually keeps after rising prices erode purchasing power. With Banxico’s policy rate at 6.50% and Mexican headline inflation at 4.2% year-on-year (the latest reading referenced in the 7 May 2026 statement), Mexico offers a positive real rate of roughly 2.3 percentage points.
That figure is the foundation of everything that follows. In a world where many developed markets offer near-zero or negative real returns, a positive real yield of that size is what makes the peso a structurally interesting destination rather than a purely speculative one. It is the reason professional investors tolerate emerging-market currency risk on the peso at all.
The second concept is the carry trade. In a carry trade, investors borrow in a low-yielding currency and deploy the capital in a higher-yielding one, pocketing the difference. The yield gap drives demand for the target currency, which is why a wide differential tends to support it.
The relevant differential here is between US and Mexican rates. Banxico cut from 7.00% to 6.50% while the Federal Reserve stayed relatively stable, narrowing that gap. Elias Haddad of Brown Brothers Harriman (BBH) identifies this narrowing as a genuine headwind for the peso, though not, in his current view, a decisive one.
The distinction matters for how you weigh the outlook:
- Real yield is the nominal rate minus inflation. Positive real yields attract international capital and support a currency.
- The carry trade rewards the yield gap between currencies. A wider gap pulls capital toward the higher-yielding currency.
- The narrowing differential is a headwind for the peso as Banxico’s rate falls relative to US rates, but it is only one input, not the whole thesis.
Keep that last point in mind. It is the difference between a currency that depends entirely on carry and one with demand that runs deeper.
The structural case for the peso: what analysts are actually pointing to
The bullish argument for the peso is not a single trade dressed up as a thesis. It is a stack of factors, each reinforcing the next.
The base layer is the real yield advantage established above. On its own, a positive real rate attracts capital. But Haddad’s synthesis at BBH is that the peso rests on more than yield alone.
The second layer is the balance of payments. Banxico’s own Quarterly Report for October to December 2025 describes a manageable current-account deficit supported by strong remittances, the money Mexican workers abroad send home. That flow provides a steady, non-speculative source of foreign currency demand that does not depend on interest rates at all.
The third layer is nearshoring, the trend of companies relocating manufacturing closer to their end markets. Mexico’s deepening integration into North American supply chains has drawn both portfolio inflows and foreign direct investment, reinforcing structural demand for pesos that is tied to factories and contracts rather than short-term positioning.
The fourth layer is energy market exposure, which Haddad flags as an additional buffer for the currency.
Haddad’s read is that positive real yields, a favourable balance of payments, and energy exposure are together sufficient to underpin the peso even as the US-Mexico rate differential narrows. He treats the narrowing gap as a headwind, not a disqualifying one.
The following table breaks the case into its component parts, including how exposed each factor is to the rate cycle itself.
| Structural factor | Mechanism | Evidence / source | Sensitivity to rate cycle |
|---|---|---|---|
| Positive real yields | Nominal rate above inflation attracts international capital | Haddad (BBH); Banxico policy statements | High: erodes as the rate falls or inflation rises |
| Favourable balance of payments | Remittances and a manageable current-account deficit provide steady FX demand | Banxico Quarterly Report, Oct-Dec 2025 | Low: independent of interest rates |
| Nearshoring FDI inflows | Supply-chain integration drives portfolio and direct investment | Reuters coverage; Banxico | Low: tied to long-term investment decisions |
| Energy market exposure | Oil revenues and trade linkages act as a currency buffer | Haddad (BBH) | Moderate: sensitive to global energy prices |
What this tells you is where the durability sits. The remittance flows and nearshoring investment are structural and largely indifferent to the rate cycle. The real yield advantage, by contrast, is the layer most exposed to erosion. That distinction is the difference between a currency with genuine structural demand and one that depends entirely on carry to stay bid, and it should shape how much weight you assign to each support.
Where the bullish case breaks down: the conditionalities that matter
None of the structural supports are unconditional. Each can be undermined by a specific risk, and those risks are what turn a confident thesis into a conditional one.
The two risks with the highest structural reach
The first is US tariff and trade policy. Banxico’s Quarterly Report flags downside scenarios from trade renegotiation or sector-specific tariffs that could weigh on Mexican manufacturing exports and investment.
The mechanism is direct. If tariffs reduce the competitiveness of Mexican manufacturing, they weaken the nearshoring and FDI narrative that underpins the peso’s structural demand. The layer that looked most durable in the table above depends on Mexico remaining an attractive place to build for the North American market.
USMCA tariff negotiations entered a new phase when the United States declined to extend the pact on 1 July 2026, activating the sunset clause and converting every subsequent annual review into a discrete risk event for the peso, a structural shift in the trade policy backdrop that is directly relevant to the nearshoring FDI narrative.
The second high-reach risk is domestic fiscal pressure. Banxico has warned that higher public spending commitments combined with volatile oil-related revenues could stress public finances.
Here the threat runs to the real yield anchor. Fiscal slippage could force a choice between defending fiscal credibility and tolerating higher inflation. Either path threatens the positive real rate that sits at the base of the entire structural case.
The secondary risks worth tracking
Beyond those two, a set of secondary risks could compound the picture without necessarily driving it:
- Domestic political uncertainty, particularly debates over energy policy and security that could raise questions about Banxico’s institutional independence.
- Energy price volatility, which feeds simultaneously into inflation, fiscal revenues, and the trade balance.
- Global risk-off scenarios, where a spike in worldwide risk aversion pulls capital out of emerging markets regardless of local fundamentals.
There is one conditionality worth watching above the rest. Reuters reported on 6 August 2026 that Banxico had extended its timeline for inflation to return fully to target, a signal that price convergence is not linear. CentralBanking’s June 2026 analysis reinforces the stakes, warning that perceived political interference or tolerance for higher inflation would undermine the peso’s carry premium despite high nominal yields.
If inflation stays above the 4% upper band for longer, the real yield advantage that supports the whole structural case begins to erode. That is the point at which the conditional nature of the bullish view becomes the dominant frame rather than a footnote.
History offers a sobering coda. Banxico’s own Quarterly Report notes that emerging-market currencies with strong carry, citing precedents including Brazil and South Africa, have still suffered rapid depreciation during global risk shocks. Carry can sustain a currency through gradual adjustment. It cannot prevent a sharp move when global risk aversion spikes.
What the peso’s position tells you now, and what to watch next
Pull the threads together and the verdict is neither bullish nor bearish. The peso has genuine structural backing, but the bullish case is conditional, and the conditionalities are live.
The clearest evidence of that tension is the swap market pricing roughly 125 basis points of tightening over twelve months. That is not the pricing of a settled outlook. It is the market hedging against the very repricing the dropped guidance now permits, with Banxico’s state-contingent language replacing the explicit signal that once anchored expectations.
For a forward view, three variables carry the most weight, in order of priority:
- The pace of inflation convergence toward the 3% target. Headline CPI sits at 4.2%, above the 4% upper band.
- The trajectory of US trade and tariff policy toward Mexico, which determines whether the nearshoring narrative holds.
- Banxico’s institutional independence signals, especially if domestic political pressure on energy or fiscal policy intensifies.
These three are not equally weighted. Inflation convergence is the one that decides whether the positive real yield story stays intact, which makes it the single number to track before any other peso-related signal.
Banxico frames its posture this way: “the reference rate remains consistent at all times with the trajectory needed to enable an orderly and sustained convergence of headline inflation to the 3% target.”
The emerging-market precedent offers a partial roadmap. Real rate credibility and manageable external imbalances are the two factors most consistently linked to currency resilience when carry narrows, as the Brazil and South Africa experiences suggest. They point to a firmer peso as the differential shrinks, without guaranteeing it against a global shock.
For investors wanting to map these structural variables onto a near-term trading framework, our dedicated guide to USD/MXN near-term drivers examines how the Fed hike probability, oil price dynamics, and USMCA negotiation progress interact to set the directional skew across specific price levels.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors, and forward-looking statements are speculative and subject to change based on market developments.