Most macro frameworks still treat the government as a stabiliser of last resort, the actor that steps in only when markets break. The thesis examined here argues something far more unsettling: that the US government has already decided to become a proactive equity market participant, and that the gap between those two assumptions is worth trillions.
That distinction matters because it changes what you are forecasting. A reactive government is a tail risk you hedge against. A proactive one is a structural input you position around every day.
This analysis draws on a thesis formulated roughly two to three years before now, which gives an unusual advantage: the predictive logic can be tested against the legislative record as it actually stands in September 2026. The central question is straightforward. If direct government equity purchases and a US sovereign wealth fund projected at up to $10 trillion materialise as forecast, how should investors recalibrate their models and their sector exposures?
Here is the analytical lens on offer: a structured way to evaluate whether the conditions for intervention are genuinely present, what the international precedent actually demonstrates rather than what proponents claim, and what the investment implications are if even a partial version of this thesis plays out.
Why traditional macro models are no longer sufficient
For roughly 28 to 29 years, the dominant forecasting inputs were macro conditions and structural market flows. Interest rates, inflation, liquidity cycles, positioning. Feed those variables into a model and you generated a reasonable distribution of market outcomes. That framework was reliable because government behaviour was largely predictable and largely reactive.
That baseline is now being displaced. Over the last 18 months, according to the original source analysis by Cem Karsan, government incentives and government actions have become the dominant variable, with the traditional inputs reduced to secondary status. The government is no longer waiting for markets to break before acting.
Consider the leading indicator. The placement of individuals with hedge fund backgrounds at the head of both the Treasury and the Federal Reserve is not treated in this thesis as coincidence. It is read as intent, a signal that the administration intends to engage with markets operationally rather than watch them from a distance.
Then there is the anomaly the traditional model cannot explain.
A roughly 20% equity rally across a two-month window from late March through May, occurring after a decline of less than 20%, has no precedent in approximately 125 years of market history.
A move of that magnitude, following that particular kind of drawdown, simply does not appear in the historical record. If your model treats it as noise, your model is the problem.
The stress signals underneath tell the same story. During the week of the original analysis, the 10-year Treasury yield approached 5.2%, and 30-year Treasury bonds fell nearly 1% in a single day. Those are not the readings of a system that resolved itself.
Bond market interventions that reprice speculative risk rather than anchor yields permanently are a key distinction for reading the long-end moves the thesis flags: a 9-10 basis point drop in the 30-year yield that fully retraces within days is a deterrent signal, not evidence of a failed operation.
Here is what this means for you. If the government has already demonstrated both the willingness and the capacity to engineer a historically unprecedented rally, then anyone still using a pre-2024 macro framework to set expectations is calibrating against the wrong variable. The practical cost is mispriced risk: treat intervention as an anomaly rather than a regime, and you end up systematically underexposed to the upside of policy support and overexposed to the downside of a policy pivot.
When big ASX news breaks, our subscribers know first
What $10 trillion in government equity could look like in practice
The temptation is to read the proposals as a scattered wish list. They make far more sense as a single operational sequence, a coherent programme with a timeline.
The architecture has three connected components. First, a US sovereign wealth fund. Second, so-called “Trump accounts” as vehicles for government-linked equity investment. Third, large-scale quantitative easing directed specifically at suppressing long-end yields. The strategic logic tying them together is competition with China, with capital channelled toward artificial intelligence, infrastructure, and energy.
The fund itself is projected to approach $10 trillion within ten years, potentially sooner. The timing is not vague. 2027 is identified as the key action window, positioned after the midterms and well ahead of the 2028 presidential election, when the political incentives to deploy align most cleanly.
What makes the timing thesis sharp is that some of the tools require no legislation at all. The Treasury General Account, which holds approximately $1 trillion, already exists and can function as a market support mechanism right now. Former Treasury Secretary Hank Paulson publicly warned of an approaching Treasury market crisis roughly four to five months before the original source discussion, urging preparation of a dedicated facility to manage the stress.
The Intel case is the clearest live example of government as co-investor in action: equity acquired through converted federal grants, commercial partnerships brokered from the White House, and policy levers including tariffs and export controls all operated by the same actor holding the stock.
| Tool | Mechanism | Estimated Scale | Timing Trigger |
|---|---|---|---|
| Treasury General Account deployment | Existing cash balance used as market support | ~$1 trillion | Immediate, no legislation required |
| Targeted QE on long-end yields | Bond purchases to suppress yields, engineer real negative rates | Not specified in research | Fed action, crisis-triggered |
| US Sovereign Wealth Fund | Direct equity purchases in strategic sectors | Up to $10 trillion over ten years | 2027 action window |
| Trump Accounts | Government-linked equity investment vehicles | Not specified in research | Aligned with SWF rollout |
The crisis conditions cited as catalysts for all of this are worth listing plainly:
- An unsustainable long-end Treasury yield trajectory
- Collateral risk at scale, with global equity markets estimated near $300 trillion
- China actively working to displace the US dollar as the dominant reserve currency
- Populist political pressure that threatens financial stability without policy mitigation
Here is the read for your positioning. Because the Treasury General Account and targeted QE can move markets without a congressional vote, investors who wait for formal sovereign wealth fund legislation before repositioning may be acting after the structural shift has already happened. The sequencing also matters instrument by instrument: QE on the long end reshapes bond-equity correlations, while direct equity purchases reshape sector valuations and free-float dynamics. Map your exposure to each lever, not just the headline number.
Japan as the working model, and what the US precedent record actually shows
Every intervention thesis needs a template, and this one points squarely at Japan. The original source reports that Japan’s government owns roughly 8% of the Nikkei through its intervention programme, a level of direct state ownership in a major developed equity market that makes the US proposals look less exotic than they first appear.
Japan’s Government Pension Investment Fund (GPIF) held approximately ¥293.4 trillion, around $1.8 trillion, at the end of 2025. That is scale deployed with an explicit stabilising function.
Norway sits at the opposite end of the governance spectrum. Its Government Pension Fund Global (GPFG) held approximately 21,268 billion NOK, around $2.2 trillion, at the end of 2025, with 71.3% in equities spread across roughly 7,200 listed companies globally. Norway is widely viewed as the depoliticised, rules-based standard, capital allocated by transparent mandate rather than strategic direction.
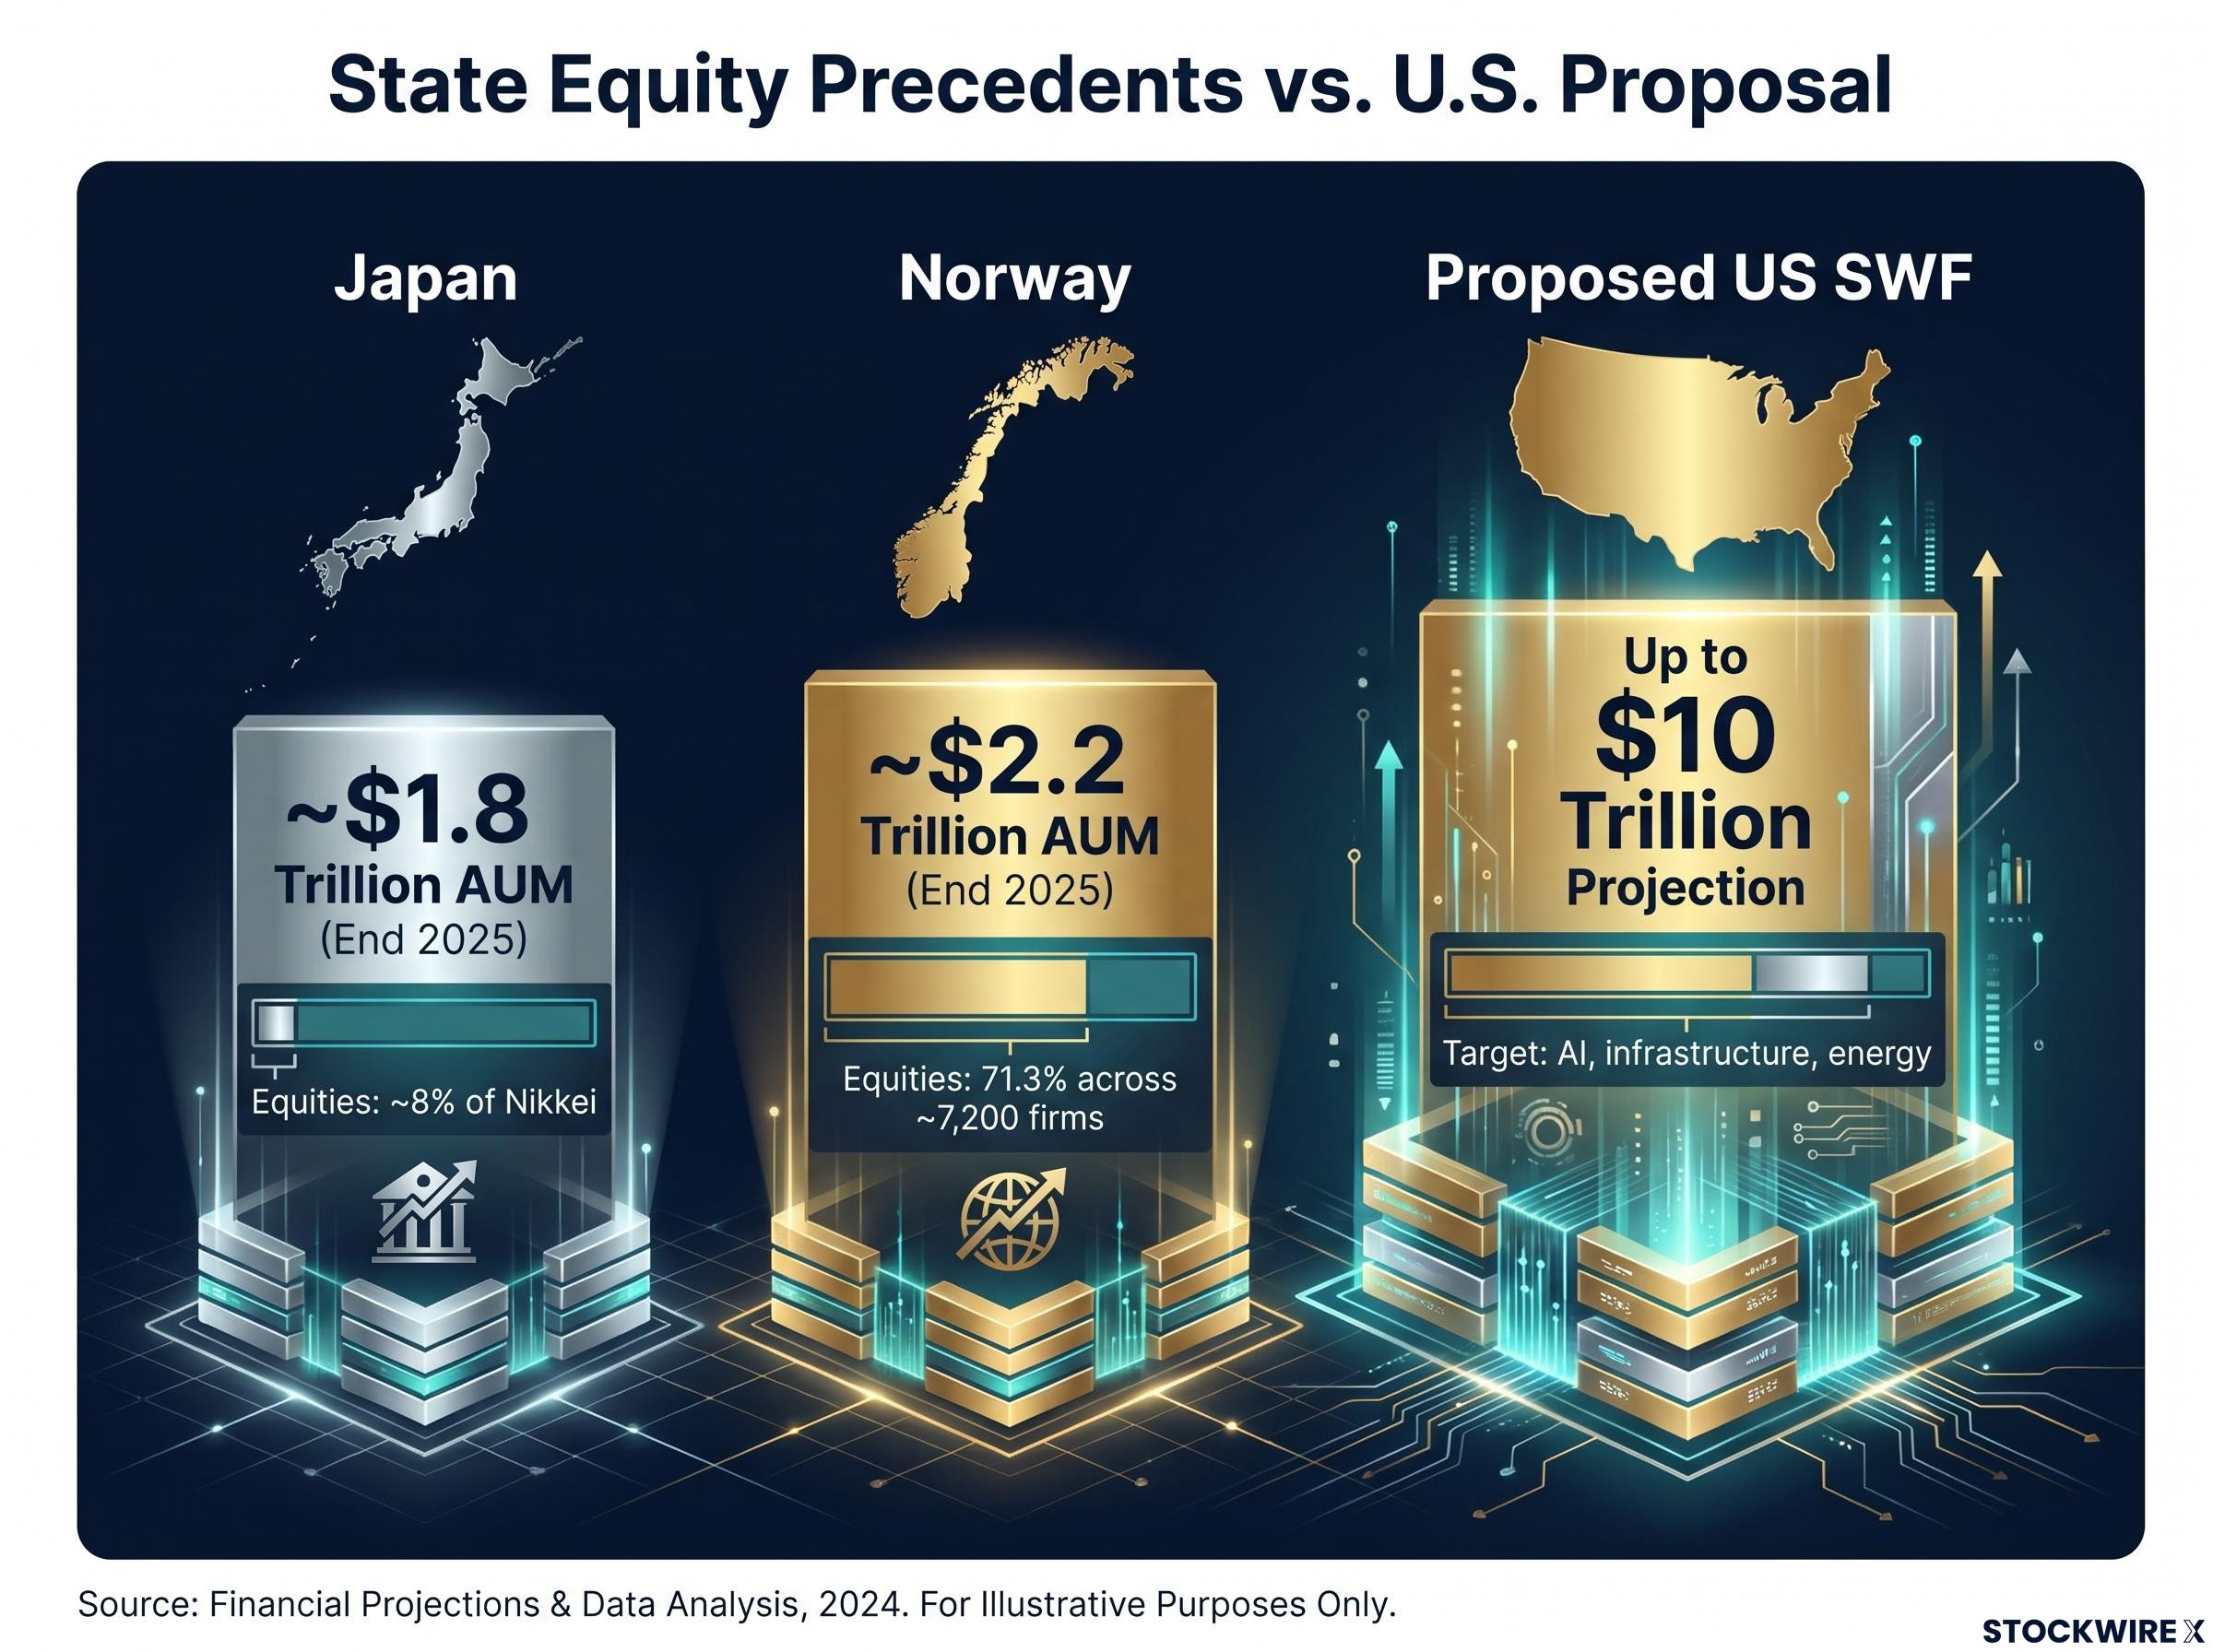
The critical question is not whether government equity ownership works at scale. Japan and Norway both confirm it can. The question is whether it runs through a depoliticised rules-based structure or a strategically directed one, because that governance model determines whether your sector exposure is set by returns logic or by geopolitical priority.
The US has done this before, but only temporarily
The US precedent record complicates any simple “Japan did it, so can America” conclusion. The Reconstruction Finance Corporation in the 1930s and the Troubled Asset Relief Program (TARP) in 2008 both show that large-scale equity-like backstops have genuine American precedent. Both, critically, were designed as time-limited crisis tools built to restore private markets, not as permanent wealth structures.
Singapore and China mark the cautionary points on the spectrum. Singapore’s Temasek and GIC demonstrate how state equity can fund national development while risking concentrated economic power and compromised competitive neutrality. China’s state-guided funds show the ability to mobilise resources at scale alongside the dangers of overcapacity, misallocation, and heavy political overlay on price discovery.
| Country/Entity | Vehicle | Estimated AUM | Equity Allocation | Governance Model |
|---|---|---|---|---|
| Japan | GPIF + direct intervention | ~$1.8 trillion (GPIF) | ~8% of Nikkei via intervention | Directed stabilisation |
| Norway | GPFG | ~$2.2 trillion | 71.3% equities, ~7,200 firms | Rules-based, depoliticised |
| Singapore | Temasek / GIC | Not specified in research | Development-focused equity | State-directed development |
| US Historical | RFC (1930s) / TARP (2008) | Not specified in research | Time-limited backstops | Temporary crisis resolution |
| Proposed US SWF (forecast) | SWF + Trump accounts | Up to $10 trillion (projection) | AI, infrastructure, energy focus | Undetermined (forecast) |
International precedent here is not decoration. It is the clearest available map of the distortions a US fund would introduce. If you understand how Japan’s buying compressed Nikkei risk premia and how Norway’s rules preserved price discovery, you are far better placed to model what a US version would do to S&P 500 sector dynamics.
Where the legislative record stands and what the institutional mainstream believes
For all the projected scale, the legislative reality is sober. The United States has enacted no legislation creating or funding a broad operational sovereign wealth fund. As of September 2026, there are no assets under management. What exists is two stalled proposals.
| Proposal | Introduced By | Current Status | Key Mechanism |
|---|---|---|---|
| American Sovereign Wealth Fund Exploration Act (H.R.3116) | Rep. Morgan McGarvey (D-KY-3), 30 April 2025 | Referred to House Financial Services Committee, no further action | Commission to study a national SWF |
| American A.I. Sovereign Wealth Fund Act (S.4825) | Sen. Bernard Sanders (I-VT), 18 June 2026 | Referred to Senate Finance Committee, not enacted | Excise tax on AI activity, 50% stock transfer to a Treasury trust |
Note what both share: they are exploratory or narrowly targeted, and neither has moved beyond committee.
The gap between the formal legislative record and the operational reality is already closing: positions in Intel, MP Materials, Lithium Americas, and US Steel reveal a US sovereign wealth fund strategy being assembled sector by sector before any enabling statute exists.
The mainstream institutional consensus is equally clear. The Federal Reserve, the Congressional Budget Office (CBO), the International Monetary Fund (IMF), and think tanks including Brookings and the Peterson Institute all treat elevated long-end yields and the national debt as genuine threats. What they do not do is endorse structural equity purchases as the answer. Their prescriptions run through conventional tools: interest-rate policy, balance-sheet management, fiscal consolidation, and medium-term debt planning.
The debate over the fund itself is genuine, and both sides deserve fair framing.
Proponents argue:
- A public fund lets citizens share directly in gains from federally financed research and public data
- A large sovereign fund could act as a stabilising anchor, immune to short-term panic
Critics, including the Cato Institute and the Heritage Foundation, argue:
- Using tax revenue or federal borrowing to buy equities blurs constitutional lines and risks off-budget fiscal policy
- “Too-strategic-to-fail” dynamics create moral hazard
- Political pressure will inevitably distort capital away from its highest-return uses
Here is why the gap itself is investable. The structural conditions the thesis flags as crisis catalysts are real and acknowledged even by the institutions that reject the proposed remedy. But the specific policy response remains unlegislated, with the most advanced proposals still in committee. That means the opportunity and the risk both sit in the timing, not the direction. Dismissing the thesis as fringe ignores acknowledged structural pressure; front-running it as imminent ignores the empty legislative record. The calibrated position lives between the two.
Sizing up your portfolio exposure to a regime you cannot predict precisely
The honest problem is that you cannot forecast the exact policy outcome. What you can do is build a positioning framework that survives that uncertainty.
Start with sectors. The thesis names its own priorities: artificial intelligence, infrastructure, and energy, the industries most likely to receive strategic capital in the competition with China. When the state signals a sector is “too strategic to fail,” it compresses risk premia there. Downside volatility gets dampened, but the informational content of prices erodes, because movements begin to reflect policy rather than private risk assessment.
The valuation link is direct. A referenced Carlyle Group report notes that capital expenditure growth shares a roughly one-to-one correlation with earnings growth, which in turn drives equity valuations for leading stocks. Government capital deployed into AI and infrastructure feeds straight into that chain.
Political influence on stock prices is already embedded in sector pricing dynamics, with announcement timing, equity stake conversions, and deal brokering creating information asymmetries that standard valuation models were not built to detect.
Then there is the plumbing. Large government buy-and-hold positions reduce the free float of targeted stocks, amplifying the price impact of remaining private trades and making those names highly sensitive to incremental flows.
With global public and private equity markets estimated near $300 trillion, a 20% move represents roughly $50 trillion in collateral value. That is the number that makes the stakes tangible, on the upside and the downside alike.
The three variables to keep monitoring
Rather than betting on a specific outcome, track the signals that reveal which version of the thesis is unfolding:
- Sector targeting signals from legislative and executive action, showing where strategic capital is actually being pointed
- Governance model indicators, distinguishing a Norway-style rules-based fund with predictable, transparent weights from a Japan-style or China-style directed model where geopolitical priority sets allocation
- Free-float and liquidity metrics in likely target sectors, where reduced float would confirm intervention is under way
The interpretation for your book is this. If the government deploys even a fraction of the projected $10 trillion into AI, infrastructure, and energy equities, the risk-adjusted case for holding underweights in those sectors weakens considerably, regardless of what a conventional valuation model says. Size your exposure to the probability of intervention, not the certainty of it.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. These statements are speculative and subject to change based on market developments, and past performance does not guarantee future results.
What the thesis gets right regardless of whether the fund arrives on schedule
Strip away the precise timeline and two claims hold firm. The structural pressures the thesis identifies, an unsustainable yield trajectory, collateral risk at scale, and geopolitical competition over the dollar’s reserve status, are confirmed by mainstream institutional analysis, not just its author. And the government has already shown a willingness to engineer market outcomes that the historical record cannot otherwise explain.
The genuine uncertainty sits in the timing and the governance model. As of September 2026, there is no enacted legislation and no assets under management, yet the stress indicators driving the thesis, the long-end yield path, national debt dynamics, and Chinese competition with the dollar, remain live. Acknowledging that uncertainty is not the same as retreating to “too speculative to act on.” The prudent response is to build optionality into sector exposures rather than place a directional bet on a specific legislative date.
As 2027 approaches, a handful of signals will confirm or challenge the thesis:
- Legislative progress on H.R.3116 and S.4825
- Treasury General Account deployment patterns
- Fed communication on long-end yield management
- Any executive action building sovereign wealth fund infrastructure
You do not need to resolve whether a $10 trillion fund arrives on schedule. You need to position for a world in which the pressures that would drive it are already here and are not going away. Track these signals, and you sit ahead of the consensus regardless of how the legislation lands.