Two central banks raised rates by exactly 25 basis points in the same week. One pushed its currency to a 31-year policy high and the market barely blinked. The other set off a yen surge of more than 1% intraday that forced carry traders to scramble for cover.
Same mechanical increment. Opposite market verdicts.
On 25 September 2026, the Japanese yen recorded its sharpest single-session move against the dollar in recent memory, dragging USD/JPY back from a three-week peak near 159.05 to settle around 158.86. It followed a September Bank of Japan (BoJ) decision that lifted rates to 1.25%, the highest since 1995, yet somehow disappointed the hawks. It also followed a summer of escalating intervention warnings and a coordinated yen-buying operation with the United States as recently as July-August 2026.
The cross-rate data confirmed the move was yen-specific: the yen gained roughly 0.88% against the euro and 0.79% against sterling in the same session.
Here is the read on why two identical rate hikes were interpreted so differently, how official intervention threats are reshaping foreign-exchange risk pricing, and what the structural-versus-tactical debate means for anyone carrying yen exposure, funded positions, or international equity holdings.
Why identical rate hikes produced opposite market verdicts
Start with the arithmetic, because the arithmetic is identical. In the same week of September 2026, both the Federal Reserve and the BoJ raised their benchmark rates by 25 basis points. The BoJ’s move took its policy rate from 1.00% to 1.25%, the highest level Japan has seen since 1995.
Mechanically, nothing separates the two increments. Twenty-five basis points is twenty-five basis points. Yet the market treated the Fed hike as part of an entrenched, higher-for-longer regime and the BoJ hike as a reluctant half-step. The gap between those readings is where the real story lives.
Three features made the BoJ decision land as dovish:
- The vote came in at 7-2, with board members Toichiro Asada and Ayano Sato dissenting in favour of holding at 1.00%. Both are described across reports as dovish newcomers, and their dissent signalled internal division rather than conviction.
- The forward guidance framed the hike as a pre-emptive guard against inflation overshooting the 2% target, not as the opening move of a determined tightening cycle.
- The step was fully anticipated. A move everyone has already priced carries no surprise, and surprise is what moves currencies.
The BoJ monetary policy decisions published by the central bank confirm both the rate level and the vote split, providing the primary record against which market interpretations of forward guidance can be checked.
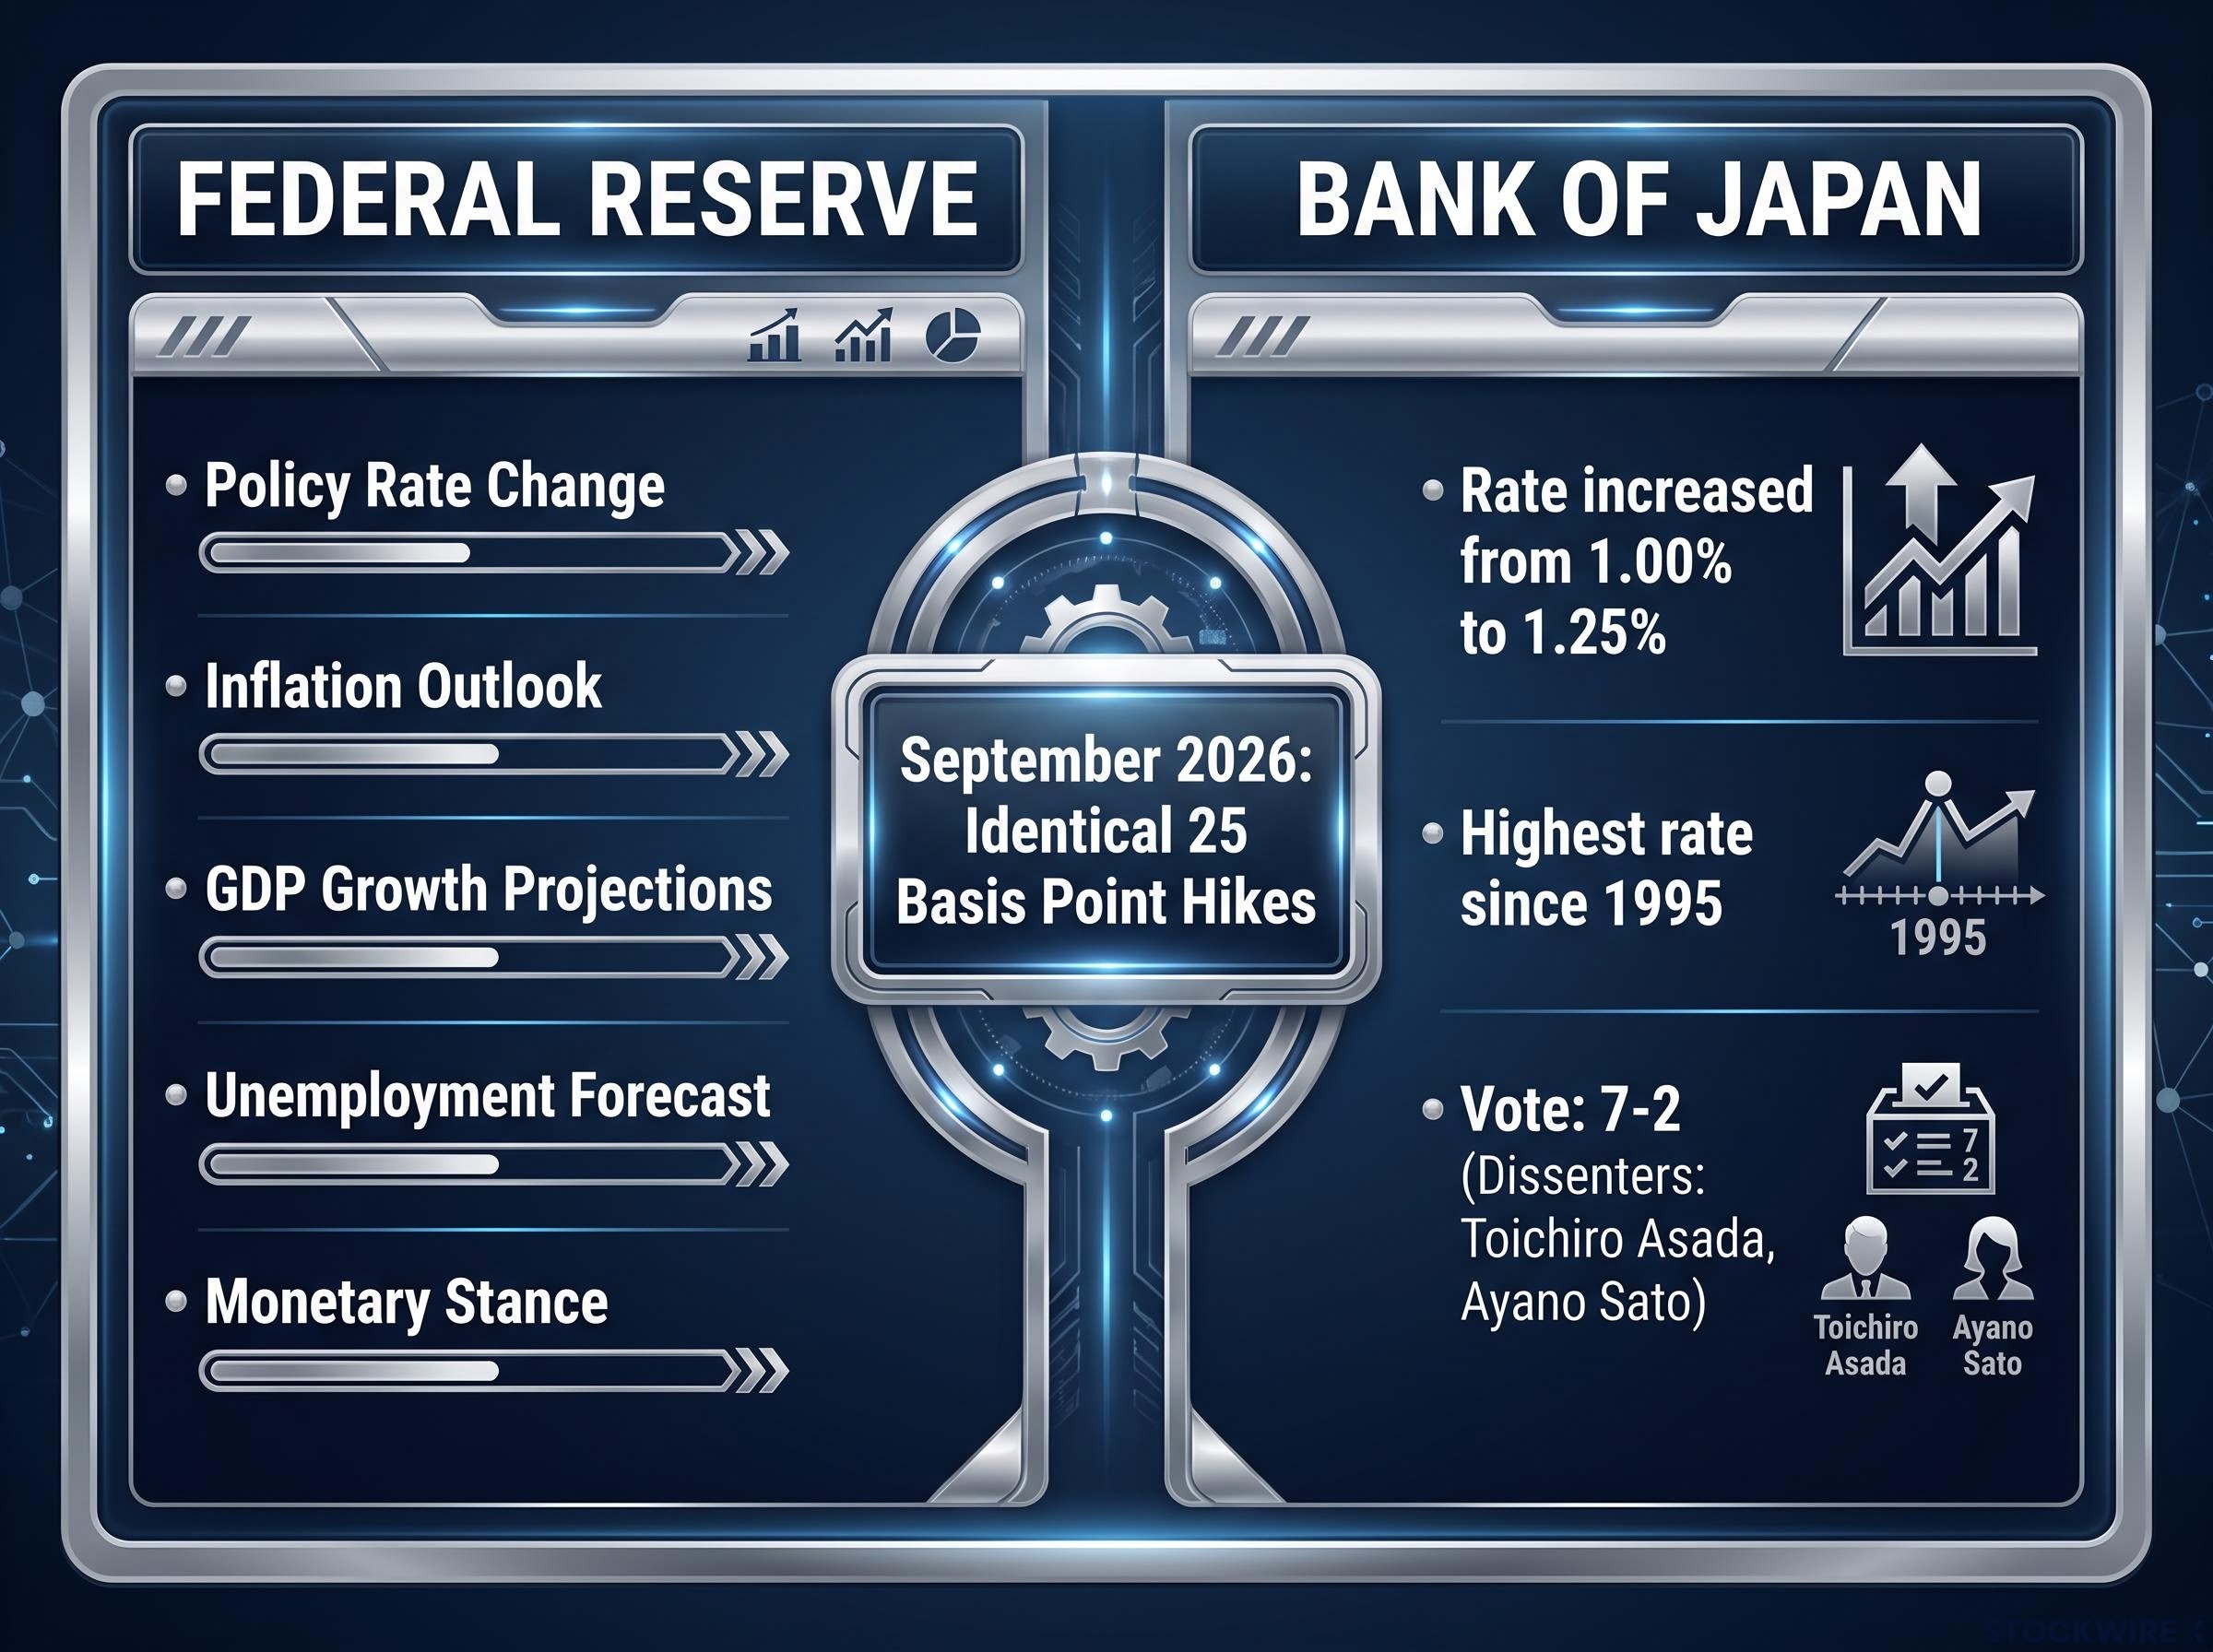
The market delivered its verdict immediately, and it was counterintuitive.
Despite raising rates to a 31-year high, the yen weakened on the day of the decision. USD/JPY climbed toward 156.91 in the aftermath of the 18 September announcement.
That reaction tells you something important: a rate hike on its own does not lift a currency if the surrounding message signals caution. What matters is not the size of the increment but the perceived trajectory behind it. Investors read a slow-walking BoJ, not a central bank chasing the Fed up the rate ladder.
Deputy Governor Himino’s public declaration that the central bank does not need complete information before acting represents a structural departure in the BoJ decision framework, one that lowers the bar for future hikes and changes the risk calculus for anyone treating BoJ inaction as the default base case.
The Fed, by contrast, was already sitting several percentage points above Japan and pairing its increment with rhetoric about keeping rates elevated. Same 25 basis points, entirely different rhetorical weight.
For anyone with internationally exposed positions, the lesson is direct. Anchoring your yen view to the policy rate level alone will mislead you. Credibility and guidance move the currency more than the number on the page.
When big ASX news breaks, our subscribers know first
How intervention threats reshaped the risk calculus for yen shorts
If policy divergence explains why the yen did not rally on the hike, official intervention explains why it eventually surged anyway. Throughout 2026, Japanese officials ran a deliberate campaign of escalating warnings, and the market spent months debating whether the rhetoric was real.
The escalation followed a clear sequence:
- On 30 March 2026, top currency diplomat Atsushi Mimura warned that authorities might take “decisive” yen-buying measures if speculative moves persisted, described at the time as the strongest warning yet.
- In late April 2026, officials issued what was characterised as a “final warning” ahead of possible operations. Government sources indicated it remained in force as late as June 2026.
- On 3 July 2026, Finance Minister Satsuki Katayama reaffirmed that Japan’s stance had not shifted and that Tokyo would act as needed.
The language throughout was deliberately vague on trigger levels, and that ambiguity is itself a policy tool. By refusing to name a line in the sand, officials preserve the element of surprise and force traders to price a non-trivial intervention probability at any exchange rate.
“Our stance has not changed at all,” Finance Minister Satsuki Katayama stated on 3 July 2026, adding that authorities would “respond appropriately at any time as needed.”
Then came proof of concept. The July-August 2026 episode is the anchor reference point for anyone who assumed the warnings were performative.
| Date | Official | Statement / Action | Market Impact |
|---|---|---|---|
| 30 March 2026 | Atsushi Mimura | Warned of “decisive” yen-buying measures | Framed as strongest warning to date |
| 3 July 2026 | Satsuki Katayama | Reaffirmed readiness to act “at any time” | Kept intervention risk live for shorts |
| July-August 2026 | Finance Ministry | Coordinated yen-buying with the US | ~1% yen surge to a three-month high |
The finance ministry confirmed the operation was coordinated with the United States, and afterward stated authorities would “not hesitate to take further action.”
That coordination is the data point that changes the calculation. Unilateral operations can be faded by traders who bet the underlying trend will reassert itself. Joint action with a major counterpart signals a higher threshold of political commitment, and it is harder to dismiss as a temporary speed bump.
The coordinated intervention mechanics behind the July-August 2026 operation reveal why joint action carries a different weight than unilateral yen-buying: the US deliberately sold euro reserves rather than Treasuries, protecting Washington’s bond market from a supply shock while still providing the firepower to arrest the yen’s slide to 40-year lows.
Anyone short yen, or running yen-funded carry trades, is therefore not simply exposed to rate differentials. You are exposed to a sequence of policy actors who have demonstrated willingness to act, have the US alongside them, and have explicitly reserved the right to act again without notice.
What the carry trade actually prices in when the yen jumps 1%
To understand why a 1%-plus yen move rattles markets, you need to understand what a yen-funded carry trade is and why it works.
The mechanics are straightforward. A carry trade involves borrowing in a low-yielding currency, in this case the yen, and deploying that capital into higher-yielding assets denominated in other currencies. As long as the exchange rate stays stable or moves in your favour, you pocket the difference between the cheap funding cost and the higher yield. That difference is the “carry.”
At a BoJ rate of 1.25%, the funding cost remains low relative to dollar, euro, or pound rates. The yield gap versus other major currencies stays substantial, which preserves the core economic case for borrowing yen and buying elsewhere. In pure rate-differential terms, the trade is as attractive as it has been in years.
Carry trade persistence after BoJ rate increases reflects three decades of near-zero rates that embedded yen borrowing into the architecture of global capital flows, a structural depth that explains why a 1.25% policy rate, though historically elevated for Japan, still leaves the fundamental economics of the trade intact.
The problem is the exchange rate assumption baked into it.
In the session under review, the yen gained over 1% against the dollar, roughly 0.88% against the euro, and about 0.79% against sterling. A move of that size can erase days or weeks of accumulated carry income in a single session.
When positions are crowded, the damage compounds. A sharp yen appreciation forces leveraged traders to cover, that covering buys more yen, and the move feeds on itself into a disorderly unwind. Intervention risk turns an orderly trade into a tail-risk problem overnight.
This is exactly where the analyst community splits:
- The tactical view: Recent yen strength is a positioning squeeze. Verbal warnings and occasional operations produce sharp but episodic moves without reversing the underlying weakness driven by rate differentials. Crowded shorts get flushed, then the trend resumes.
- The structural view: The BoJ’s willingness to reach 1.25% and describe the move as pre-emptive could mark the early stages of a genuine exit from ultra-easy policy, gradually narrowing rate gaps and supporting a durably stronger yen.
The reload problem: why carry traders come back even after a squeeze
History points to a recurring dynamic. According to Reuters analysis, once it becomes clear that underlying rate differentials remain wide, traders tend to reload carry positions after an intervention has passed.
That is the trap. The squeeze hurts, positions unwind, and then the same wide yield gap that made the trade attractive in the first place lures capital straight back in.
For anyone with yen-denominated liabilities, internationally funded positions, or cross-asset strategies that embed an implicit yen short, the takeaway is about discipline rather than direction. At 1.25% funding against materially higher yields elsewhere the carry still pays, but the 1%-plus single-session move is precisely why sizing and stop discipline matter more than the yield differential when intervention risk is live.
Reading the broader dollar picture on the day the yen surged
Before assuming the yen’s rally signals broad dollar weakness, look at how the dollar behaved against everything else. The currency heatmap works as a diagnostic here. If the dollar were being sold across the board, most pairs would show it losing ground uniformly.
That is not what happened.
| Currency Pair | USD Move | Direction |
|---|---|---|
| USD vs CHF | ~0.15% | USD gained |
| USD vs CAD | ~0.10% | USD gained |
| USD vs GBP | ~0.19% | USD lost |
| USD vs AUD | ~0.21% | USD lost |
| USD vs EUR | ~0.10% | USD lost |
| USD vs NZD | ~0.01% | USD lost marginally |
The dollar was mixed. It gained against the Swiss franc and the Canadian dollar while losing ground to the pound, the Australian dollar, the euro, and, marginally, the New Zealand dollar. The yen’s gain of over 1% stands as the clear outlier, well beyond the modest moves elsewhere.
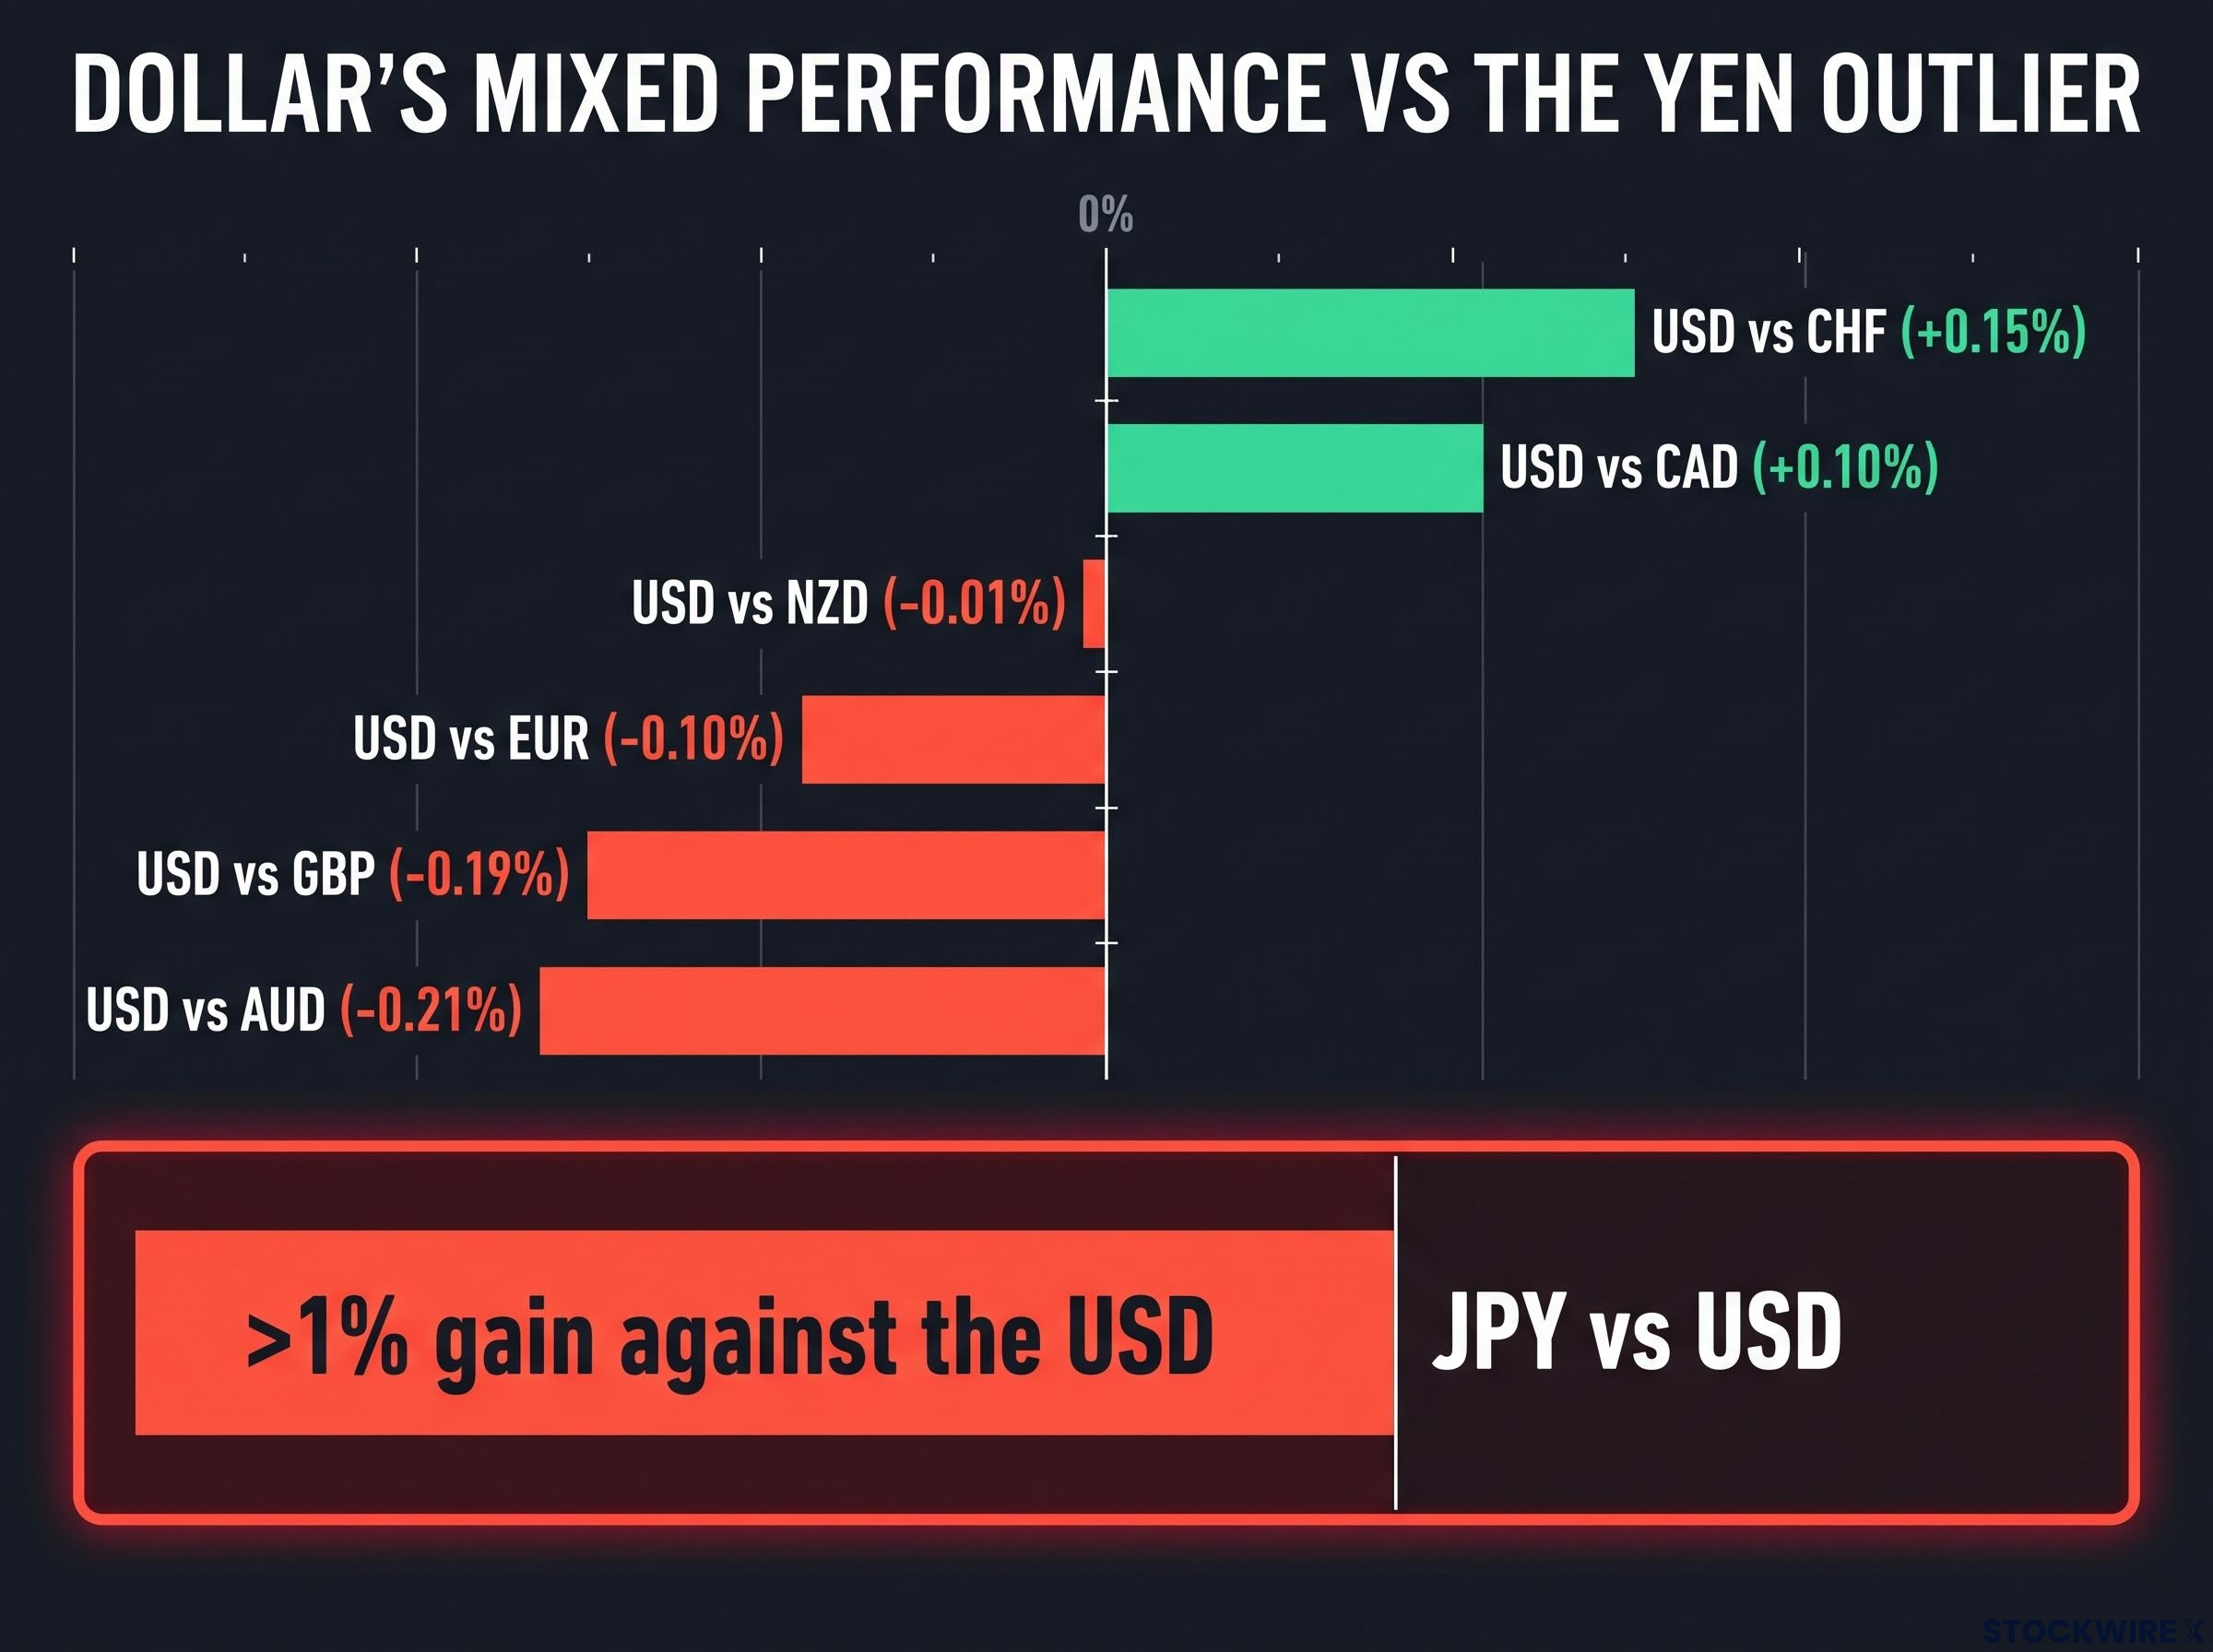
A dollar that was strengthening against the Swiss franc and Canadian dollar while the yen surged over 1% is the evidence that isolates this as a yen-driven event, not a generalised dollar sell-off.
That distinction matters for positioning. The yen’s move against the dollar looks even more striking when you realise the dollar itself was not broadly under pressure. It points to yen-specific catalysts, intervention fear, a positioning squeeze, or both, rather than a shift in overall dollar sentiment.
For anyone holding dollars alongside other major currency exposures, the read is this: yen strength here was not automatically paired with broad dollar weakness that might have offset other holdings. USD/JPY still settled around 158.86 after retreating from the 159.05 high, and the isolation of the yen tells you not to extrapolate a regime change in the dollar from a single yen event.
What the yen’s next move depends on
The honest position now is that the direction is not settled, so the more useful exercise is to identify what would tip the balance. Three variables will determine whether this strength extends or fades:
- The BoJ’s rate path. Watch whether future hikes arrive with firmer forward guidance and fewer dissenting votes. The current 7-2 split, with two dovish newcomers voting to hold, is a proxy for how much internal conviction actually sits behind the tightening.
- Intervention follow-through. The rhetoric has been backed by action once already. Whether officials keep warning, and whether they act again, will shape how much intervention premium stays priced into the yen.
- The US-Japan rate differential. As long as the gap between US and Japanese yields stays wide, the structural case for a stronger yen remains conditional.
The most market-relevant forward signal came from the top of the central bank.
BoJ Governor Kazuo Ueda has linked yen weakness and imported inflation to the case for further rate hikes, indicating that a soft currency could itself justify tighter policy in the months ahead.
Frame every new data point through the structural-versus-tactical lens. A yen move that coincides with softer US data or a genuinely hawkish BoJ surprise deserves a different read than one triggered purely by positioning or a fresh intervention scare.
The reload dynamic keeps the outcome open. If the next meeting produces a hawkish surprise, fewer dissenters, stronger guidance, alongside intervention warnings backed by action, the structural thesis gains credibility. If the familiar pattern holds, hike, cautious language, yen weakens, carry traders will reload and the cycle continues.
Positioning for yen volatility without betting on a single outcome
Pull the evidence together and the two interpretations do not resolve into one. They coexist, and both have legitimate support in the data.
- The tactical camp reads the recent surge as a positioning squeeze driven by intervention fear. Under this view, size for a short-lived move, expect the trend to reassert, and treat rallies as opportunities rather than regime shifts.
- The structural camp reads it as the early signal of a durable shift as the BoJ inches out of ultra-easy policy. Under this view, treat yen strength as something that could persist and compound.
The reason you cannot cleanly pick one is the rate itself. At 1.25%, the BoJ policy rate is historically elevated for Japan yet still structurally low relative to peer economies. That single fact keeps both stories alive at once.
So the useful conclusion is not a directional call. Yen risk is repricing upward in both directions. The carry trade is more attractive in rate-differential terms than it has been in years, but the confirmed July-August coordinated intervention and the policy backdrop mean the cost of being wrong on direction is also higher than it has been in years.
For readers with any exposure to yen-linked assets or funding, that converts the session’s noise into a clear framing: make your yen exposure explicit, size for volatility rather than direction, and monitor the three variables identified above. The session’s move from 159.05 to 158.86 against a mixed dollar backdrop is a reminder that the yen now demands to be priced as a live risk factor, not treated as a quiet funding line.
For readers wanting to understand how Japan’s Ministry of Finance decides when to act, our full explainer on USD/JPY intervention triggers examines why velocity rather than price level is the operative threshold, with Goldman Sachs quantifying how a 3% intraday gap can erase an entire year of carry returns in one session.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
Past performance does not guarantee future results. Financial projections are subject to market conditions and various risk factors. These statements are speculative and subject to change based on market developments and central bank policy.