

IDP board rejects Blackstone’s $2.50 bid as opportunistic and undervalued
IDP Education Limited (ASX: IEL) has confirmed it received and rejected an unsolicited, confidential, non-binding and indicative proposal from Blackstone Singapore Pte Ltd, acting on behalf of funds managed and advised by Blackstone Inc. and its affiliates, to acquire 100% of IDP shares via a recommended scheme of arrangement at $2.50 in cash per share. The proposal was received on 9 September 2026 and subsequently rejected. This followed an earlier Blackstone proposal at $2.30 in cash per share, which was also rejected.
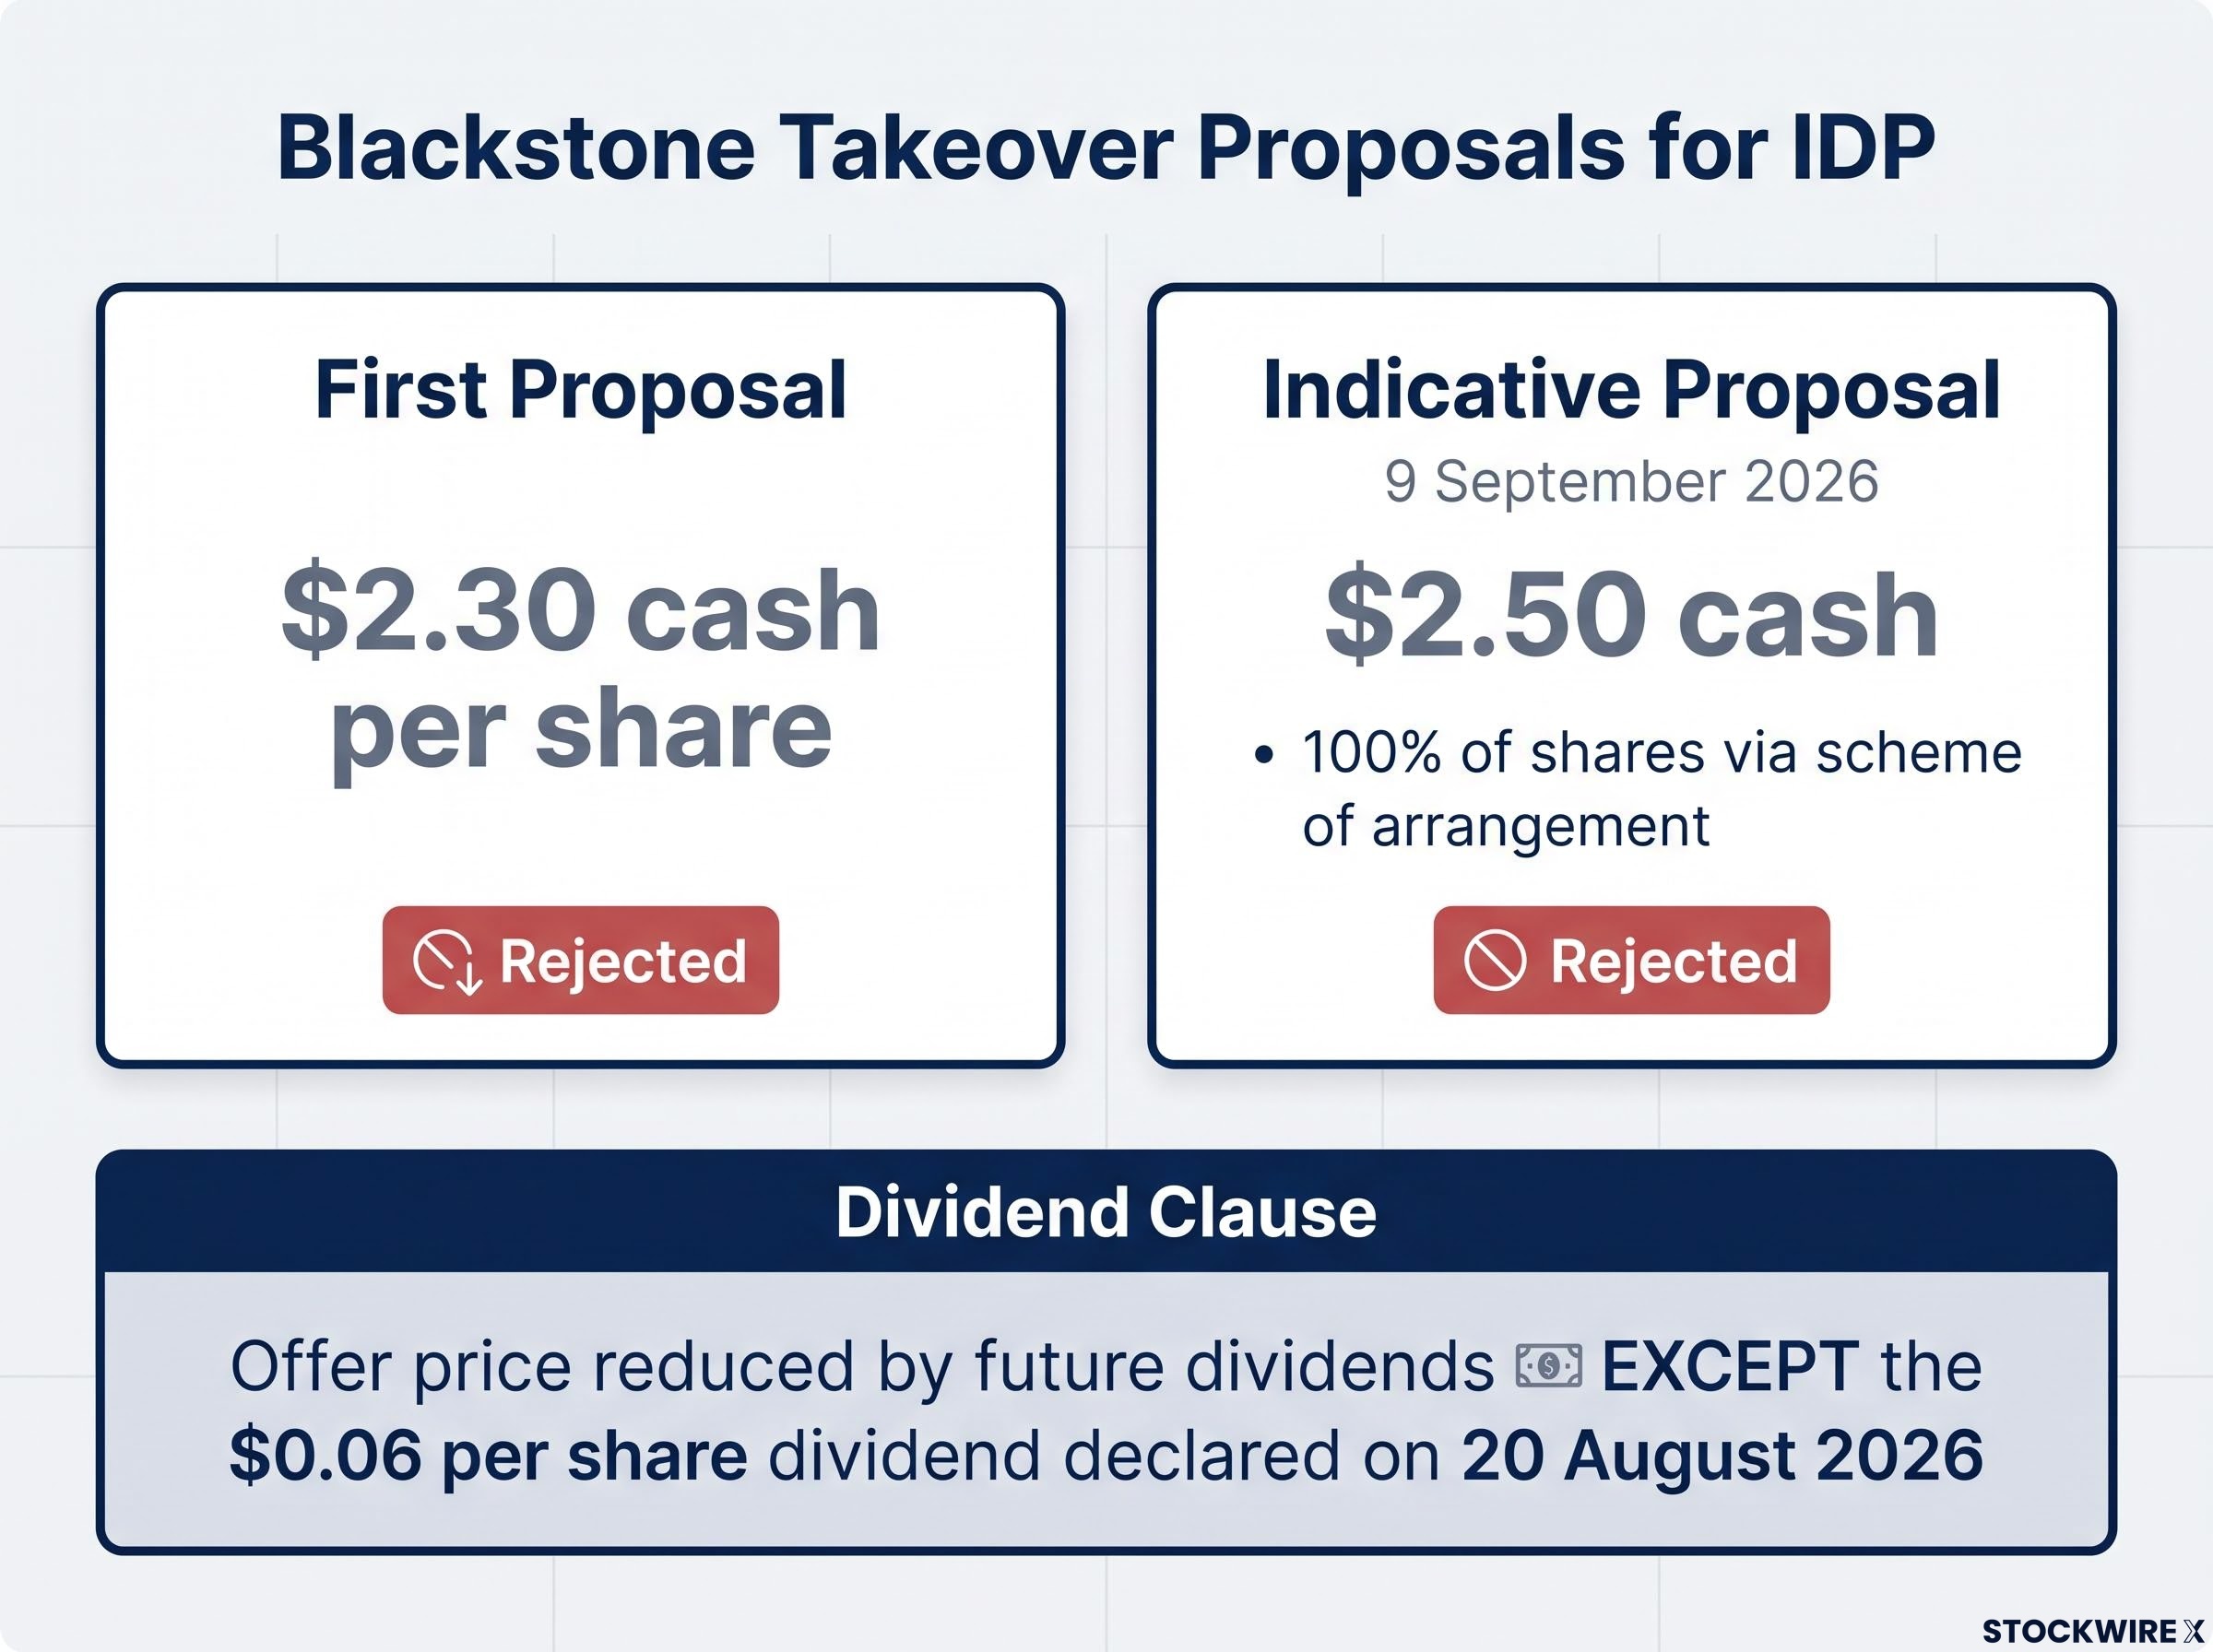
The $2.50 Indicative Proposal was confidential, non-binding, and indicative. The price payable under each would have been reduced by the amount of any future dividends or distributions declared or paid by IDP prior to implementation, with the exception of the $0.06 per share dividend declared and announced by IDP on 20 August 2026, which is explicitly excluded from this reduction clause. IDP is being advised by Goldman Sachs as financial adviser and Mallesons as legal adviser.
When big ASX news breaks, our subscribers know first
Why the Board said no — and why it matters
The IDP Board’s rejection was direct. Its stated position was that the $2.50 indicative proposal fails to reflect the underlying worth of the business.
The Board stated its view that the Indicative Proposal fails to reflect the fundamental value of IDP’s market-leading global platform, substantially undervalues IDP and is not in the best interests of its shareholders.
The Board characterised the timing of the approach as “highly opportunistic,” citing current industry conditions and the fact that IDP is “part way through a multi-year transformation” to position the business for future growth. Reinforcing the undervaluation argument, the Board noted that IEL shares traded above the $2.50 offer price as recently as late June 2026.
IDP’s $50 million share buyback, launched in June 2026 alongside an upgraded cost reduction target of $30 million, was an explicit signal from management that it regarded its own shares as undervalued well before Blackstone’s approach arrived.
The terms attached to the Indicative Proposal also drew scrutiny. Conditions included:
- A four-week period of hard exclusivity with no fiduciary out
- Final Blackstone investment committee approval
- Due diligence and documentation
- Regulatory approvals
- Unanimous IDP Board recommendation
These conditions were not merely procedural. In particular, the demand for hard exclusivity with no fiduciary out would have prevented IDP from considering any competing offer during the four-week window.
| Proposal | Offer Price (per share) | Structure | Status |
|---|---|---|---|
| First Proposal | $2.30 | Unspecified | Rejected |
| Indicative Proposal (9 Sep 2026) | $2.50 | Scheme of arrangement | Rejected |
Understanding scheme of arrangement bids — what investors should know
A scheme of arrangement is a court-approved mechanism by which an acquirer can purchase 100% of a listed company’s shares. It requires approval from shareholders (typically 75% in value and 50% in number) as well as court sanction before it can proceed.
The $2.50 Indicative Proposal was described as “non-binding and indicative,” meaning Blackstone carried no legal obligation to proceed with a formal offer. The Board’s rejection means no formal bid has been made, and IDP shareholders have not been asked to vote on anything.
The demand for hard exclusivity with no fiduciary out deserves specific attention. Under such a condition, IDP would have been prohibited from considering any competing proposal during the four-week exclusivity period, even if a superior offer emerged. This is regarded as an aggressive condition in takeover negotiations, and the Board’s refusal to accept it represents a substantive act of shareholder protection rather than a purely procedural decision.
Transformation underway — the Board’s investment case for staying the course
The Board’s rejection is not simply a refusal of price — it is an assertion that IDP’s standalone future is worth more than either proposal reflects. Central to this position is IDP’s ongoing multi-year transformation program, with the Board stating that the future earnings potential and associated benefits of this program are “yet to be realised.”
IDP Education FY26 results released on 20 August 2026 showed revenue of $795.4m and Adjusted EBIT of $122.9m, with the transformation program delivering a $32m net cost reduction that beat the original $25m target, providing the financial foundation the Board is now citing in defence of its standalone strategy.
The Board’s key reasons for rejecting the Indicative Proposal can be summarised as follows:
- The $2.50 price fails to reflect the fundamental value of IDP’s market-leading global platform
- The proposal does not account for the future earnings potential embedded in the transformation program
- The timing is considered highly opportunistic given current industry conditions and IDP’s position mid-transformation
- IDP’s share price traded above the offer price as recently as late June 2026, underscoring the inadequacy of the bid
In terms of financial capacity to pursue its standalone strategy, the Board highlighted IDP’s current position:
- Robust organic cash flow
- Existing cash reserves
- Strong balance sheet
The announcement does not explicitly invite further engagement with Blackstone or other parties. What is clear is that both proposals to date have been rejected on the basis of price, and the Board has expressed confidence in the execution of its transformation strategy to deliver profitable growth.
Don’t Miss the Next Consumer Sector Takeover Move
Breaking ASX news, including takeover bids, rejections, and market-moving announcements, lands in your inbox within minutes at Big News Blast. Join 20,000+ investors already receiving FREE real-time alerts paired with in-depth analysis the moment news breaks. Click the “Free Alerts” button to stay ahead before the market moves.