

IVE Group moves to acquire Motio in digital media push
IVE Group (ASX: IGL) and Motio Limited (ASX: MXO) have entered into a binding Scheme Implementation Deed (SID), under which IVE proposes to acquire 100% of Motio’s shares via a Scheme of Arrangement. The transaction is intended to extend IVE’s capabilities beyond marketing execution into the ownership and monetisation of digital place-based Out-of-Home (OOH) media.
Key offer metrics:
- Offer price of $0.060 cash per Motio share
- Premiums of 15.4% to last close, 15.6% to 5-day VWAP, 14.0% to 3-month VWAP, and 17.5% to 6-month VWAP (all to 18 September 2026)
- Fully diluted equity value of $20.7 million; enterprise value of $16.7 million
- Implied EV/FY26A cash EBITDA multiple of approximately 6.7x
- Funded from IVE’s existing debt facilities and cash reserves
- EPS and EPSA accretive on a pro forma basis from the first full year of ownership
The Motio Board unanimously recommends that Motio shareholders vote in favour of the Scheme, and each Motio Director intends to vote their controlled shares in favour of the Scheme, subject to no Superior Proposal arising and an independent expert opining that the Scheme is in the best interests of Motio shareholders.
When big ASX news breaks, our subscribers know first
What is Motio and why does it matter?
Motio is a digital place-based OOH media company operating over 1,300 digital screens across approximately 1,000 locations in Australia. Its screens are placed in environments characterised by high dwell time, including medical centres, cafés, licensed bars, indoor sports facilities, and taxi-tops across Sydney.
Digital place-based media pre-qualifies audiences based on where they are, using the environment itself to do the targeting. Screens are positioned in locations where people spend extended, uninterrupted time, which tends to support higher attention and recall for advertisers. Critically, Motio secures its inventory through multi-year site licences rather than competitively tendered concessions, providing supply security and reducing renewal risk.
Motio’s five networks at a glance
| Network | Locations/Panels | Key Metric | Audience Environment | Highlight Stat |
|---|---|---|---|---|
| Motio Health | 600+ locations | 3.2m visits/month | Medical centres and specialist rooms | 18m+ waiting room hours annually |
| Motio Café | 200+ locations | 1m+ visits/month | CBD hubs and high socio-economic suburban cafés | 2,400 weekly footfall per site |
| Motio Venue | 120+ locations | 2.3m visits/month | Licensed bars, pubs and clubs | 3,700 weekly footfall per site |
| Motio Play | 115+ locations | 500k visits/month | Indoor sports and leisure centres | 14–24 target age demographic |
| Motio Drive | 100+ panels | 15m+ monthly impressions | Taxi-top displays across Sydney | 36% monthly Sydney reach; sold exclusively by Motio under its partnership with Adonix |
Why digital OOH is growing
The Australian OOH sector has grown materially over the past five years, supported by increasing digital penetration and improved audience measurement. Key data points from the Outdoor Media Association:
- Australian OOH net media revenue grew from $669 million in 2020 to approximately $1.45 billion in 2025, representing 2.2x growth over the period
- Industry net media revenue grew +11.4% in 2025
- Digital inventory accounted for 77.1% of industry net revenue in 1H FY26
- First half 2026 net revenue reached approximately $744 million, up 6.5% on the prior corresponding period
- The retail, lifestyle and other (place-based) category generated approximately $314 million in 2025 and grew 7.4% in H1 2026 on the prior corresponding period
- MOVE 2.0 launched 9 March 2026, providing advertisers with a unified audience measurement standard across the channel
Motio’s financial profile — profitable and scaling
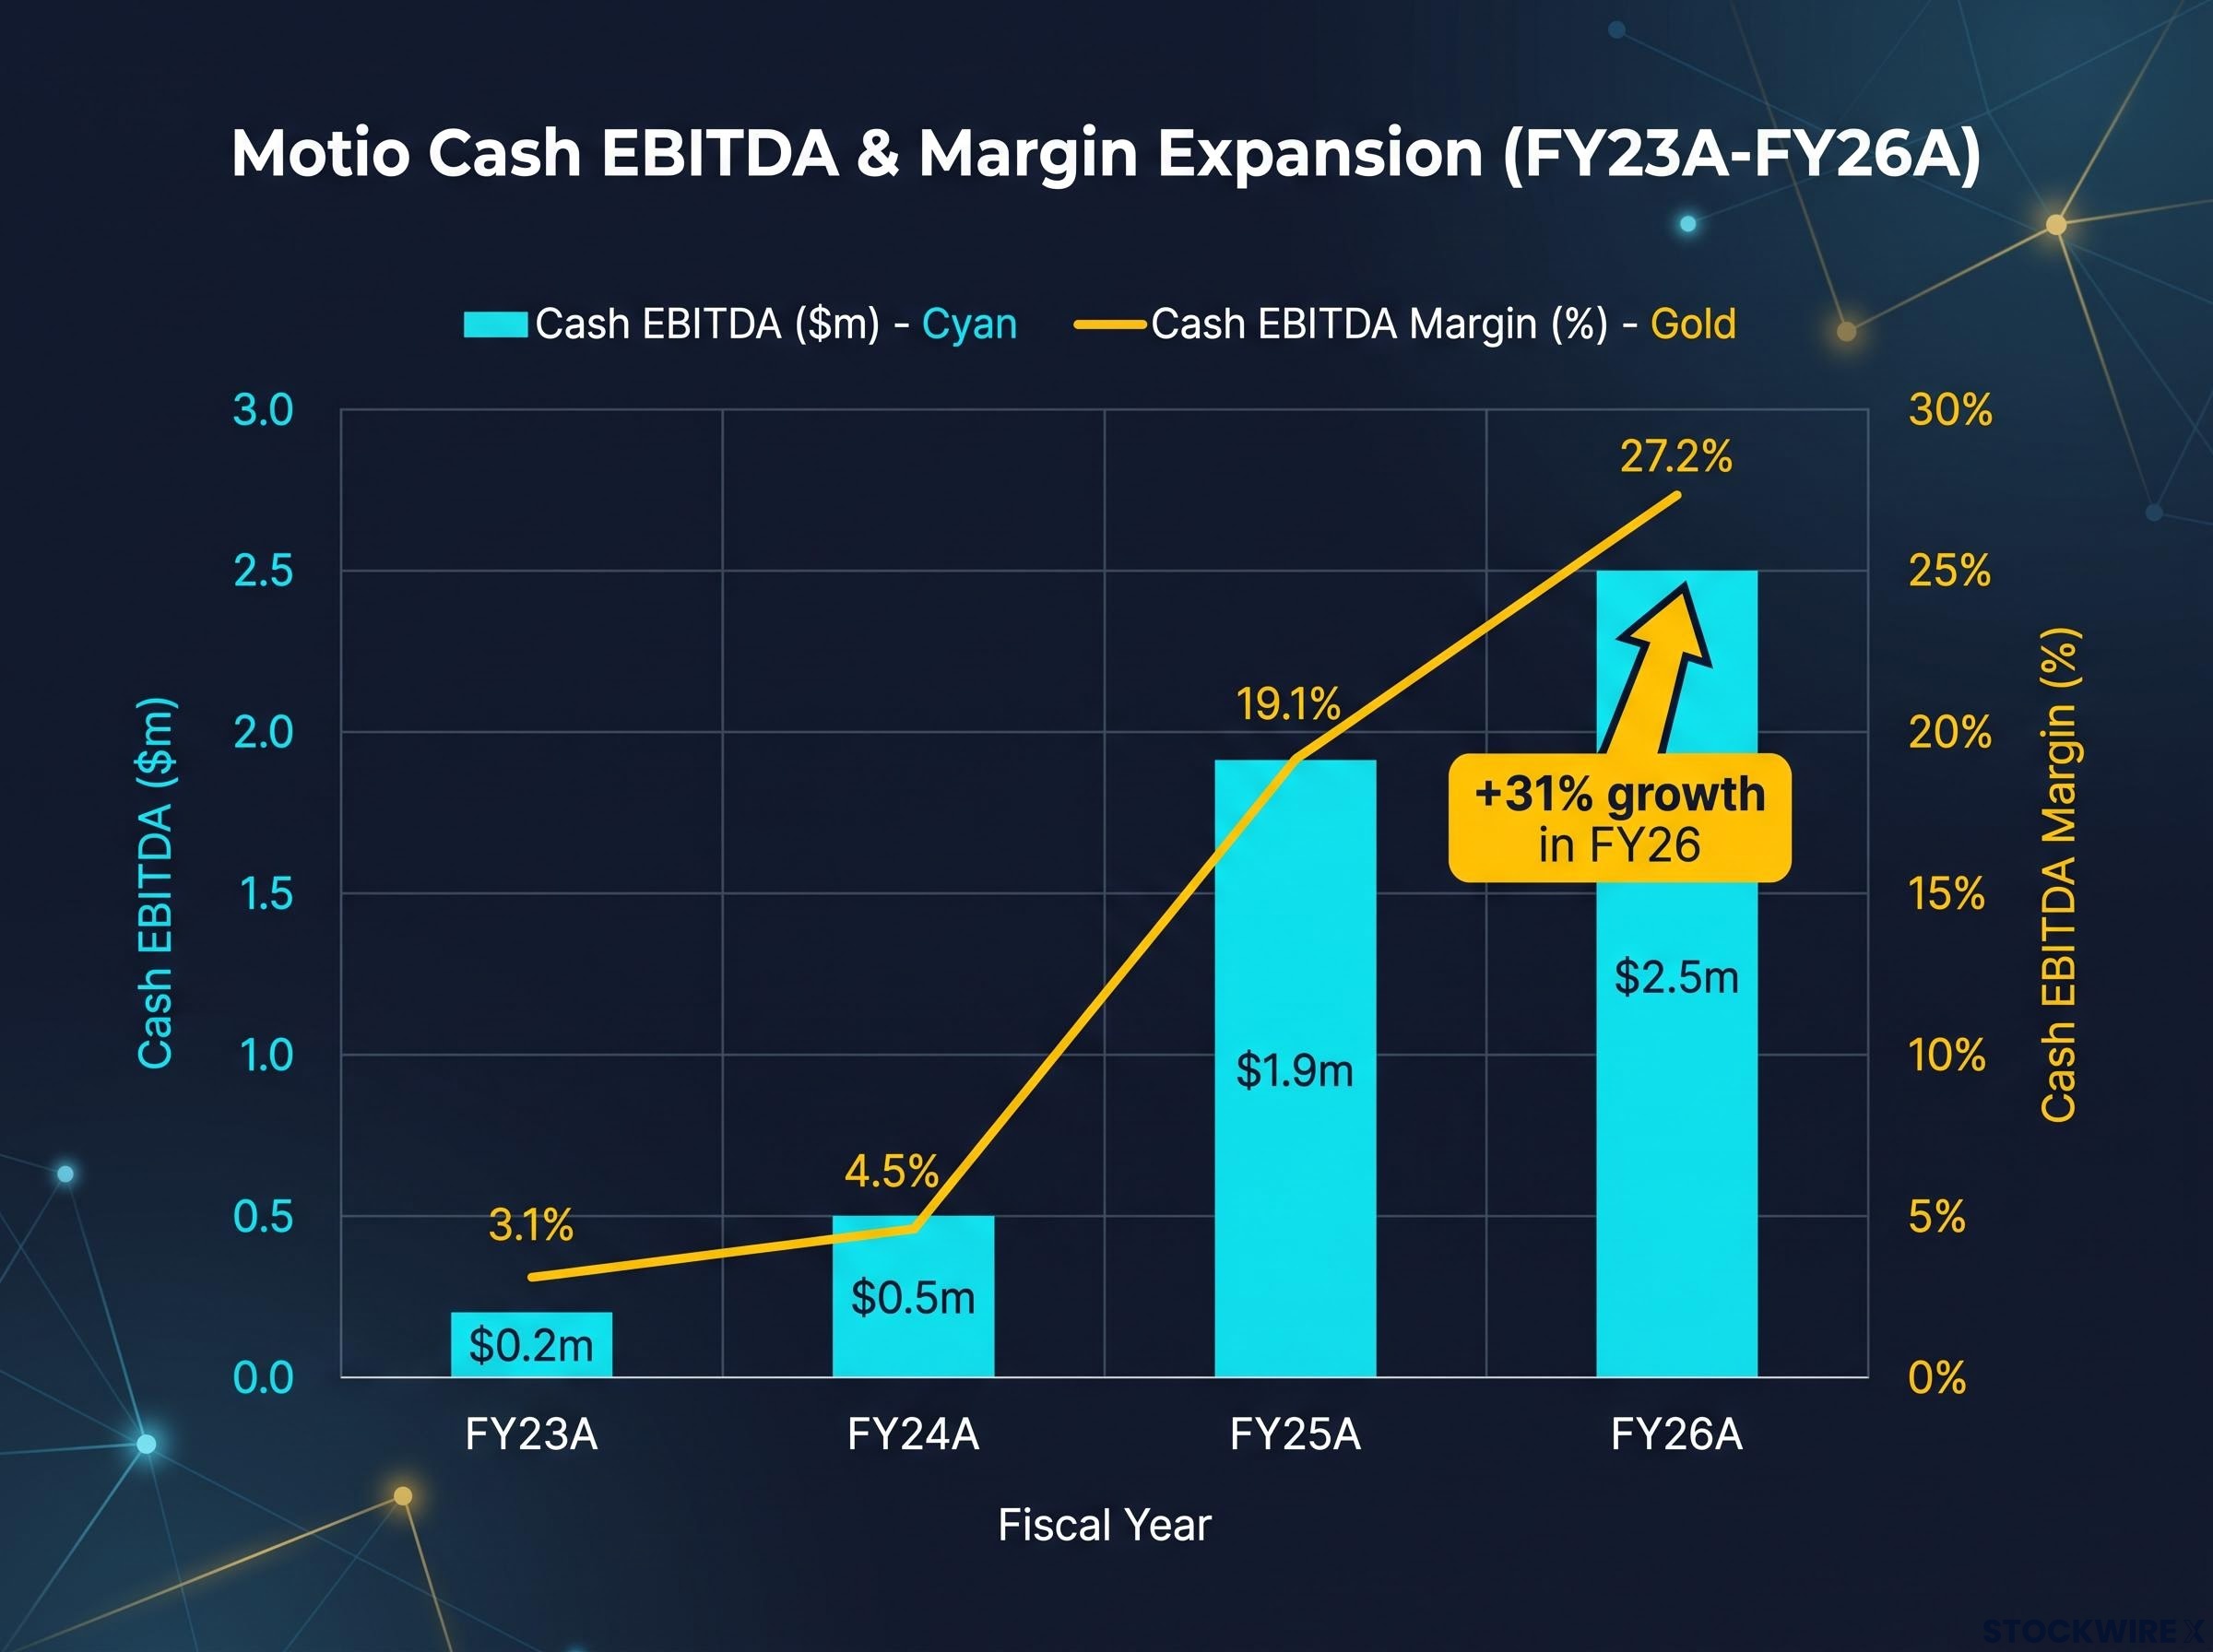
Motio has delivered consistent revenue growth alongside a marked expansion in cash EBITDA margins over the four years to FY26. The business is debt free, with approximately $3.94 million in net cash as at 30 June 2026.
| Period | Revenue (A$m) | Cash EBITDA (A$m) | Cash EBITDA Margin (%) |
|---|---|---|---|
| FY23A | $6.6m | $0.2m | 3.1% |
| FY24A | $7.2m | $0.5m | 4.5% |
| FY25A | $9.4m* | $1.9m | 19.1% |
| FY26A | $9.2m | $2.5m | 27.2% |
FY25A revenue includes the Motio Go Representation business (sales representation for a Petrol & Convenience network), which ceased at the end of FY25. FY26A revenue growth of +8% is calculated on a like-for-like basis, excluding this discontinued activity.
Cash EBITDA grew +31% in FY26, rising from $1.9 million to $2.5 million, as the network scaled and benefited from operating leverage on a largely fixed cost and infrastructure base. The margin trajectory, from 3.1% in FY23 to 27.2% in FY26, reflects the structural economics of place-based media: once a network is established, incremental inventory tends to convert to earnings at a high incremental margin.
Strategic fit and transaction terms
Extending IVE into media ownership
IVE outlines three strategic areas through which the combined entity is intended to create value, framed within its 2030 Strategy to position the group as a leading integrated marketing solutions provider:
- Scale: Deepen Motio’s existing platforms, extend into adjacent verticals, and draw on IVE’s client relationships, service breadth, and balance sheet to accelerate Motio’s expansion.
- Integrate: Bring screen procurement, content management, and delivery in-house within IVE’s Brand Activations business, replacing third-party supply that IVE currently sources externally.
- Build: Combine Motio and IVE capabilities to create a retail media proposition, monetise existing physical and digital touchpoints, and pursue potential follow-on M&A opportunities.
More broadly, the acquisition moves IVE from marketing execution into the ownership, delivery, and monetisation of media audiences and inventory, opening new markets and recurring revenue streams.
The presentation notes that value capture is intended to begin on day one post completion, with meaningful cost synergies identified and potential revenue synergies flagged as further upside over time.
Deal terms and timetable
The Scheme is subject to a number of customary conditions, including:
- Motio shareholder approval
- Court approval
- The Independent Expert concluding that the Scheme is in the best interests of Motio shareholders
- No Material Adverse Change and no prescribed occurrences
- No identified Key Employee resigning or giving notice of resignation before the Second Court Date
- Motio maintaining consolidated net cash and cash equivalents of at least $4.0 million on the day before the Second Court Date
- Completion of the agreed treatment of all equity incentives and other share rights
- Approval of the interrelated Option Scheme (concurrent and inter-conditional with the Scheme)
The indicative timetable for the Scheme of Arrangement is as follows:
| Event | Indicative Timing |
|---|---|
| Motio lodges Scheme Booklet with ASIC for review | Late October 2026 |
| First Court Date | Early November 2026 |
| Scheme Booklet dispatched to Motio shareholders and optionholders | Early November 2026 |
| Scheme meeting and Option Scheme meeting | Late November 2026 |
| Second Court Date | Late November 2026 |
| Effective date | Late November 2026 |
| Scheme record date | Early December 2026 |
| Implementation date | Early December 2026 |
The above timetable is indicative only and remains subject to change.
On a pro forma basis, the acquisition is expected to result in net debt to FY26 EBITDA (pre-AASB 16) of approximately 1.67x post-completion. This is calculated as IVE’s FY26 net debt of $173.2 million plus $19.2 million of transaction-related adjustments (totalling $192.4 million), divided by IVE’s FY26 pre-AASB 16 EBITDA of $112.6 million plus Motio’s FY26 cash EBITDA of $2.5 million (totalling $115.1 million). The transaction is funded from IVE’s existing debt facilities and cash reserves.
The IVE Group FY26 results provide the financial baseline behind the transaction: underlying EBITDA of $112.6 million and net debt of $173.2 million, both figures used directly in the pro forma leverage calculation of approximately 1.67x net debt to EBITDA post-completion.
Don’t Miss the Next Media Sector Deal on ASX
Big News Blast delivers FREE breaking ASX news straight to your inbox within minutes of release, complete with in-depth analysis already done. Join 20,000+ investors staying ahead of market-moving announcements across media, technology, and beyond. Click the “Free Alerts” button at Big News Blast to start receiving alerts the moment news breaks.