On 17 September 2025, the Federal Reserve cut interest rates by 25 basis points to a target range of 4.00-4.25%, the first reduction since December 2024. The language surrounding it was cautious enough that commentators quickly labelled it a “hawkish cut,” the kind of message that would usually pull stocks lower and lift the dollar.
Instead, equities stabilised, gold resumed a record-breaking climb, and Bitcoin barely twitched. The contradiction sat right there on the screen: a hawkish signal met with a shrug.
That gap between what the Fed said and how markets actually processed it is where a lot of reactive, emotion-driven trading goes wrong. Misreading central bank communications is one of the most consistent ways retail investors talk themselves into bad decisions, and the September meeting is a near-perfect example of why the headline label so often misleads.
Understanding how markets read the Fed changes how you handle every future announcement. What follows gives you a clear framework for reading Fed decisions the way the market does, not the way the headlines do, so you can assess the next FOMC meeting on your own terms.
The Fed cut rates, called it cautious, and markets mostly shrugged
Here is what actually happened. The Federal Open Market Committee (FOMC) lowered its benchmark rate by 25 basis points to 4.00-4.25%, effective 18 September 2025. The vote was not unanimous. Stephen I. Miran dissented, arguing for a larger 50 bp cut instead.
The “hawkish” label came not from the cut itself but from the accompanying dot plot, the chart of where each policymaker expects rates to go. The median path projected only two more cuts in 2025, taking the benchmark to roughly 3.50-3.75%, and just one further cut in 2026. That was far fewer than the most optimistic pre-meeting hopes.
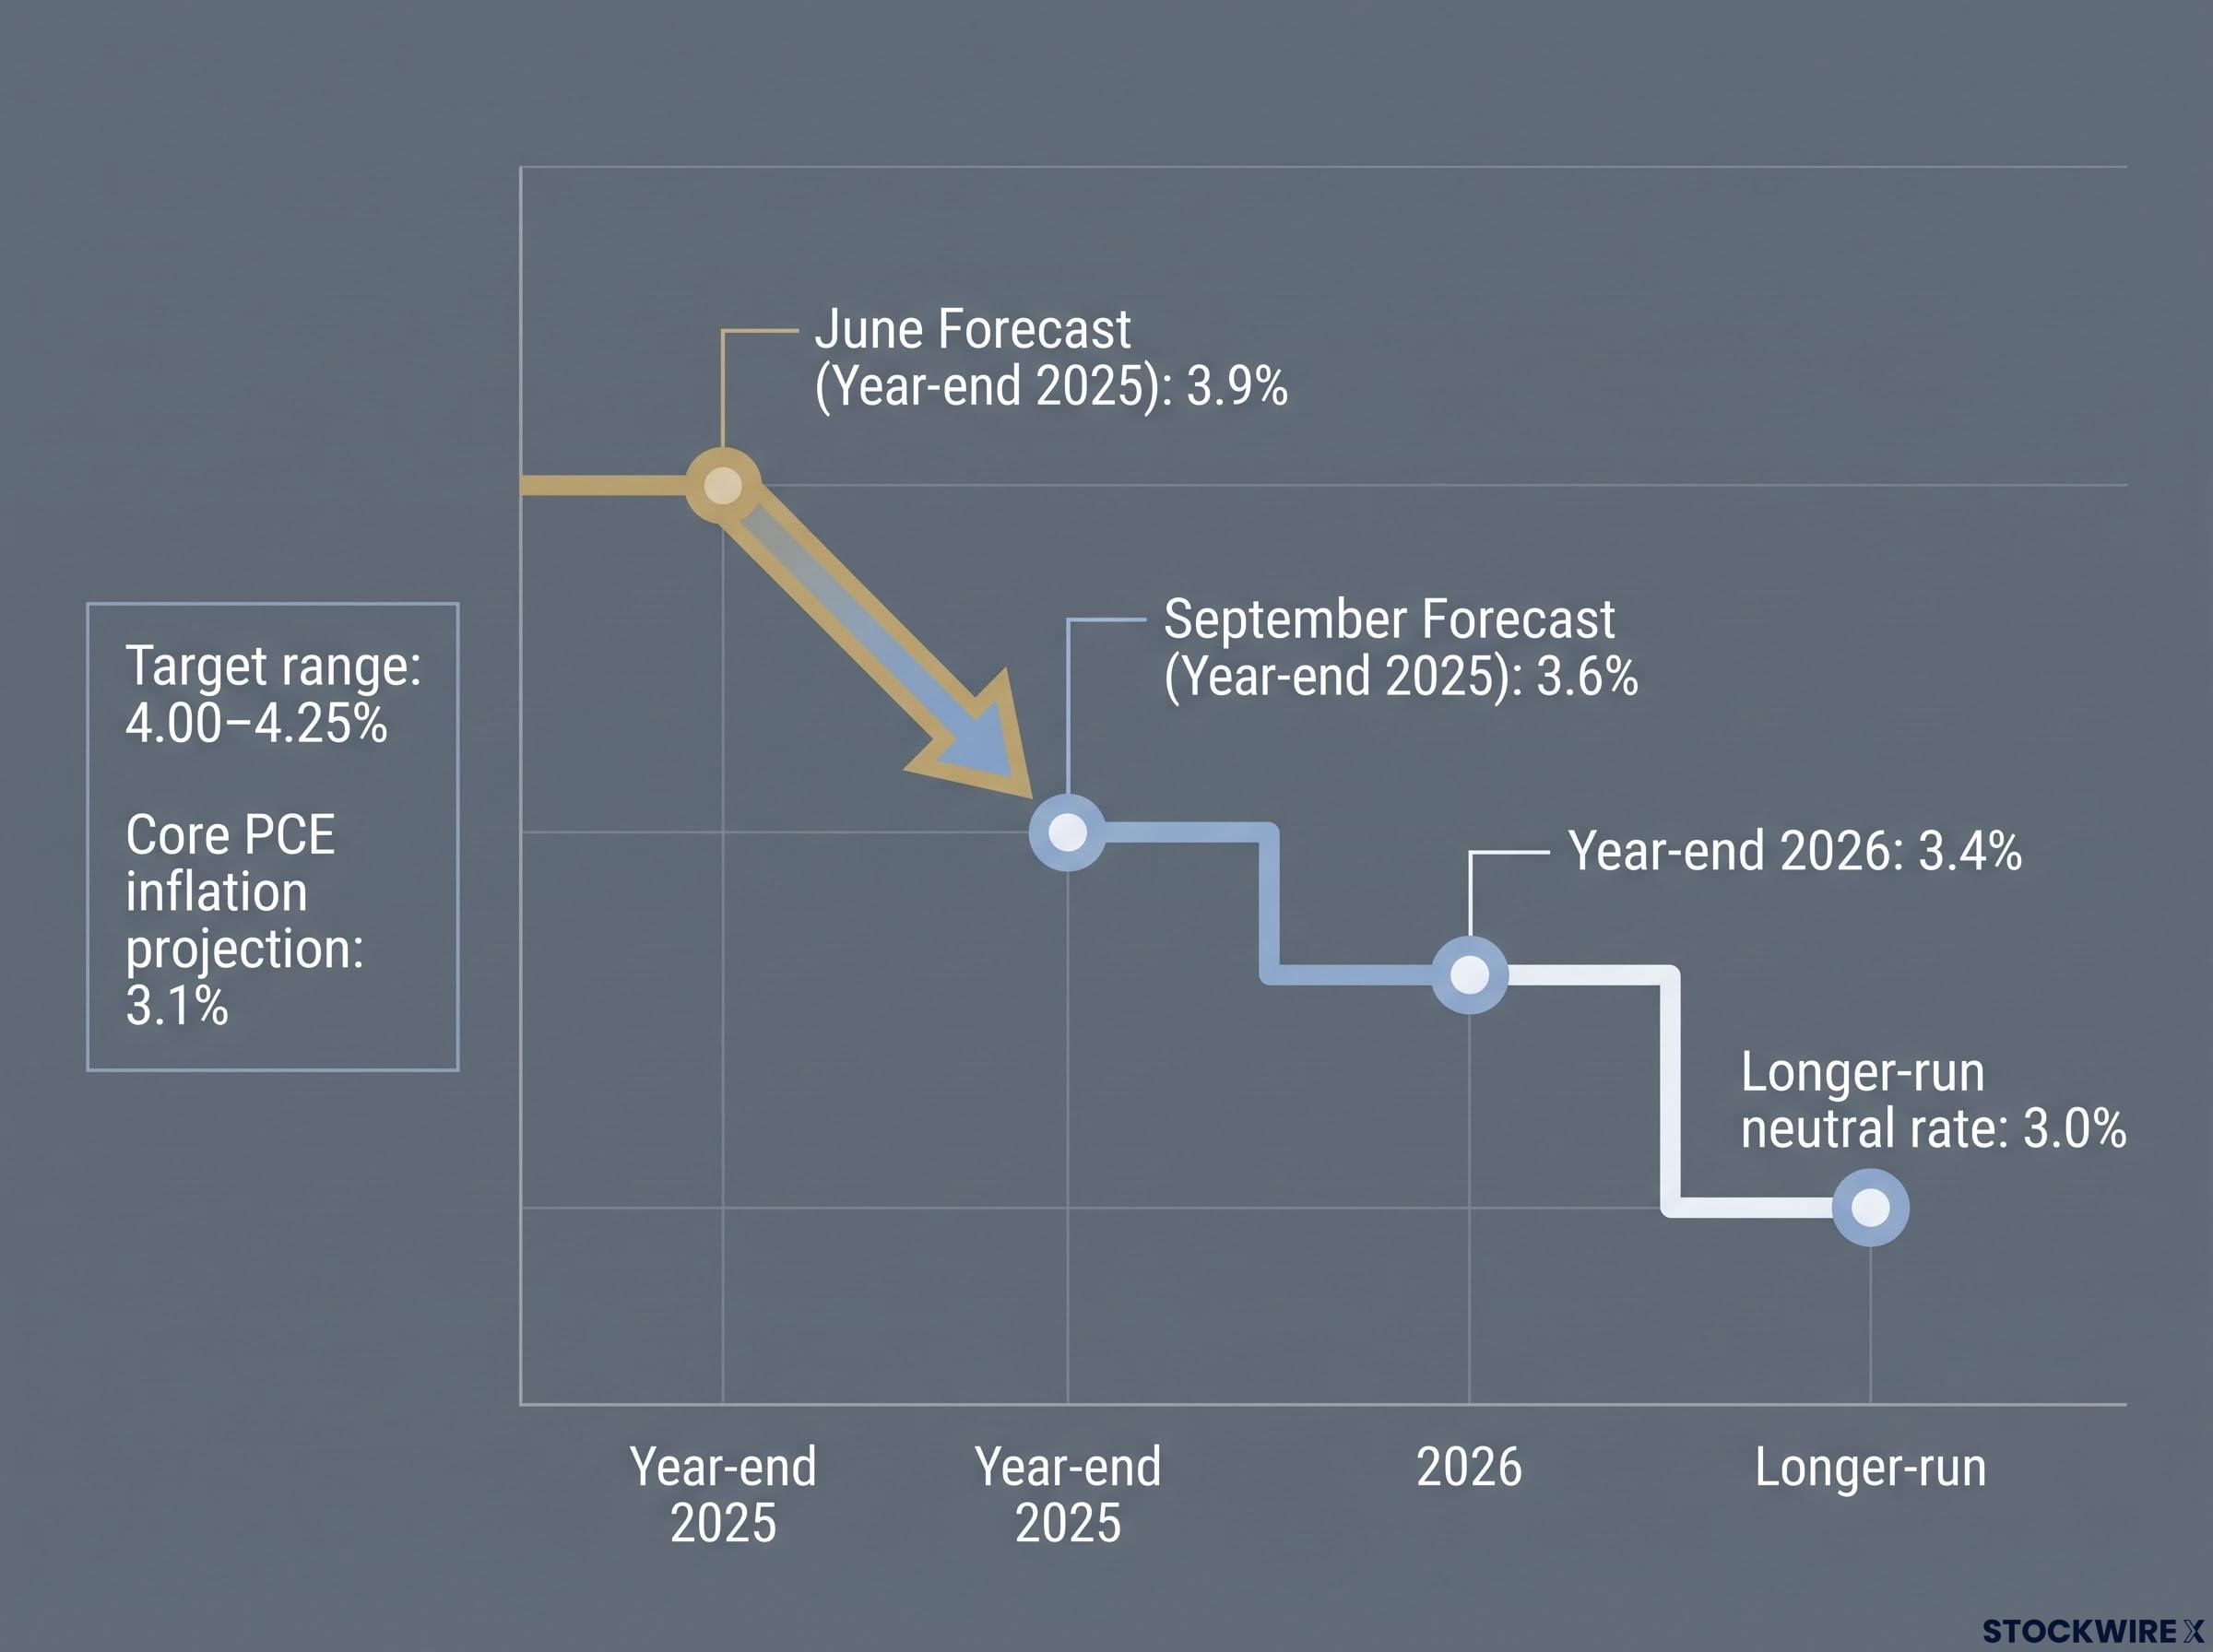
The projections also carried a downward revision. The median year-end 2025 rate dropped to 3.6%, from 3.9% in the June forecast, with the year-end 2026 median at 3.4% and the longer-run neutral rate at 3.0%. All of this sat against a core PCE inflation projection of 3.1% for the year, well above the Fed’s 2% target.
So how did markets close? Mixed, and quietly so.
| Asset | Move on 17 September | Level at close |
|---|---|---|
| Dow Jones Industrial Average | +0.57% | 46,018.32 |
| S&P 500 | -0.10% | ~6,600.35 |
| Nasdaq Composite | -0.32% | 22,261.33 |
| 10-year Treasury yield | +4.5 bps | 4.074% |
| 30-year Treasury yield | +2.5 bps | 4.672% |
None of that constitutes a selloff. And by the week of 22 September, equities had pushed to fresh highs.
Mark Malek, CIO at SiebertNXT (Reuters Instant View, 17 September 2025) The market’s reaction “has been to sell on this news, which isn’t that surprising; what does surprise is that the markets were as bullish going into this as they were.”
Here is the part worth sitting with. The absence of a selloff is more informative than any single index move. A supposedly hawkish decision produced no damage, which tells you the label and the reaction had come apart. Something was absorbing the news before it arrived.
When big ASX news breaks, our subscribers know first
What “priced in” actually means, and why it changes everything
You have heard the phrase a thousand times. A Fed decision was “priced in,” and it can sound like a hedge, a vague excuse traders reach for when the market does not do what the headline suggested it should. It is not vague at all.
Futures markets run a continuous auction on Fed outcomes. Traders assign probabilities to each possibility, a cut, a hold, a specific path of future moves, and those probabilities get baked into asset prices well before the meeting takes place. By the time the decision lands, the market has already bought and sold around the most likely result.
That is why an announcement matching expectations moves prices only at the margin. The information is old news the instant it becomes official.
The September numbers make this concrete.
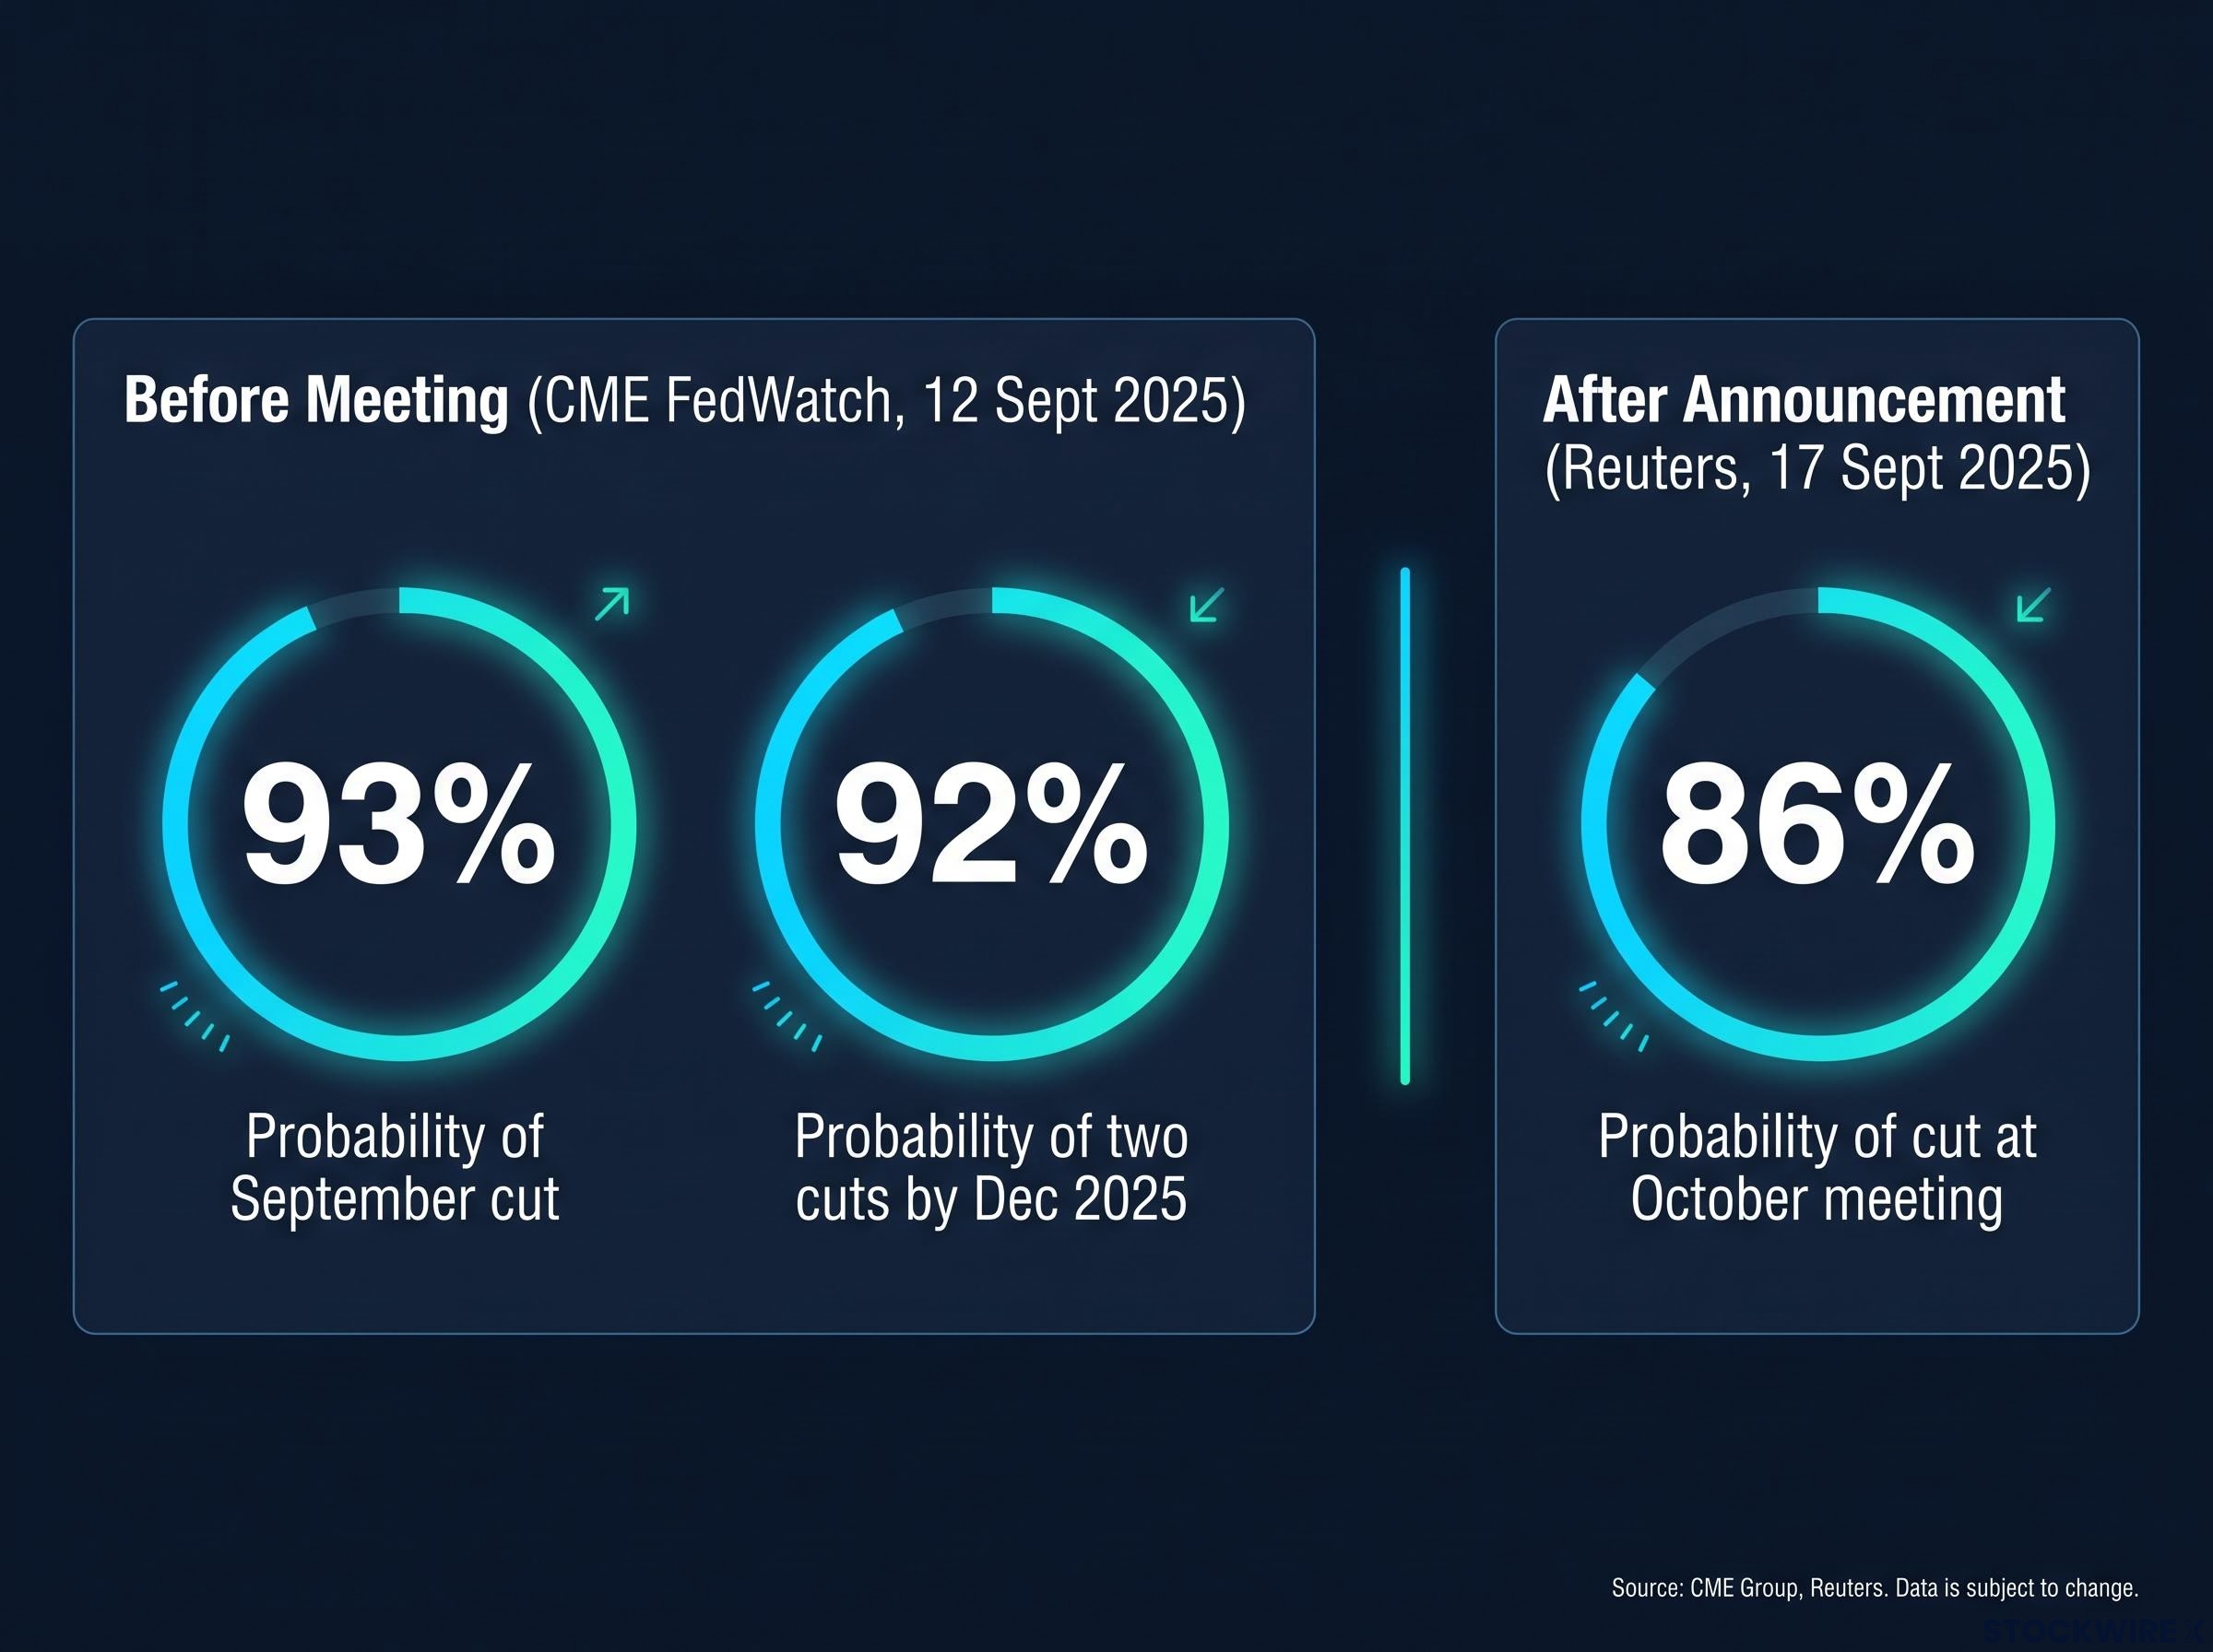
Before the meeting (CME FedWatch, around 12 September 2025):
- Roughly 93% probability of a September cut
- Roughly 92% probability of two cuts by December 2025
After the announcement:
- Around 86% probability of a further cut at the October meeting (Reuters, 17 September 2025)
With more than 90% of the September move already locked into prices, the actual decision simply confirmed what the market had positioned for. Even the cautious dot plot was, in one sense, still accommodative: the median path had been revised down from 3.9% in June to 3.6% in September, meaning the direction of travel remained toward easing.
The tail-risk removal effect
There is a subtler mechanism underneath the confirmation. When an expected event actually happens, it wipes out the probability the market had assigned to worse outcomes, a surprise hold, or language far more hawkish than anticipated.
Because the price had carried some weight for those bad scenarios, removing them acts as a mild positive on its own. The market breathes out. That quiet exhale, not any single line in the statement, is a large part of why risk assets stabilised.
For you, the practical takeaway reframes the whole exercise. Tracking whether the Fed “cut” or “held” is often the least useful thing you can do. What matters is whether the outcome landed inside or outside the probability distribution the market had already built, because only the surprise portion is genuinely new information.
Gold above $3,700 and Bitcoin near $117,000: what each asset’s reaction reveals
Stocks and bonds tell you how the priced-in mechanism worked. Gold and Bitcoin tell you something else entirely, because they behaved less like risk gauges and more like independent verdicts on whether the market actually believed the Fed’s inflation story. And the two verdicts did not fully match.
Gold’s resilience as an inflation-credibility signal
Gold had already run to record territory above $3,700/oz heading into the meeting, driven by rate-cut expectations and safe-haven demand.
- After the announcement, spot gold slipped just 0.4% to $3,643.40/oz on profit-taking
- By late September, it was holding above $3,750/oz
- The World Gold Council described the pause as a “healthy unwind” within an ongoing uptrend, with analyst targets pointing toward $4,000/oz
The important detail is what did not happen. A hawkish message did not knock gold off its trend. That resilience rests on structural forces beyond the rate decision: sustained central bank buying, persistent inflation with the core PCE projection at 3.1%, and broad dollar weakness.
When gold stays bid through a hawkish announcement, it is telling you how little confidence the market actually has in the Fed’s disinflation narrative. If you hold anything sensitive to real interest rates, that signal is worth more than the Fed’s own reassurances.
Bitcoin’s muted response and what it was actually waiting for
Bitcoin barely registered the meeting.
- Trading around $115,000-$116,000 at the announcement
- A brief dip, then a recovery to roughly $117,000-$118,000 within hours
- Three-month volatility compressed to about 26% (CoinShares, 19 September 2025), which described the reaction as “cautious”
Two things explain the indifference. First, a 25 bp cut with 90%-plus odds attached carried no surprise to react to. Second, Bitcoin’s earlier weakness stemmed largely from the failure of the Clarity Act in Congress rather than Fed policy, meaning it had already digested its negative catalyst before Powell spoke.
There is a deeper reason too. Crypto markets tend to move on macro regime shifts, sustained declines in real rates or large-scale liquidity expansion, not incremental easing. This meeting delivered neither, so Bitcoin waited.
Read together, the two assets sketch a layer of skepticism beneath the surface calm. Gold stayed strong on inflation fears the Fed had not put to rest. Bitcoin sat on its hands, waiting for evidence of a genuine liquidity regime change that a single cautious cut did not provide.
Two camps, one meeting: why analysts still disagreed after the dust settled
If the mechanism is this clear, why did credible institutions land on opposite readings of the same meeting? Because the September decision contained genuine ambiguity, and your interpretation depends entirely on which part of the communication you weight most heavily.
Hawkish reading:
- Standard Chartered framed it as a risk-management cut, aimed at managing employment risks while leaving scope for slower or fewer future cuts than optimistic equity pricing implied
- SiebertNXT’s Mark Malek took the sell-the-news view, arguing the pre-meeting rally had overpriced how dovish the Fed would be
- Ridge Capital Solutions stressed that the dot plot projected only two additional cuts for 2025, not the rapid descent markets had anticipated, and read the divided committee as a sign of unresolved internal debate
Dovish-within-hawkish reading:
- IG’s Weekly Market Navigator (22 September 2025) argued the key signal was the cautious-but-not-aggressive posture, which confirmed gradual easing without triggering recession fears
- Yahoo Finance analysis emphasised the downward revision from June’s 3.9% to September’s 3.6% as meaningfully more accommodative
- The widely circulated “Dovish Message Within a Hawkish Rate Cut” reading highlighted the committee’s underlying easing bias
IG Weekly Market Navigator, 22 September 2025 The most important driver was not the cut itself but confirmation that the Fed remained cautious rather than aggressively dovish, reassuring investors that easing would be gradual and data-dependent.
Neither camp was confused. They simply weighted different dimensions of a multi-dimensional signal.
For you, the fact that serious analysts disagreed for defensible reasons is the point. Chasing the “hawkish” or “dovish” headline is an unreliable guide, because the durable skill is understanding what was already priced in and identifying which dimension of the communication actually represents new information.
Reading the next Fed announcement without getting caught in the headline
Here is the mechanism in two sentences. The gap between what the Fed says and how markets respond is set by prior pricing, not by the announcement itself. A hawkish message into a fully-priced market is functionally neutral, and a dovish message into an overpriced market can still produce a selloff.
So before the next FOMC meeting, ask three questions rather than waiting for the headline:
- What probability is the futures market currently assigning to each outcome? That tells you what is already in the price.
- How does the new dot plot compare to the prior Summary of Economic Projections? The revision, not the absolute level, is where the new information sits.
- What are gold and the bond market saying about inflation credibility, independently of the Fed’s own narrative?
The September 2025 meeting is a clean case study in why these questions beat the label. A hawkish cut produced a rebound precisely because the outcome landed inside the distribution the market had already built.
With the median path still pointing lower, 3.4% by the end of 2026 and a 3.0% longer-run neutral rate, the easing cycle is not finished. Future meetings will turn on the pace of cuts, not their direction, giving you plenty of chances to apply the same reasoning.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. Past performance does not guarantee future results, and financial projections are subject to market conditions and various risk factors.