The ASX 200 has now risen three sessions in a row, to about 8,735 points, yet it still sits below where it stood before last Thursday’s drop of roughly 2%. On the same day the index rose, technology fell almost 3%.
Tuesday 6 October showed how much a headline number can hide. Nine of eleven sectors rose, while technology sold off hard.
This ASX market wrap looks at where the money moved, which stocks drove it, and how much weight a three-day bounce deserves. You will also see how routine dividend adjustments can look like losses when they are not.
Where did the money go? Technology sold off while real estate, miners and banks absorbed it
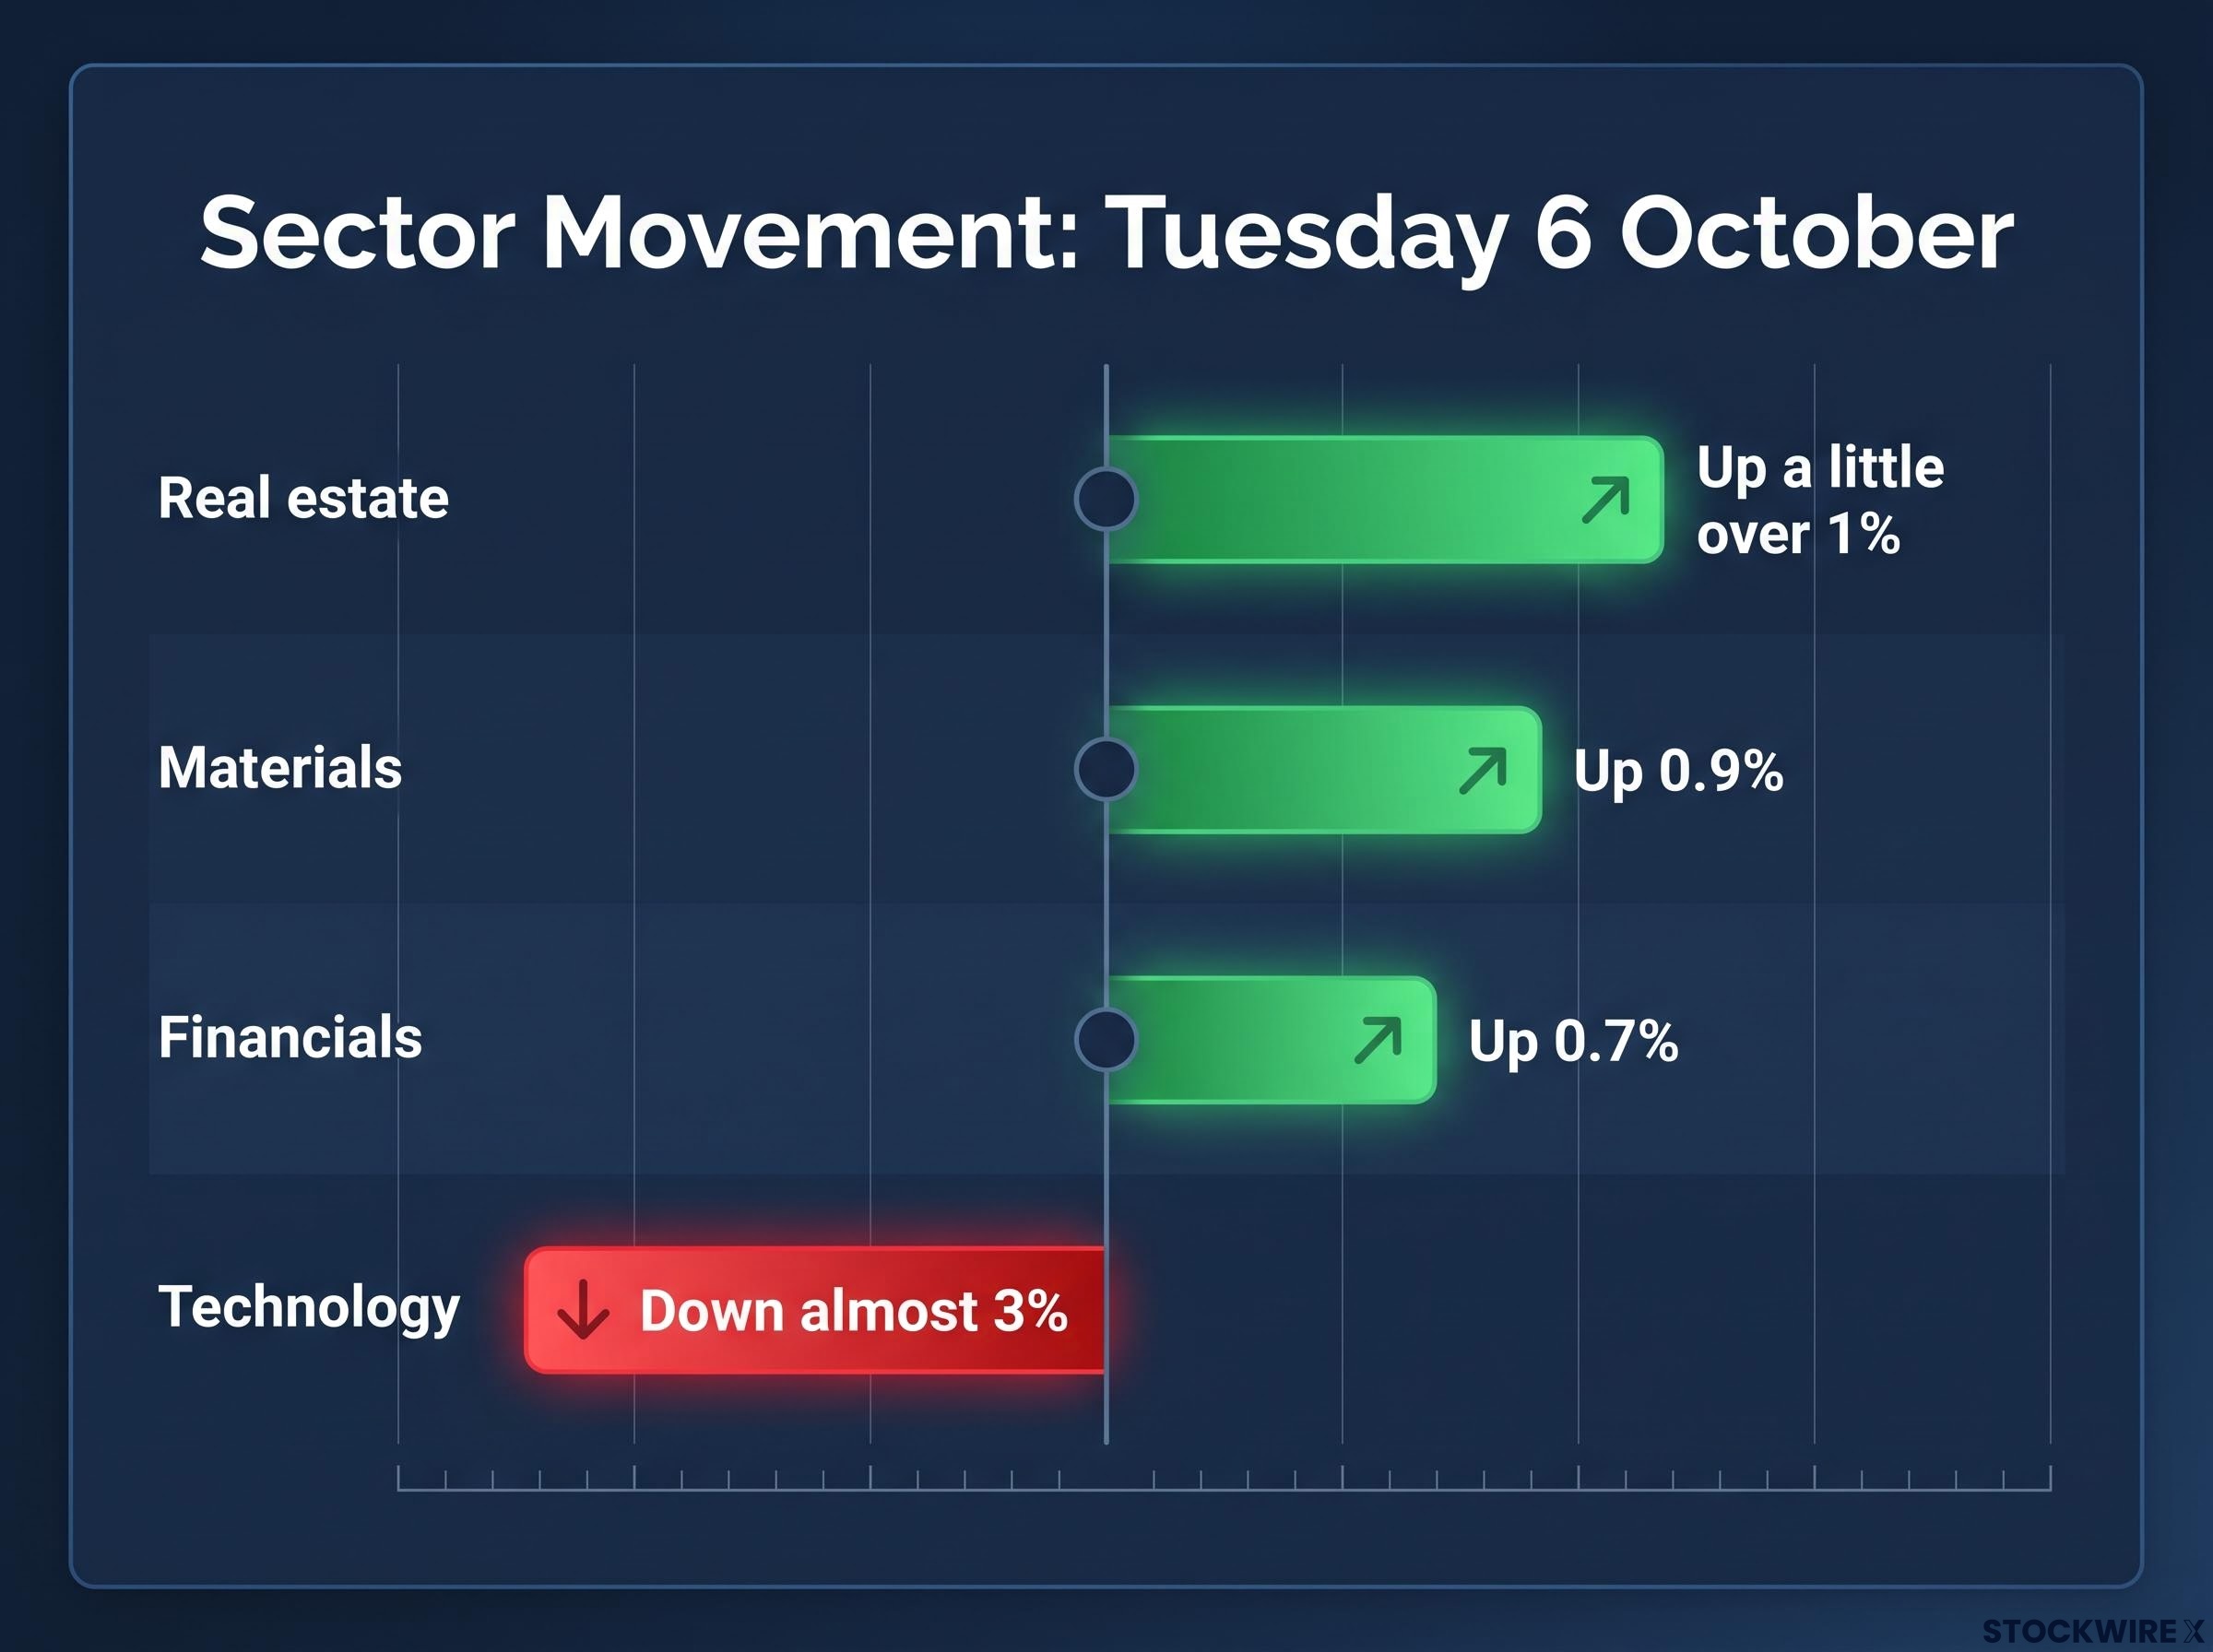
The split was stark. Technology fell almost 3% while real estate rose a little over 1%, and the index still closed up more than 0.5%.
The sector scorecard
| Sector | Move | Session driver |
|---|---|---|
| Technology | Down almost 3% | Codan and Weebit Nano retreated from recent rallies |
| Real estate | Up a little over 1% | Rebound after several weak sessions |
| Materials | Up 0.9% | BHP supported the market; Alcoa gained |
| Financials | Up 0.7% | Large banks supported the index |
| Utilities | Similar to materials | No specific driver identified |
Nine of eleven sectors rose, so the breadth was real. The index gain, though, tells you little about your own portfolio: a holder of small-cap tech had a very different day from a holder of banks and miners. Check which side your exposure sits on.
One caution. No named analyst was found confirming a deliberate rotation, so “rotation” here describes what the numbers show, not a confirmed investor strategy.
The stocks behind the numbers
The tech losers came first, and both had run hard recently:
- Weebit Nano fell almost 13%. The memory chip maker had been among Monday’s best performers after a Friday rise in the US semiconductor index.
- Elsight, a drone connectivity company, was the second-worst performer. It is still up more than 50% year to date after surging over 700% in 2025.
That Weebit pattern, a rise following the US chip index and then a sharp reversal, fits mechanisms commonly cited for speculative tech: momentum and retail flows, sensitivity to US sector leaders, and discount rates on growth stocks. No analyst linked these to either stock specifically. Still, a huge prior run makes pullbacks look larger, because there is more gain to give back.
On the other side, Alcoa rose a little over 4% on firmer aluminium prices, and Metcash, owner of IGA, gained without any announcement.
When big ASX news breaks, our subscribers know first
Arena REIT bounced hard, but is the recovery on solid ground?
Arena REIT was the session’s top performer, recovering from a more-than-six-year low. The sell-off followed a major childcare tenant ceasing to pay rent.
How the default unfolded
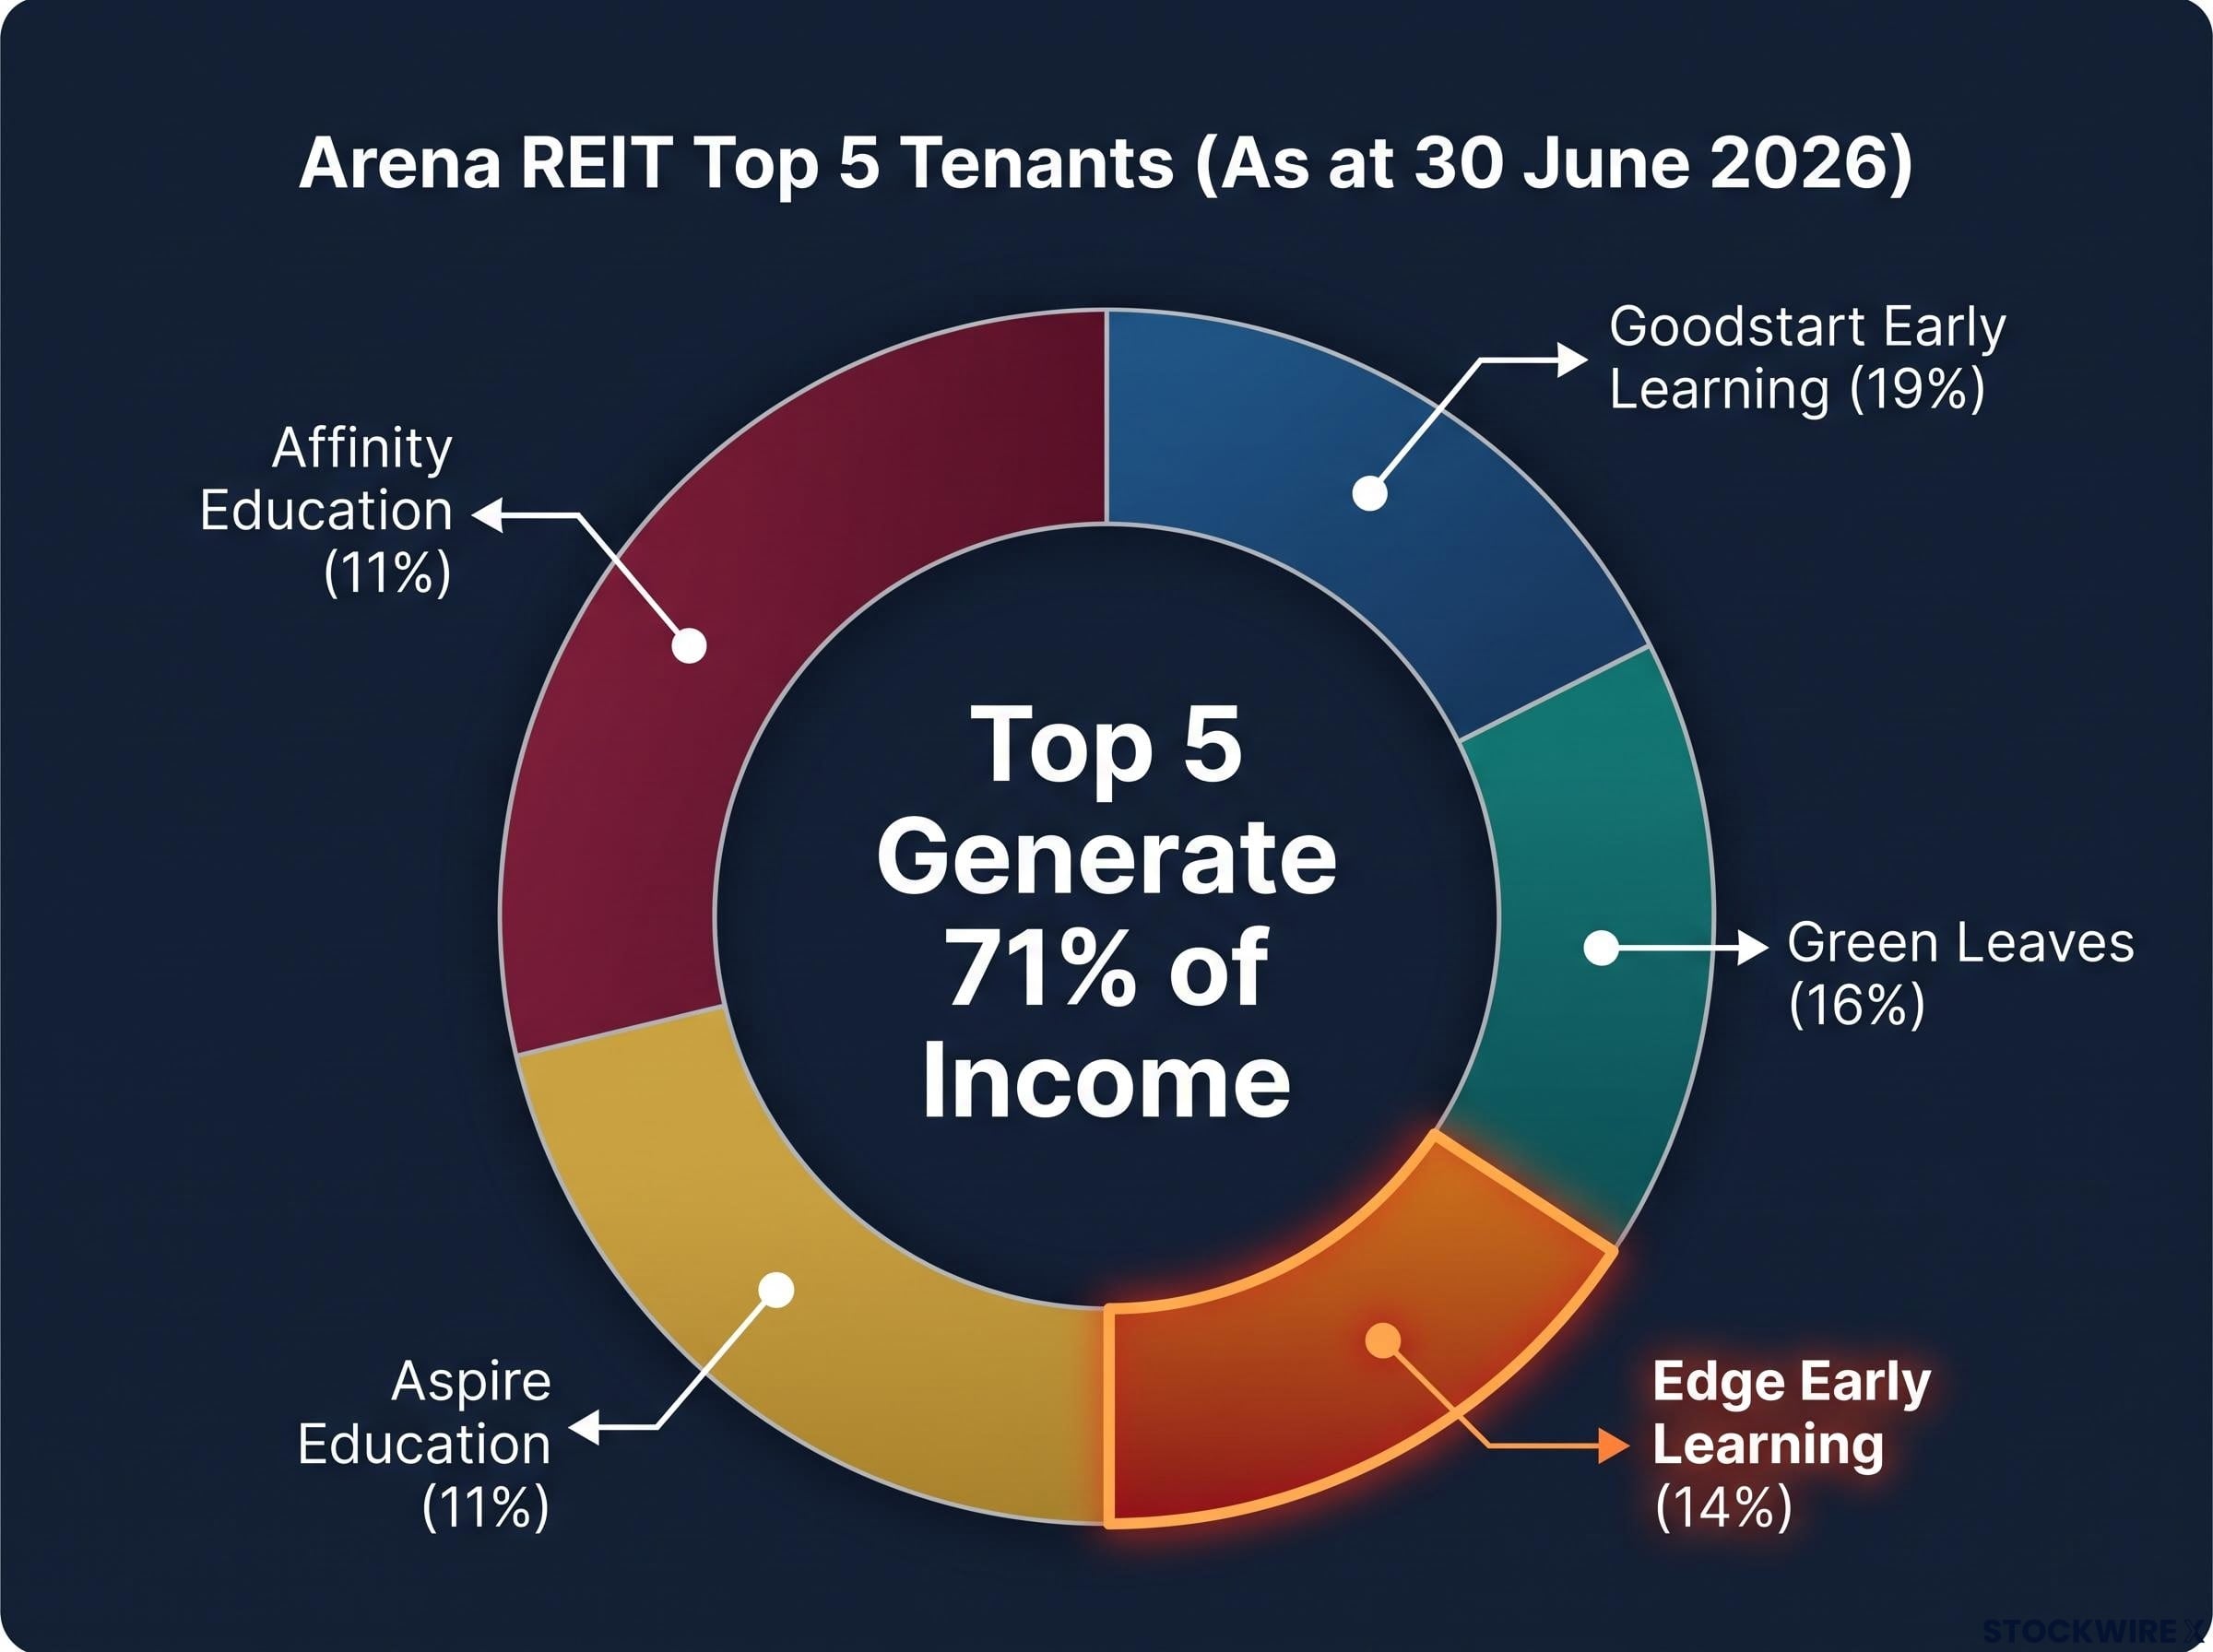
The tenant is Edge Early Learning, which leases 31 Arena properties in Queensland and South Australia. Those leases represent about 14% of annual rental income, making Edge the third-largest tenant as at 30 June 2026.
- Rent was paid in full to 31 July.
- In late July, Edge asked for a deferral or abatement as part of a restructure. Arena refused.
- August rent, due 3 August, went unpaid.
- Default notices followed on 4 August, with a 21-day remedy period.
- Edge later entered voluntary administration.
Shares fell around 20% intraday on disclosure, according to the Australian Financial Review and MarketScreener. Morningstar reports Arena guided FY2027 distributions down 7% to $0.18 per security.
| Tenant | Share of income |
|---|---|
| Goodstart Early Learning | 19% |
| Green Leaves | 16% |
| Edge Early Learning | 14% |
| Aspire Education | 11% |
| Affinity Education | 11% |
The top five tenants generate 71% of income, which is the concentration problem in one number.
Two readings of the rebound
The bull case is Morningstar’s view:
Morningstar argues the default is a material negative, but the sell-off looks overdone given Arena’s diversified tenants, long leases and stable occupancy.
Morningstar and other commentary also cite a net rent-to-gross revenue ratio of about 10%, occupancy in the mid-70% range, and roughly $4 million in liquid security held against Edge’s obligations.
The bear case is concentration and tenant quality. Simply Wall St says Edge’s failure across 31 properties raises doubts about the reliability of childcare income, and commentary points to rising staffing and compliance costs for operators.
A one-day bounce after a fall of about 20% tells you the market thinks the damage may be contained, not that it is. The answer depends on who runs the centres, whether rents are reset, and whether distributions hold after the guided cut. Further bad news on Edge or other tenants could reverse the move.
What an ex-dividend fall really tells you, and who gets paid on Wednesday
Two familiar names fell on a day the market rose. Harvey Norman dropped 1.7% and Reece slipped about 0.25%. Neither move was a verdict on the business.
Why the price drops on the ex-date
The ex-date is the first day a stock trades without its declared dividend attached. Anyone buying on or after it does not receive that payout, so the price typically adjusts by roughly the dividend amount.
- Ex-date: buyers from this day miss the dividend.
- Payment date: cash reaches eligible shareholders’ accounts.
Harvey Norman’s dividend is 13 cents per share, payable on 12 November. No dividend details for Reece were found.
The actual fall can differ from the dividend because of sentiment, company news and demand for franked income. An ex-dividend drop is not a loss of value in itself, so compare total return (price plus dividend) before treating a decline as bad news.
Wednesday’s payments
Payments land on Wednesday 7 October, after billions were distributed in recent weeks. Companies paying include:
- Wesfarmers
- Cash Converters
- Neuren Pharmaceuticals
- Perseus
- Regis Resources
If you hold any of these, that is cash arriving, not a price event. No “dividend season” effect on the ASX was found in the research. The Australian dollar was little changed at 69.6 US cents.
Three sessions up, one big drop behind: how much should a short bounce count?
The three gains were about 0.8% on Friday, minimal on Monday, and more than 0.5% on Tuesday. Thursday’s fall was roughly 2%, so the index has not fully recovered.
The index is still below its pre-drop level despite three straight gains.
The gains are not equal in conviction. Monday’s was thin because several states had a long weekend.
No historical precedents for rebounds after roughly 2% falls were found, which limits any claim about what comes next. The sensible reading is a partial repair, backed by banks, miners and a rebounding real estate sector, not confirmation that the sell-off is over.
Signals that could reverse it:
- Further news on Edge Early Learning
- Renewed speculative selling in technology
- Loss of commodity support for miners
- Failure of real estate to hold its gains
What this ASX market wrap does and does not settle
The session showed a market held up by banks, miners and real estate while speculative tech gave back gains. Arena’s bounce and routine ex-dividend adjustments were the notable stock-level stories.
Still unsettled are the Edge resolution, whether technology stabilises, and whether the index regains last Thursday’s level. Check where your holdings sit against the sector split, and note which dividends land on Wednesday.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions. These statements are speculative and subject to change based on market developments and company performance.