The S&P 500 slipped just 0.06% on Monday, but the Philadelphia Semiconductor Index fell 2.7% in the same session. A day later, South Korea’s KOSPI dropped 5.46%, led by a double-digit fall in SK hynix. The AI stocks rotation that the flat US close concealed has now produced its first serious casualty abroad.
The calm headline hid real movement. Investors sold AI and chip names that had led the market all year and moved that money into European equities and defensive sectors.
That matters if you hold a technology-heavy index fund. A flat number on your screen can sit on top of very large shifts inside your portfolio.
This piece sets out what the breadth data says about whether this is a healthy reshuffle or the start of something larger, and where the real vulnerability sits.
Why did the KOSPI fall more than 5% when Wall Street barely moved?
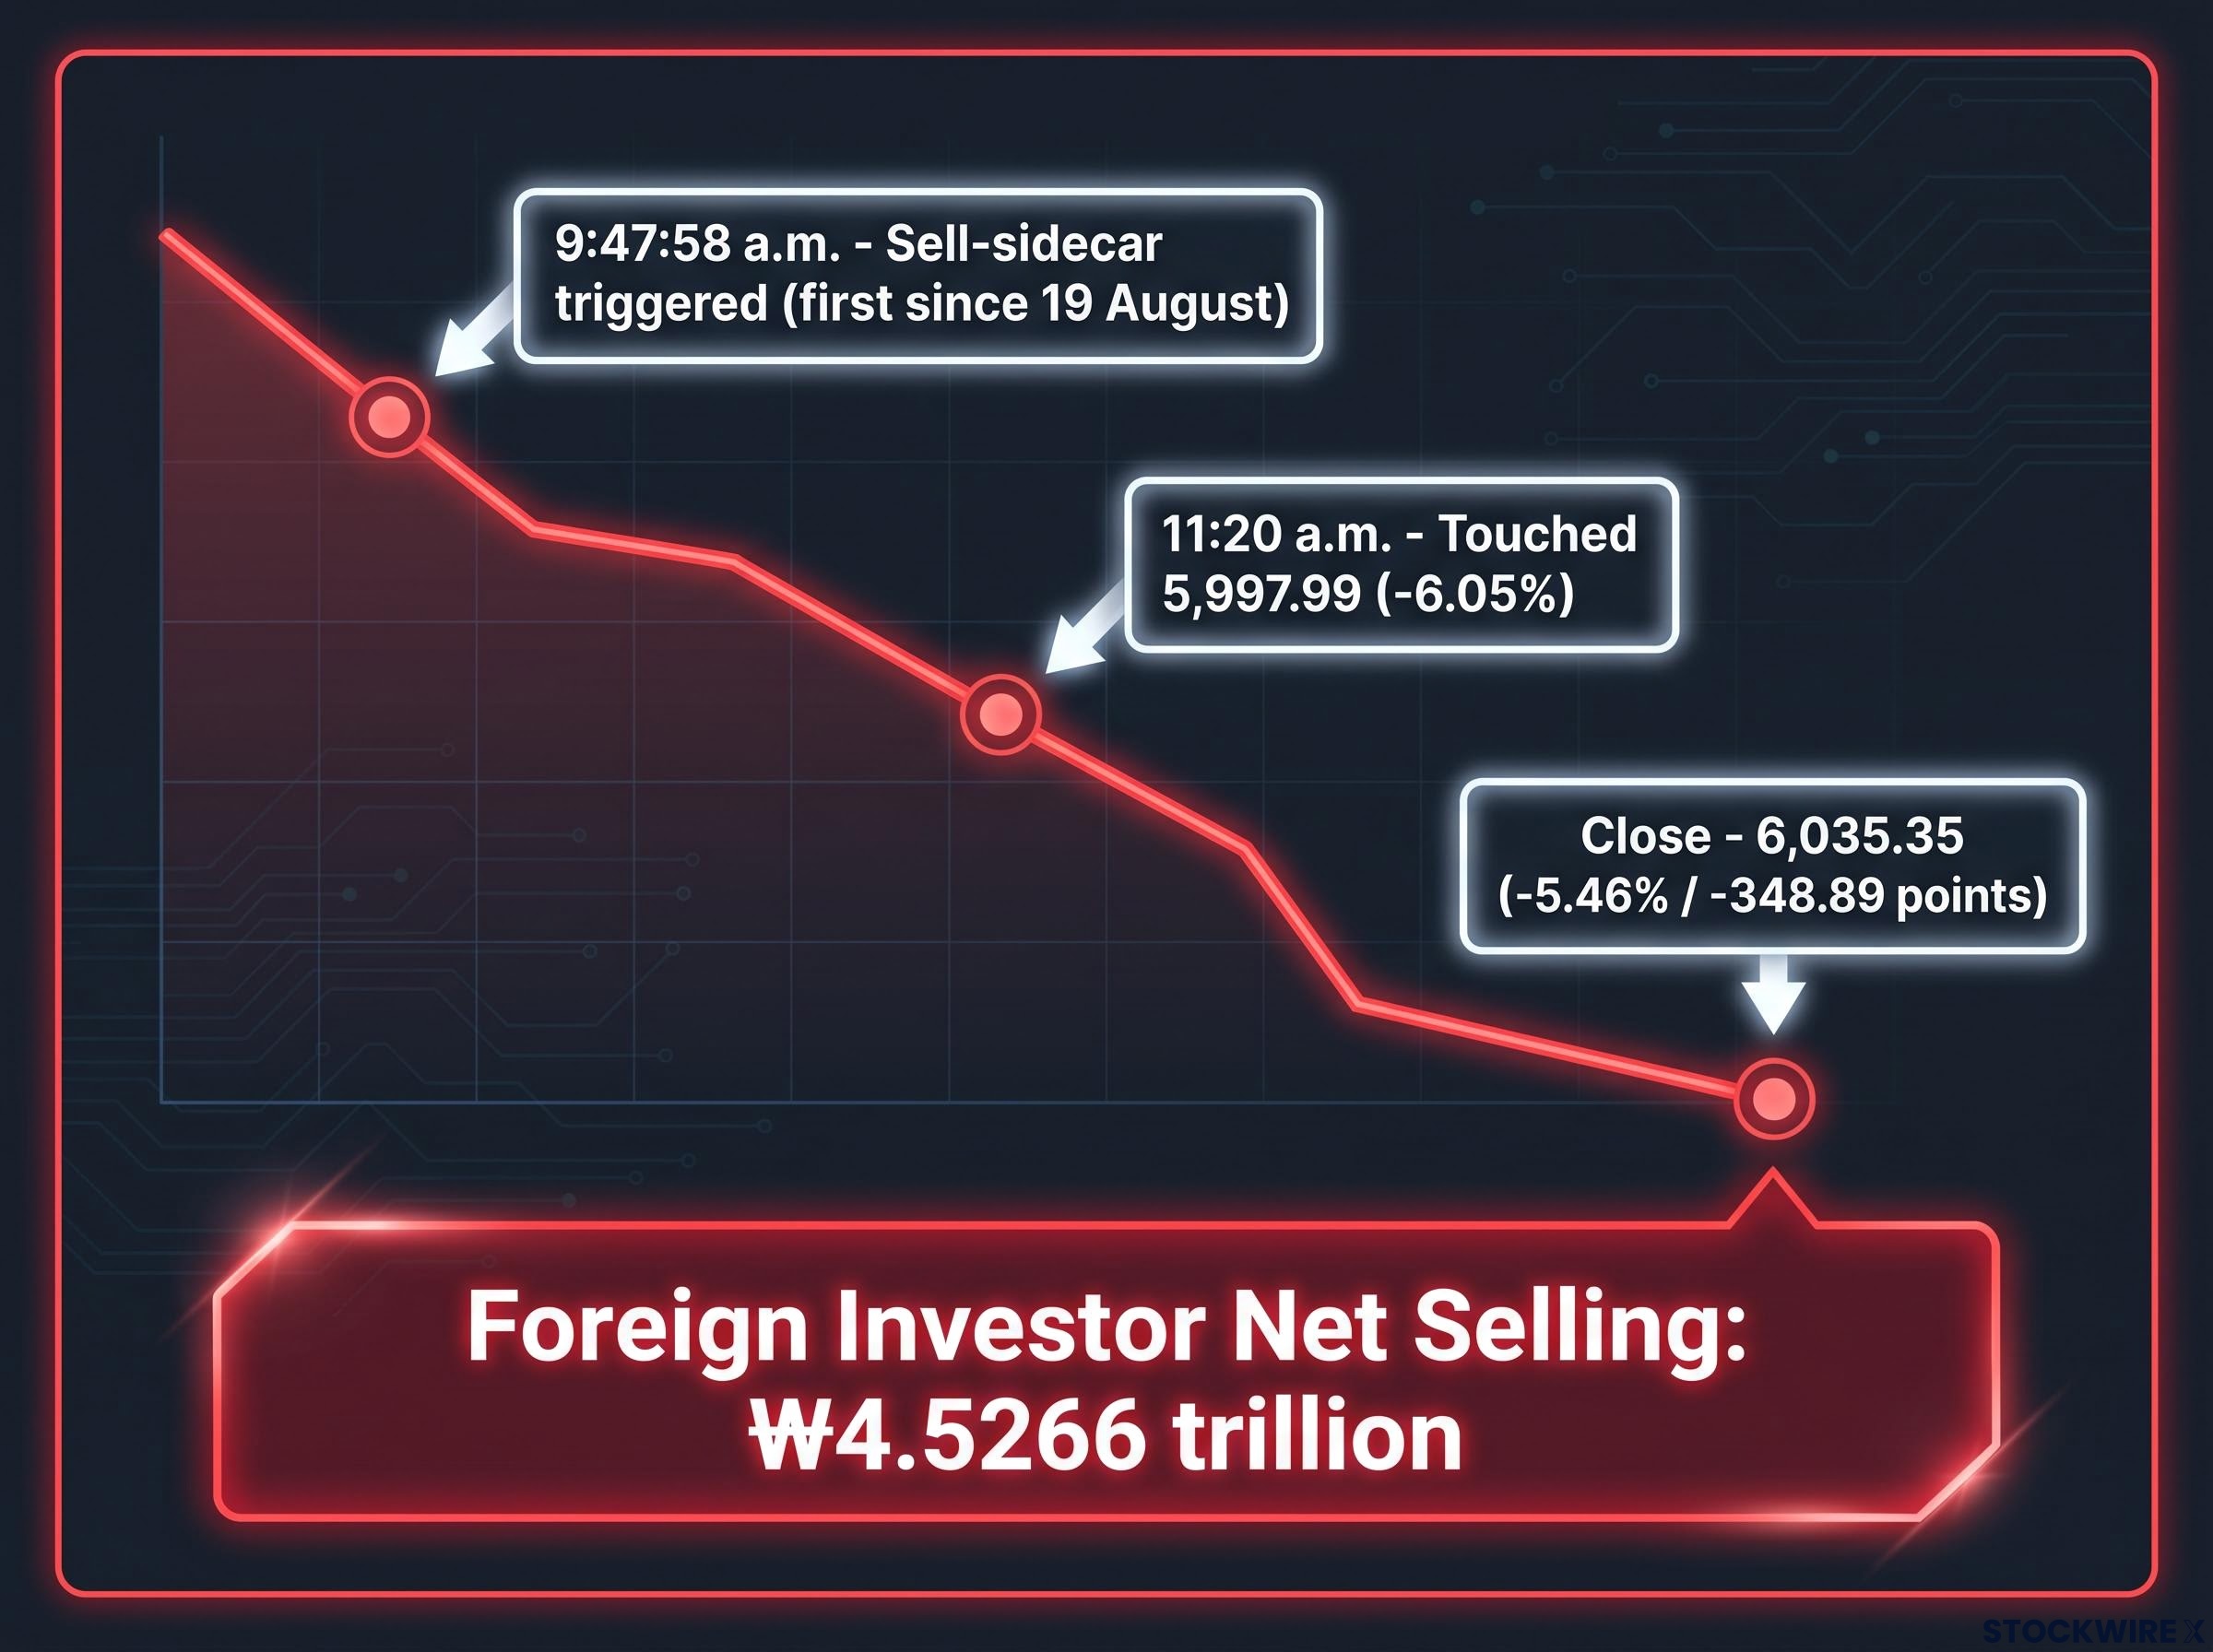
The KOSPI closed Tuesday at 6,035.35, down 348.89 points. At 11:20 a.m. it touched 5,997.99, a fall of 6.05%, and briefly broke below the 6,000 mark.
Earlier, at 9:47:58 a.m., the exchange had triggered a sell-sidecar, its first since 19 August. A sell-sidecar is a rule that pauses program selling for five minutes when futures fall sharply.
What triggered the selloff
The damage started in New York. Overnight, Micron fell 3.9% and SanDisk dropped 6.0% as chip stocks sold off.
Foreign investors then sold a net ₩4.5266 trillion of Korean shares, their sixth straight session of net selling, based on full-session totals. Smaller figures circulated during the day because reports captured different times.
The local spark came from China. CXMT reportedly announced progress on a DRAM design with roughly 30% smaller cell area, with next-generation server memory planned by year-end. DRAM is the short-term working memory chip in computers and servers, and it drives most of the profit at Samsung Electronics and SK hynix.
According to Seoul Economic Daily, CXMT’s yields and customer certification remain unverified. The selling may have run ahead of any proven change in the industry.
The CXMT 4F2 DRAM design remains unshipped, with no published specifications or qualification results, which helps explain why the selloff priced a signal rather than disclosed data.
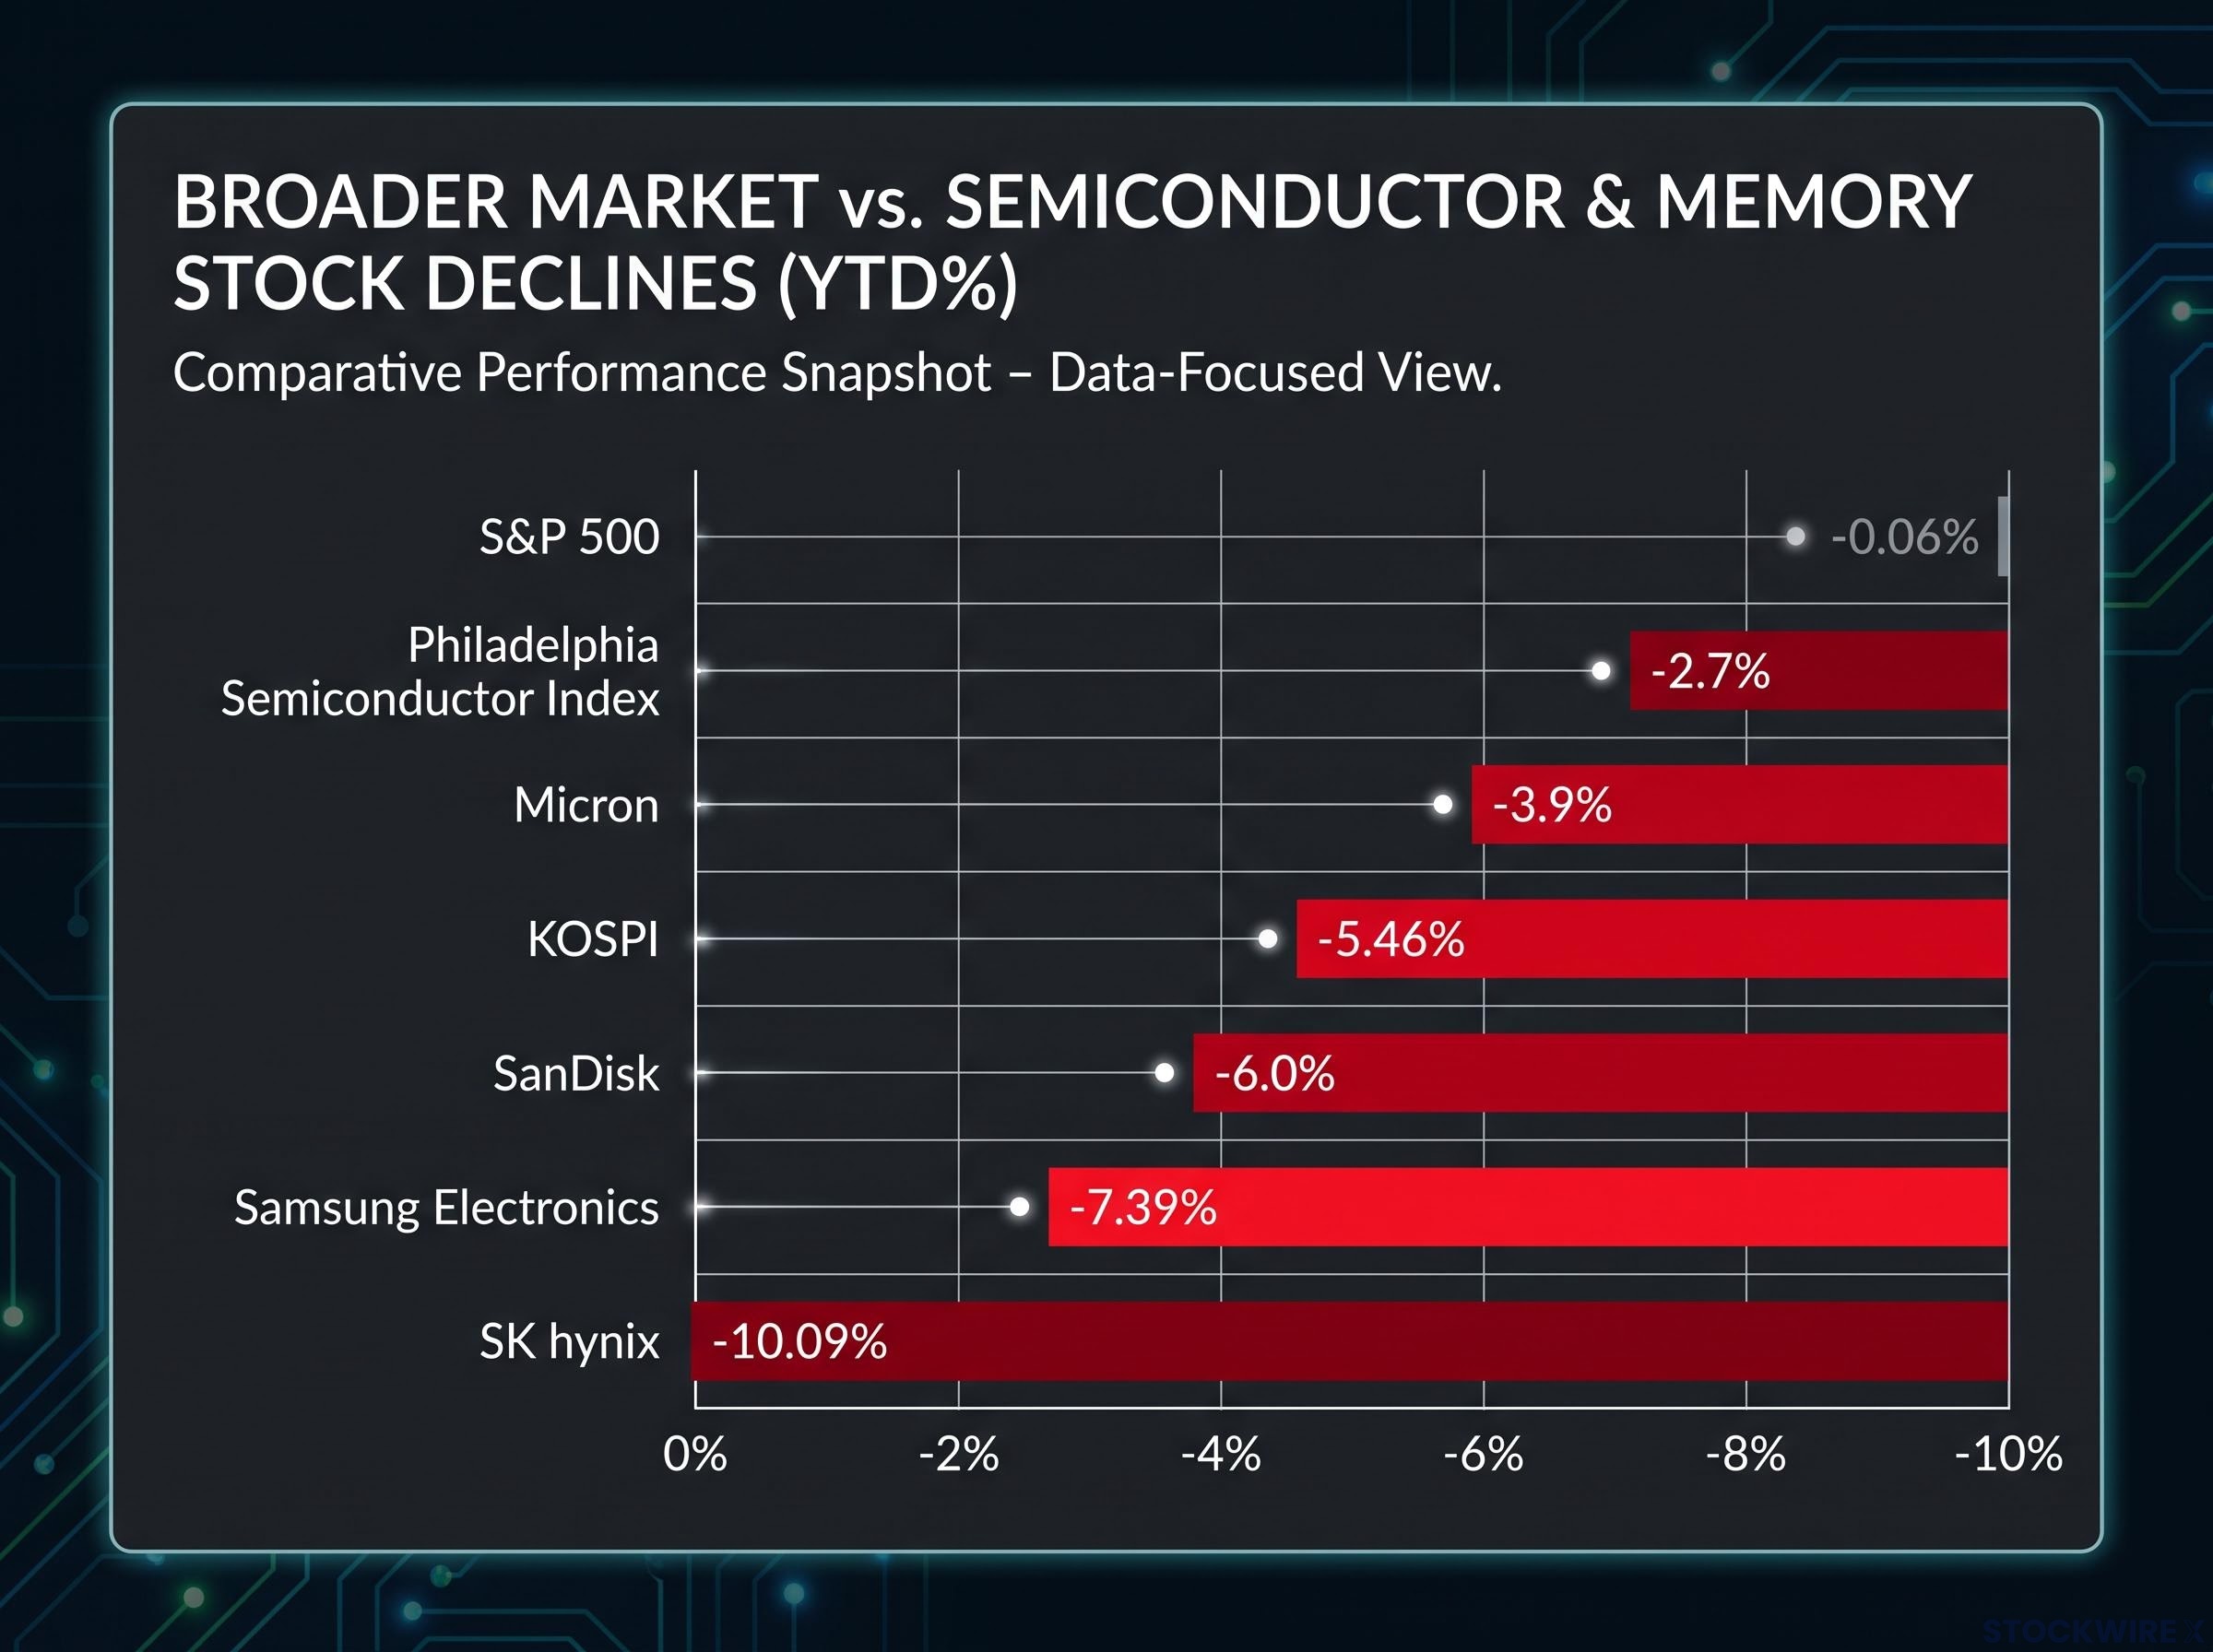
| Asset | Move | Context |
|---|---|---|
| KOSPI | -5.46% | Closed at 6,035.35 on Tuesday |
| Samsung Electronics | -7.39% | Hit by CXMT memory fears |
| SK hynix | -10.09% | Largest fall among Korean leaders |
| Philadelphia Semiconductor Index | -2.7% | US chip index, Monday session |
| Micron | -3.9% | US memory peer |
| SanDisk | -6.0% | US storage peer |
What the experts say
Han Ji-young of Kiwoom Securities described the fall as a market testing a short-term bottom. She said thin trading and weak sentiment left prices exposed, and that chasing the selloff after the 6,000 breach carries rebound risk. Charu Chanana of Saxo took a wider view.
Saxo’s Charu Chanana: CXMT was the clear trigger for the memory selloff, but the bigger issue is that investors are growing “much less forgiving” of the AI trade.
The lesson for you is about concentration. A competitive threat aimed at one industry, landing on a sector that was already nervous, did far more damage than the global rotation alone. Memory-chip exposure carries risks that a broad AI allocation may not reveal.
What does a 321-to-179 breadth reading say about a flat S&P 500?
Back in New York, the headline index barely moved. The S&P 500 closed at 7,807.24, down 4.30 points, while the Nasdaq Composite fell 0.44% to 27,245.90.
That looks like a quiet session. It was not.
Breadth measures how many stocks in an index rose versus how many fell. On Monday it told a very different story from the headline, according to Danske Research:
- 321 S&P 500 members advanced, while 179 declined
- The equal-weighted S&P 500, which gives every company the same weight regardless of size, outperformed the standard index again
- Breadth has been positive in seven of the previous eight sessions
A separate recap counted 318 advancers and 178 decliners, which points in the same direction.
The resolution is simple. A handful of very large AI and chip stocks fell hard enough to cancel out gains across most of the index. The typical stock had a good day; the biggest ones did not.
The money went to European equities and defensive sectors, with consumer staples the top performer, Danske said. Some reports put utilities and staples gains near 4%, but those figures have not been independently confirmed. Nvidia’s move for the session and full European index closes were not available.
Money moving into consumer staples and European equities fits a classic sector rotation strategy, in which institutional capital repositions ahead of economic changes and sector leadership becomes a forward-looking signal.
For you, strong breadth signals money moving within equities rather than leaving them. That weakens the case for an imminent broad correction. It does not show that the AI and chip pullback will stay shallow. If you held equal-weight or defensive funds, you probably beat cap-weighted holders on the day.
Is the leadership that is being sold earnings-backed or stretched?
Danske offers the reassuring answer first. It called this a substantial rotation, not the start of a broad US correction, and pushed back on bubble comparisons.
Danske Research: The market’s recent winners got there chiefly because their profits grew far faster, not because investors were paying higher multiples for them. That distinction shapes how exposed those winners really are.
In plain terms, prices rose because profits rose, not because investors simply paid more for each dollar of profit.
That comfort is real, but conditional. Saxo warned that a valuation reset could broaden if earnings expectations weaken. Crowded positioning and demanding forecasts can force sharp moves even in companies with genuine profits.
Strategists describe the current AI dispersion phase as one where earnings delivery and valuation discipline separate genuine earners from story plays, which is why profit-backed leaders can still reprice sharply.
The CXMT episode shows how. Korean memory leaders were repriced before any evidence of large-scale Chinese production. Kim Yun-jeong of LS Securities framed the Korean fall as a chip-specific competitive threat, not proof of a global correction.
There is precedent for recovery. During the July 2026 crash, the KOSPI dipped below its 200-day moving average (the average closing price over the past 200 trading days) for only a few sessions, Han noted.
Signals that would change the picture:
- Breadth turning negative while AI and chip names keep falling
- Downgrades to earnings forecasts for AI and memory companies
- Verified progress on CXMT’s yields or customer approvals
Earnings support lowers the odds of a systemic unwind. It does not protect your most expensive AI and chip holdings from a sharp repricing if expectations slip.
These views are speculative and subject to change based on market developments and company performance.
What the rotation changes, and what it does not
Monday’s flat close hid a genuine reallocation away from AI leaders. Breadth argues against a broad market correction, but the sharpest risk now sits in expensive AI and memory exposure, where Korea showed how quickly sentiment can turn.
Three variables will tell you whether the rotation stays contained: whether breadth holds up, whether foreign selling in Korea extends past six sessions, and whether CXMT’s claims are verified. Until then, the headline index is the least useful number to watch.
Investors weighing whether six sessions of foreign selling will persist can turn to our detailed coverage of Korean foreign flows, which shows how foreign net selling reversed sharply within a single month earlier this year.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.
—