Most people picture a property bargain as a house that sells well below what the street says it is worth. Those are rare. On the ASX, whole portfolios of warehouses, shopping centres and office towers have regularly traded 10%, 20% or even 40% below their stated asset value, and that gap is what draws many investors to REITs.
A real estate investment trust (REIT) lets you co-own large commercial properties alongside thousands of other investors. Someone else collects the rent and deals with tenants. The first hurdle is the language: results announcements are full of acronyms that can make a cheap trust look confusing.
The gap is wide right now. A comparison of 20 ASX property trusts published by Richer.au last month put the median discount to net tangible assets at about 26%.
This explainer covers how Australian REITs (A-REITs) work, what the key terms mean, and why a discount on its own does not make a trust a bargain.
How do REITs let you own property without being a landlord?
If you have ever owned an investment property, you know the workload. You find tenants, chase late rent, fix the hot water system and wait out vacancies, all while one asset carries your whole stake.
A REIT swaps those roles. An A-REIT pools money from many investors to own property, and you buy a slice by purchasing units or stapled securities on the ASX, the same way you buy shares.
The properties span most of the commercial market:
- Offices: Dexus (ASX: DXS) is a large office owner
- Shopping centres: Scentre Group (ASX: SCG) runs major retail centres
- Warehouses and industrial: Goodman Group (ASX: GMG) focuses on logistics property
- Diversified portfolios: Stockland (ASX: SGP) and Mirvac (ASX: MGR) hold a mix
- Hotels and cinemas: held by some specialist trusts
The manager, or responsible entity, handles leasing, rent collection and maintenance. You receive distributions, which are cash payments made from rental income, usually quarterly or half-yearly.
Landlord vs REIT investor A landlord finds tenants, collects rent, organises repairs and carries the vacancy risk on one property. A REIT investor buys units on the ASX, receives a share of rent from many properties and leaves the management to professionals.
Those payments can be meaningful. Morningstar’s August 2026 review found several A-REITs yielding roughly 6%-7%, and Waypoint REIT (ASX: WPR) yielded 7.1% at its 26 August 2026 price. A qualifying trust generally passes taxable income through to you rather than paying company tax on distributed rent, and some distributions include tax-deferred amounts.
The trade-off is that you gain commercial property exposure with a small amount of capital and no tenant management, but you also take on share-market price swings. A house you own outright never shows you a price every day; a REIT does.
What does a stapled structure mean?
A stapled security combines units in a property trust with shares in a company or management business. The two are joined and trade as a single security, so you cannot buy one part without the other. Many large A-REIT groups use this setup.
The ASX A-REIT investor guidance sets out how responsible entities and stapled securities fit together, so you can see which part of a listed group holds the properties and which part runs the management business.
When big ASX news breaks, our subscribers know first
The REIT jargon you need before you can spot a bargain
The acronyms look like a wall at first. Group them by the question each one answers, and they shrink into a short toolkit.
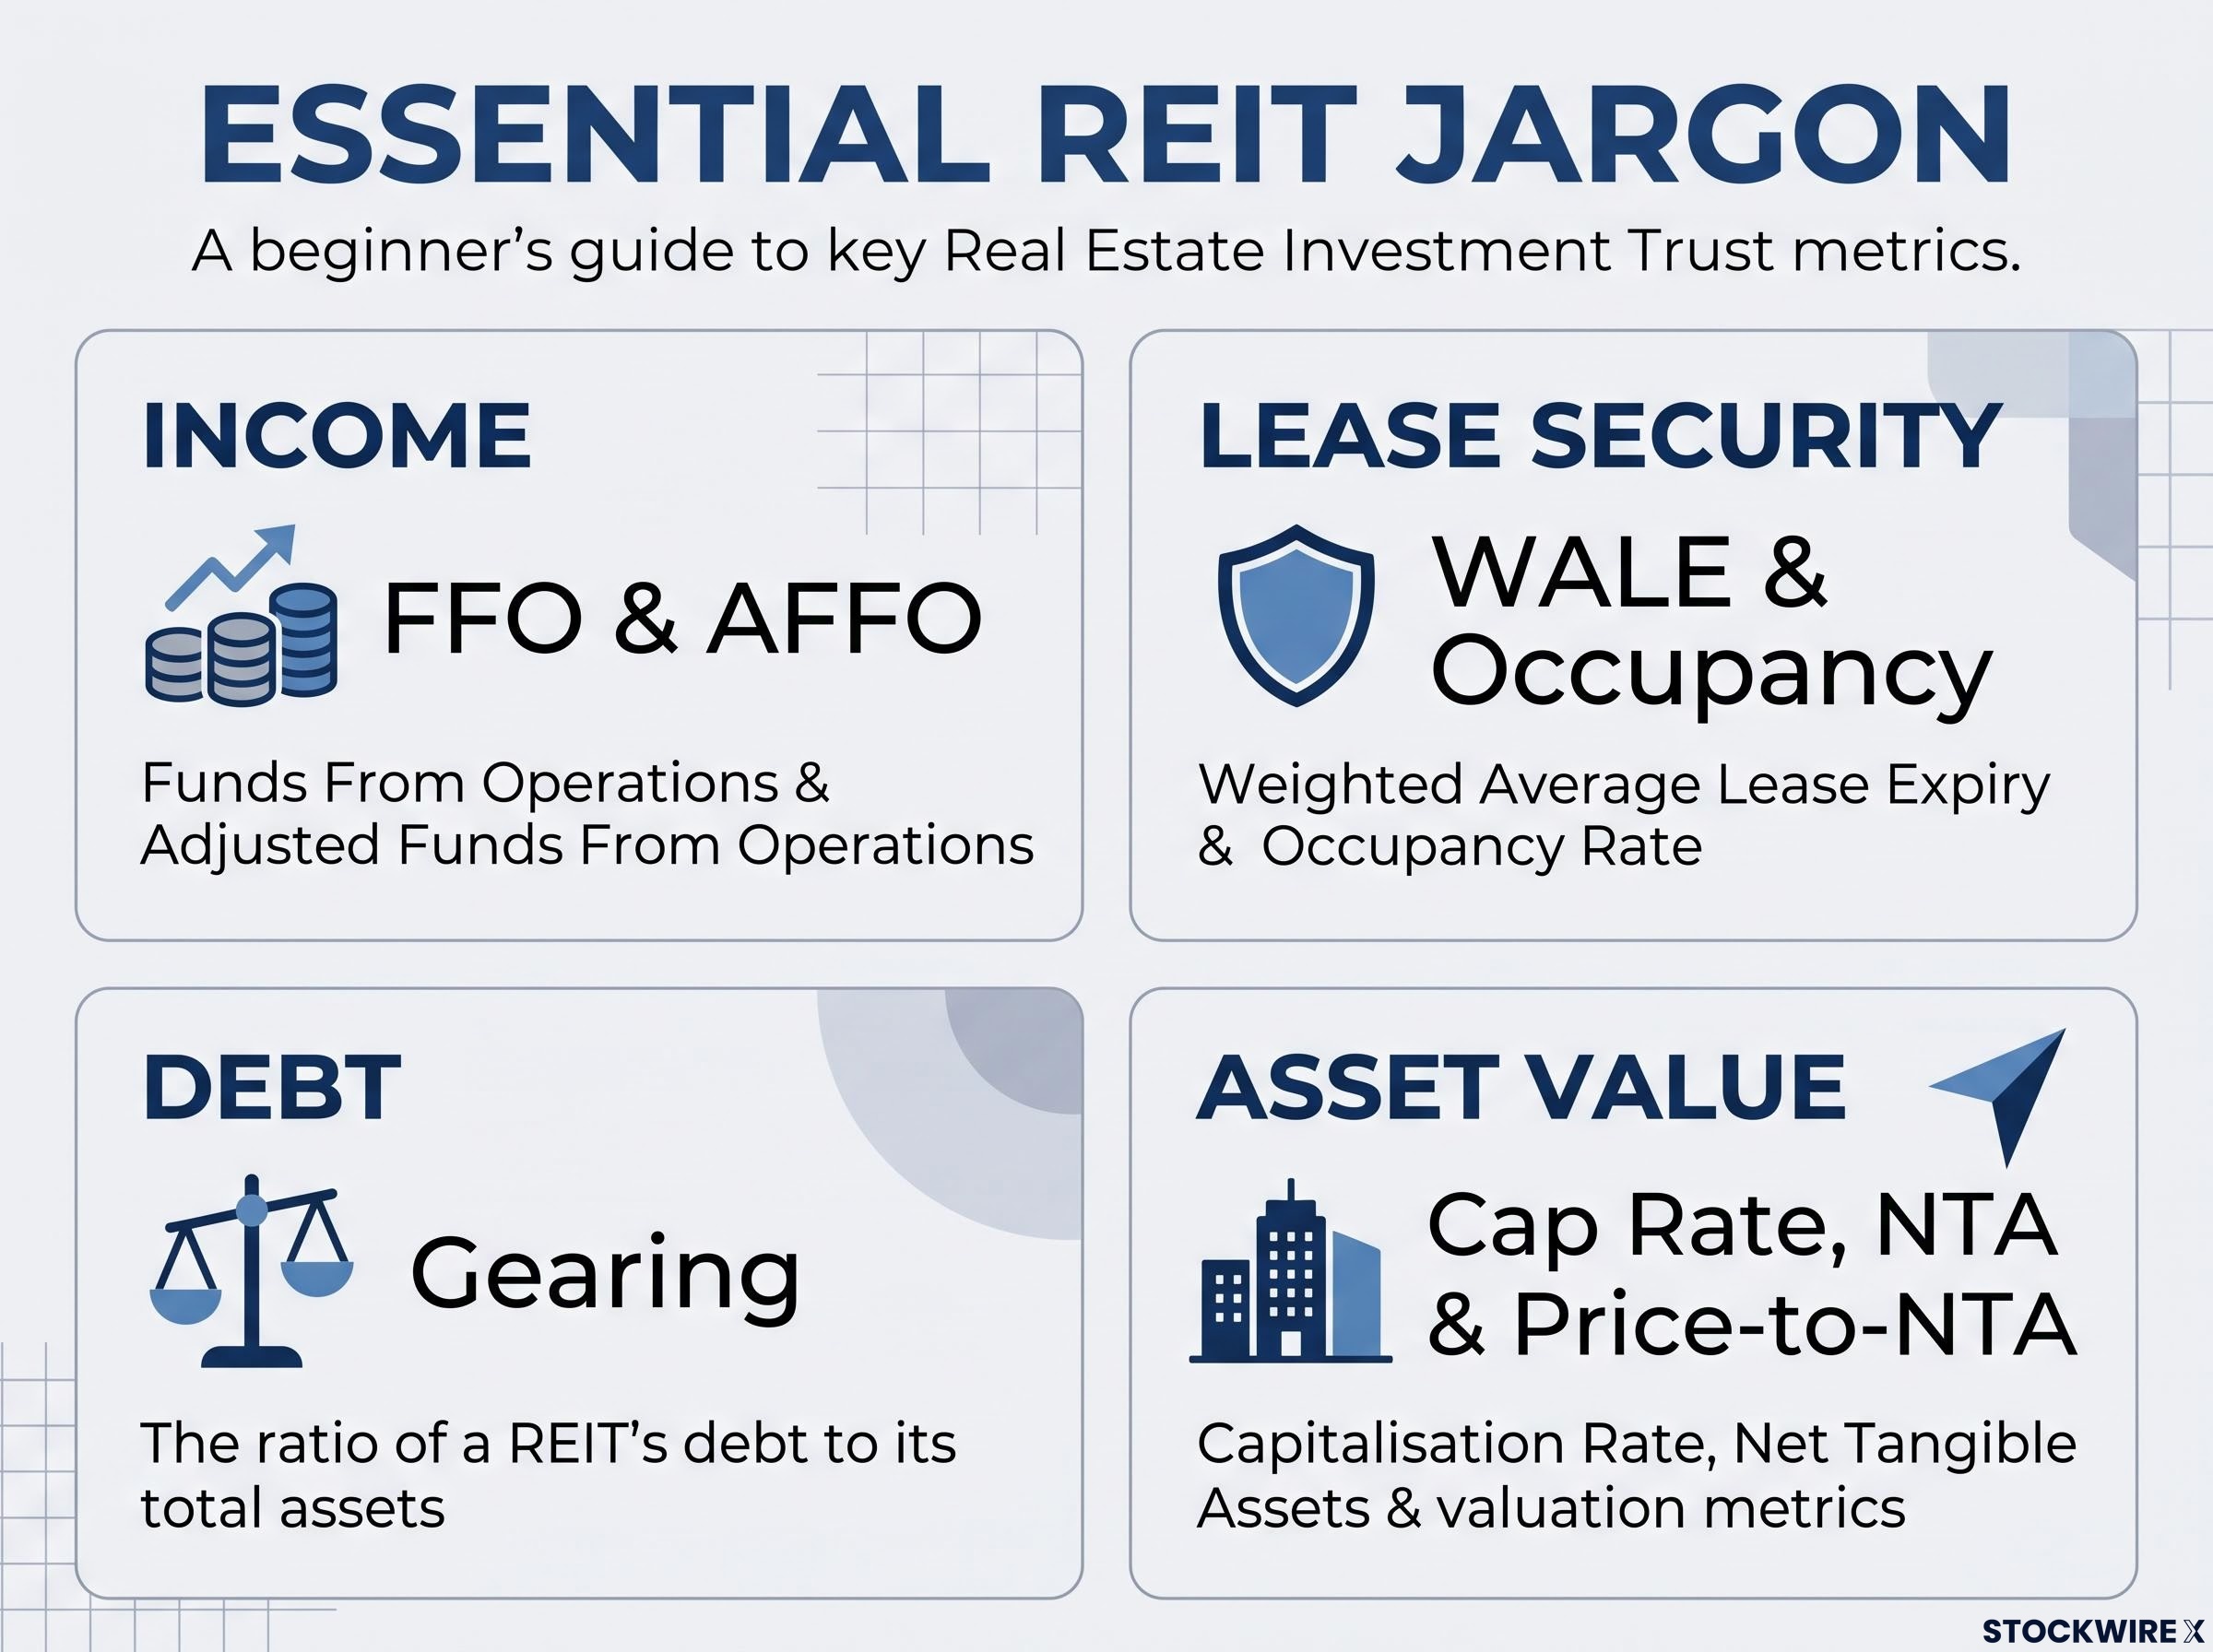
Grouping A-REIT acronyms into 4 logical categories helps make complex financial terminology much easier to understand.
Income questions are answered by FFO and AFFO. Lease security comes from WALE and occupancy. Debt is measured by gearing. Asset value sits with cap rate, NTA and price-to-NTA.
| Term | Plain-English meaning |
|---|---|
| FFO (funds from operations) | Recurring operating earnings: statutory profit adjusted for non-cash and one-off items. |
| AFFO (adjusted FFO) | FFO after recurring capital spending; a guide to cash available for distributions. |
| WALE (weighted average lease expiry) | Average remaining lease length, weighted by rent. Longer gives income visibility but can delay resetting rents to market. |
| Occupancy | The share of a property or portfolio that is leased. |
| Gearing | Debt relative to asset value or equity. It magnifies both gains and losses. |
| Cap rate | Net operating income divided by property value. A higher cap rate means a lower value for the same income. |
| NTA (net tangible assets) | Tangible assets minus debt and liabilities, divided by the number of securities on issue. |
| Price-to-NTA | Security price divided by NTA per security. Below 1.0 means trading below asset backing. |
| Discount to NTA | The percentage by which the price sits below NTA. |
The pair that matters most for spotting value is NTA and price-to-NTA. NTA estimates what each security would be worth if the properties were valued as reported and the debts paid off. Price-to-NTA compares that figure with what the market is charging you.
A price-to-NTA of 0.65x, for example, works out to roughly a 35% discount. Here is a real case.
Worked example: Mirvac Mirvac reported NTA of $2.33 per security at 30 June 2026. Its price on 27 August 2026 was $1.82. Dividing $1.82 by $2.33 gives about 0.78x, or roughly a 22% discount.
Once you can read these terms, a results announcement or broker note becomes a checklist you can use to compare trusts yourself.
Why do A-REITs trade below the value of their properties?
With NTA in hand, the obvious question is why anyone would sell a dollar of property for 74 cents. The answer builds one cause at a time.
The sector has had a rough run. State Street data shows the S&P/ASX 200 A-REIT index fell 8.38% year to date and 14.34% over the 12 months to 30 September 2026. Richer.au, citing BDO, reported that 17 of 20 trusts traded below their 30 June 2026 NTA, with a median discount of 26% against 12% a year earlier.
Five drivers do most of the work:
- Interest rates and bond yields. Higher rates make distributions less attractive next to safer fixed income and raise borrowing costs. The RBA cash rate was most recently reported at 4.60%, the highest since 2011.
- Leverage. When property values fall, the debt stays the same, so the loss lands hardest on equity holders.
- Refinancing risk. Debt falling due soon may need replacing at higher rates, or force asset sales or dilutive capital raisings.
- Office vacancy and sentiment. Hybrid working and higher tenant incentives push investors to price in leasing costs and downtime.
- Listed prices move faster than NTA. Share prices react daily, while independent valuations update periodically and can lag.
Valuation cushions are thin. Morgans estimated cap-rate spreads to the real 10-year government bond yield at about 3.8% for office, 3.0% for retail and 3.3% for industrial, below the historical 4%-6% range. That leaves property values exposed if bond yields rise further.
A more recent bond yield surge has shown how quickly cap-rate expansion can feed through to NTA, which is why you should check how old a trust’s valuations are.
Secondary factors add to the gap: management quality and fees, appraisals that may be optimistic, concentration in one sector or tenant, and thin trading in smaller trusts.
| REIT | NTA per security | Price | Implied discount | Price date |
|---|---|---|---|---|
| Dexus | $8.92 | $5.78 | ~35% | 27 August 2026 |
| Mirvac | $2.33 | $1.82 | ~22% | 27 August 2026 |
| GPT Group | $5.61 | $4.65 | ~17% | 27 August 2026 |
| Stockland | $4.39 | $4.42 | ~0.7% premium | 27 August 2026 |
| Waypoint REIT | $2.92 | $2.41 | 17.5% | 26 August 2026 |
Prices are August 2026 closing prices, not live prices. The table includes GPT Group (ASX: GPT).
Office-heavy Dexus sat at roughly a 35% discount while Stockland traded at about NTA. The market is pricing risks the NTA figure has not yet shown, so treat every discount as a question first: why is this one cheap?
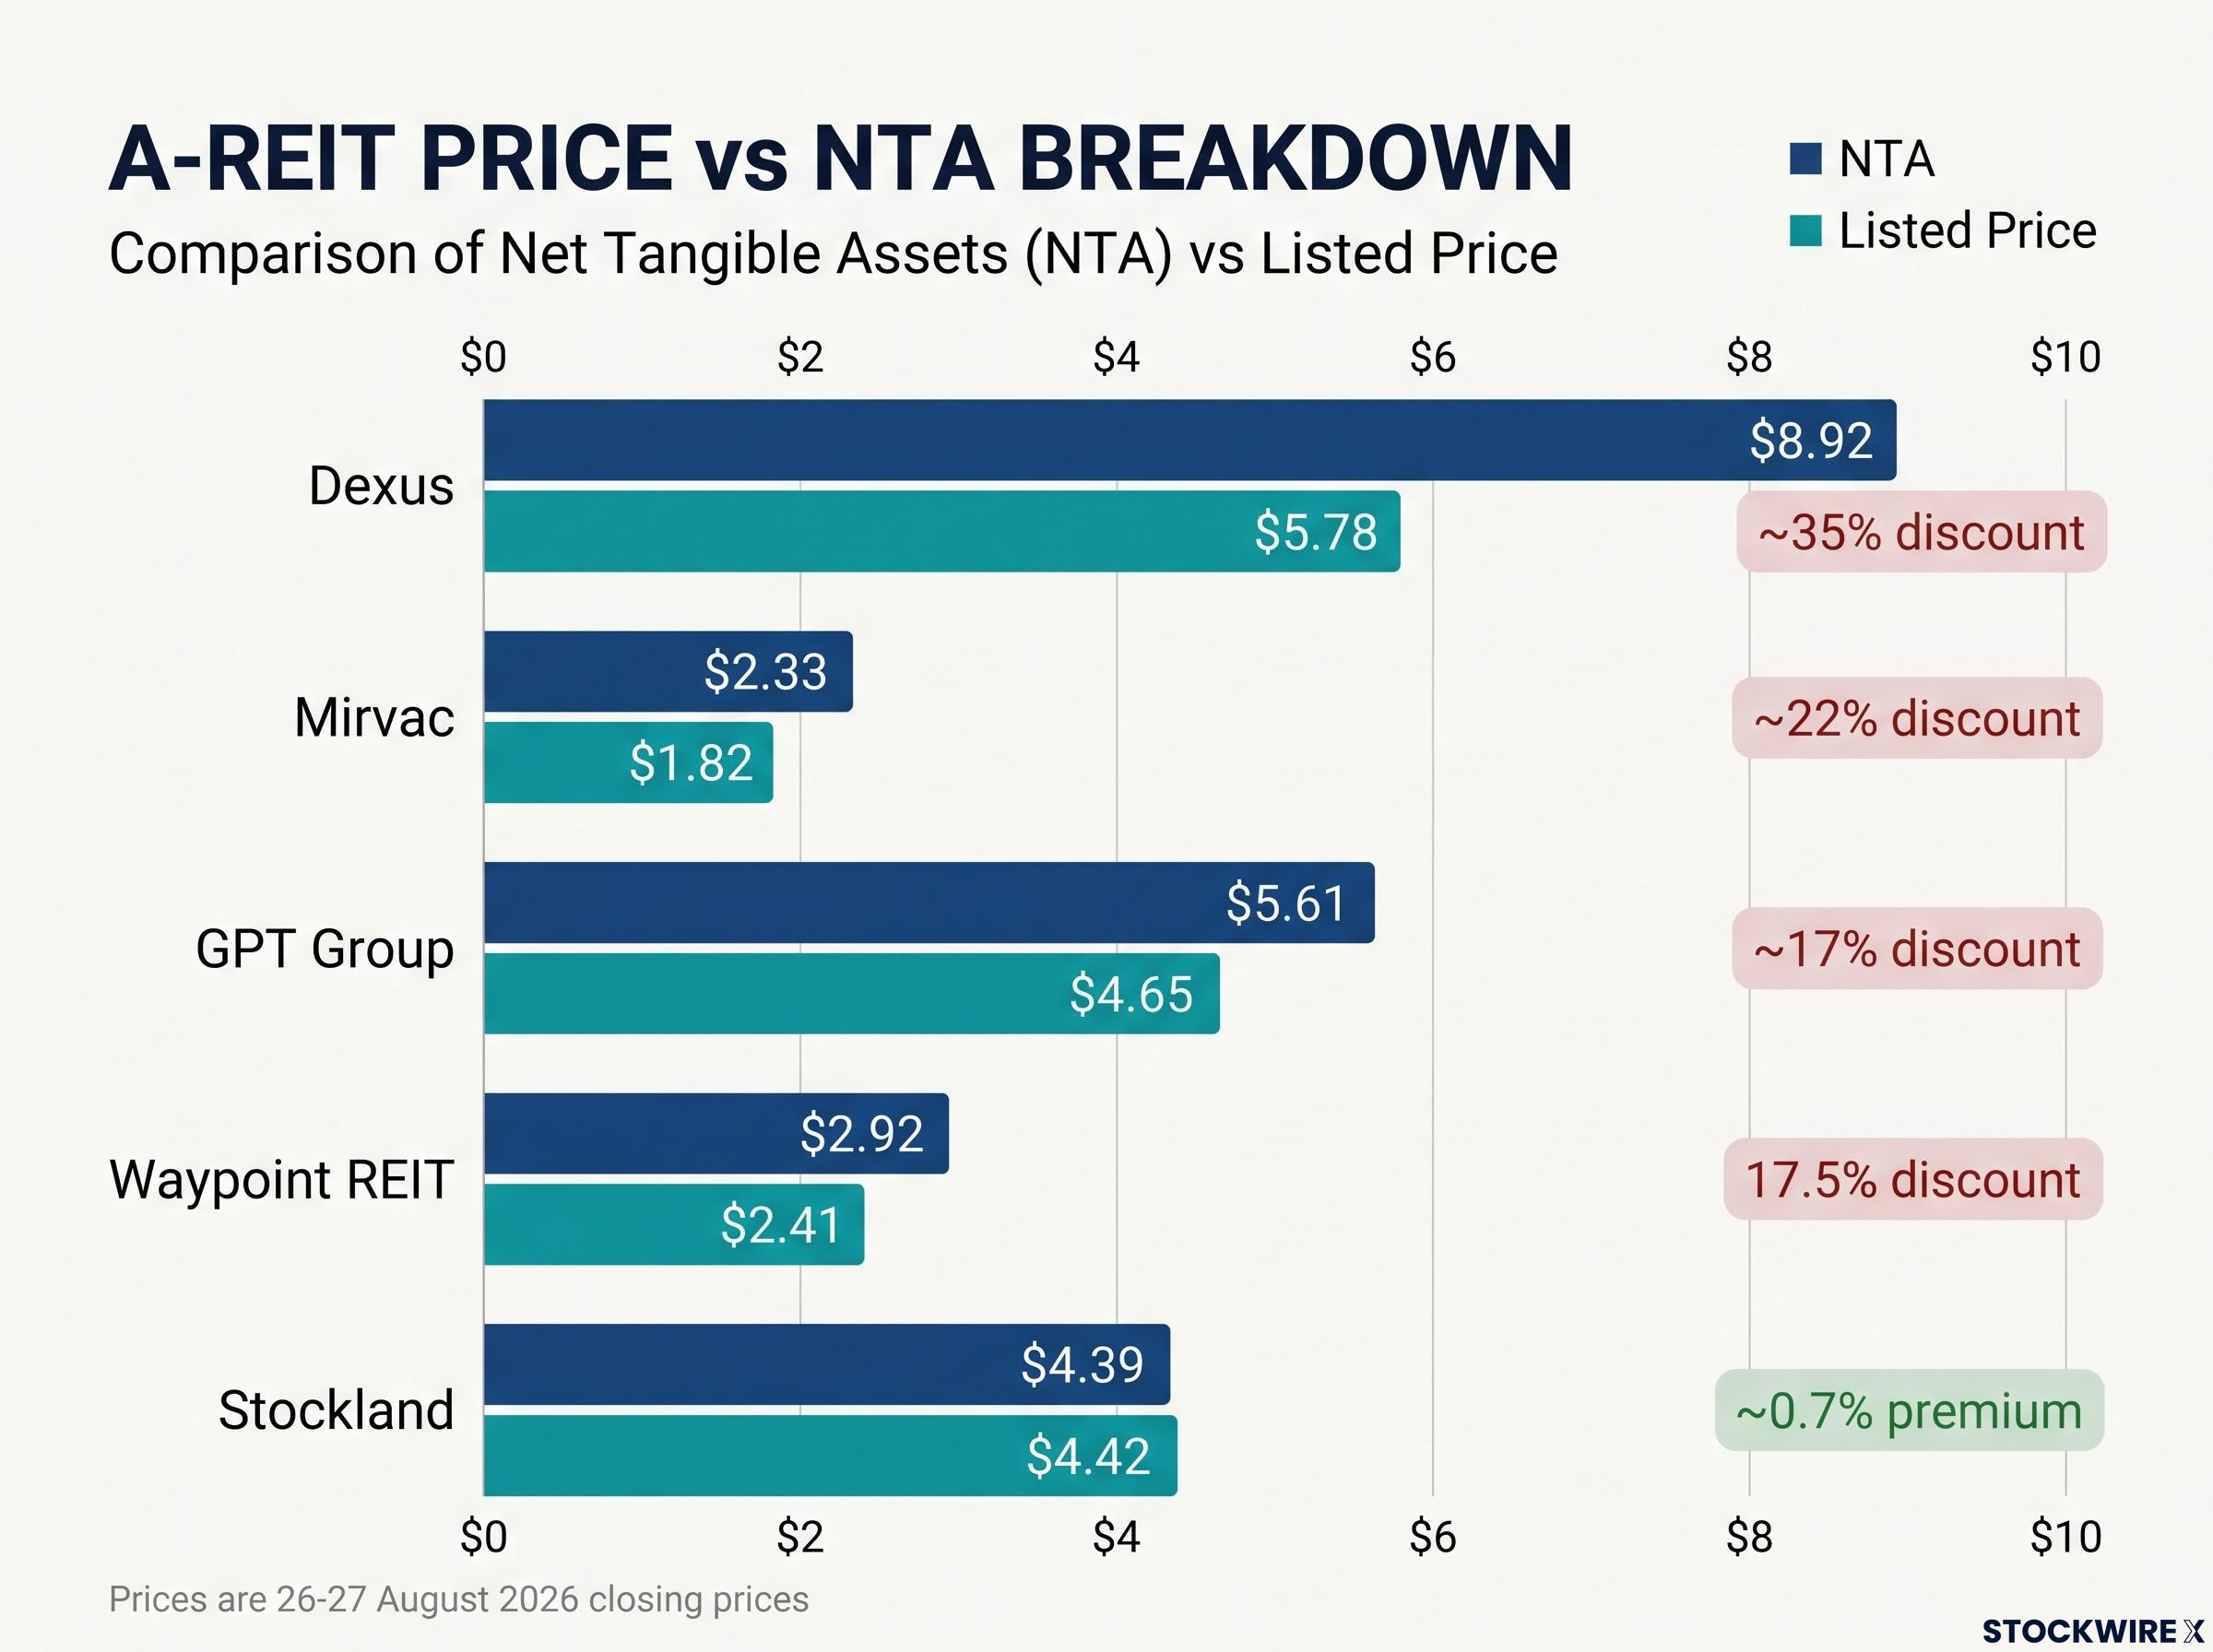
Comparing 5 A-REITs on 26-27 August 2026 shows discounts ranging from 17.5% for Waypoint REIT to ~35% for Dexus.
When does a discount close, and when is it a trap?
Sometimes the market is simply wrong, and someone with deep pockets notices.
Where discounts have closed
National Storage REIT is the standout case. A Brookfield-led consortium with GIC bought it at $2.86 per security, a 26.5% premium to the undisturbed price and about 13% above its June 2025 NTA of $2.53.
Boards act too. Mirvac launched an on-market buyback of up to $200 million while trading at about a 22% discount, and Dexus initiated its own buyback. Buying back securities below NTA can lift NTA for the holders who remain, provided the asset values hold up. Stockland, trading near NTA, shows a discount can close when the market trusts the portfolio and balance sheet.
Where discounts have persisted
Other trusts have improved on paper without the price following. Dexus Convenience Retail REIT (ASX: DXC) lifted NTA 6.0% to $3.86, yet traded at $2.75, about a 29% discount, even after doubling its buyback to 5% of securities.
Centuria Industrial REIT (ASX: CIP) sat at about a 25% discount despite NTA of $4.01 at 30 June 2026. Dexus Industria REIT (ASX: DXI) traded at about a 31% discount in August 2026. Across the sector, Morgans found discounts of 21%-48% persisted in ten of the 15 names it covers.
| Example | What happened | Why it matters |
|---|---|---|
| National Storage REIT | Taken over at $2.86, above NTA | A listed discount can attract a private buyer |
| Mirvac and Dexus | Buybacks while trading below NTA | Signals board confidence, but no guarantee |
| Dexus Convenience Retail | NTA up, discount near 29% | Better valuations do not force a re-rating |
The ASX’s 2026 outlook flags continuing exposure to interest rates, property conditions, occupancy and tenancy risks. Before calling a discount a bargain, test these points:
- Is the NTA stale? Check the valuation date against recent cap-rate moves.
- How high is gearing? More debt means more downside if values fall.
- When does debt mature? Near-term maturities raise refinancing risk.
- What are occupancy and WALE? Strong, long leases support the income.
- Is the distribution covered? Compare payouts with AFFO.
- What about fees and concentration? External management and single-tenant exposure can justify a gap.
For you, the lesson is that a discount alone is not a buy signal. What matters is whether the balance sheet, leases and assets justify the gap or leave room for it to close. All figures here are historical snapshots, not recommendations.
For readers wanting a repeatable method, our dedicated guide to valuing ASX REITs shows how to stress-test reported NTA with a cap-rate shock before trusting any discount.
A beginner’s checklist for reading the next A-REIT result
You now have three tools. REITs take the landlord work off your hands, the jargon turns a results release into readable numbers, and a discount needs explaining before you trust it.
The 26% sector median discount across 20 trusts gives you a reference point. When the next result lands, check the NTA date, gearing, WALE and debt maturities, then compare price-to-NTA against peers and that median.
This is the first part of a beginner series on A-REITs. Figures quoted are snapshots, so check current ASX announcements before acting and consider professional advice.
This article is for informational purposes only and should not be considered financial advice. Investors should conduct their own research and consult with financial professionals before making investment decisions.