
Entire acquisition strategy outlined: up to $112.1m deal, 18% EPS accretion
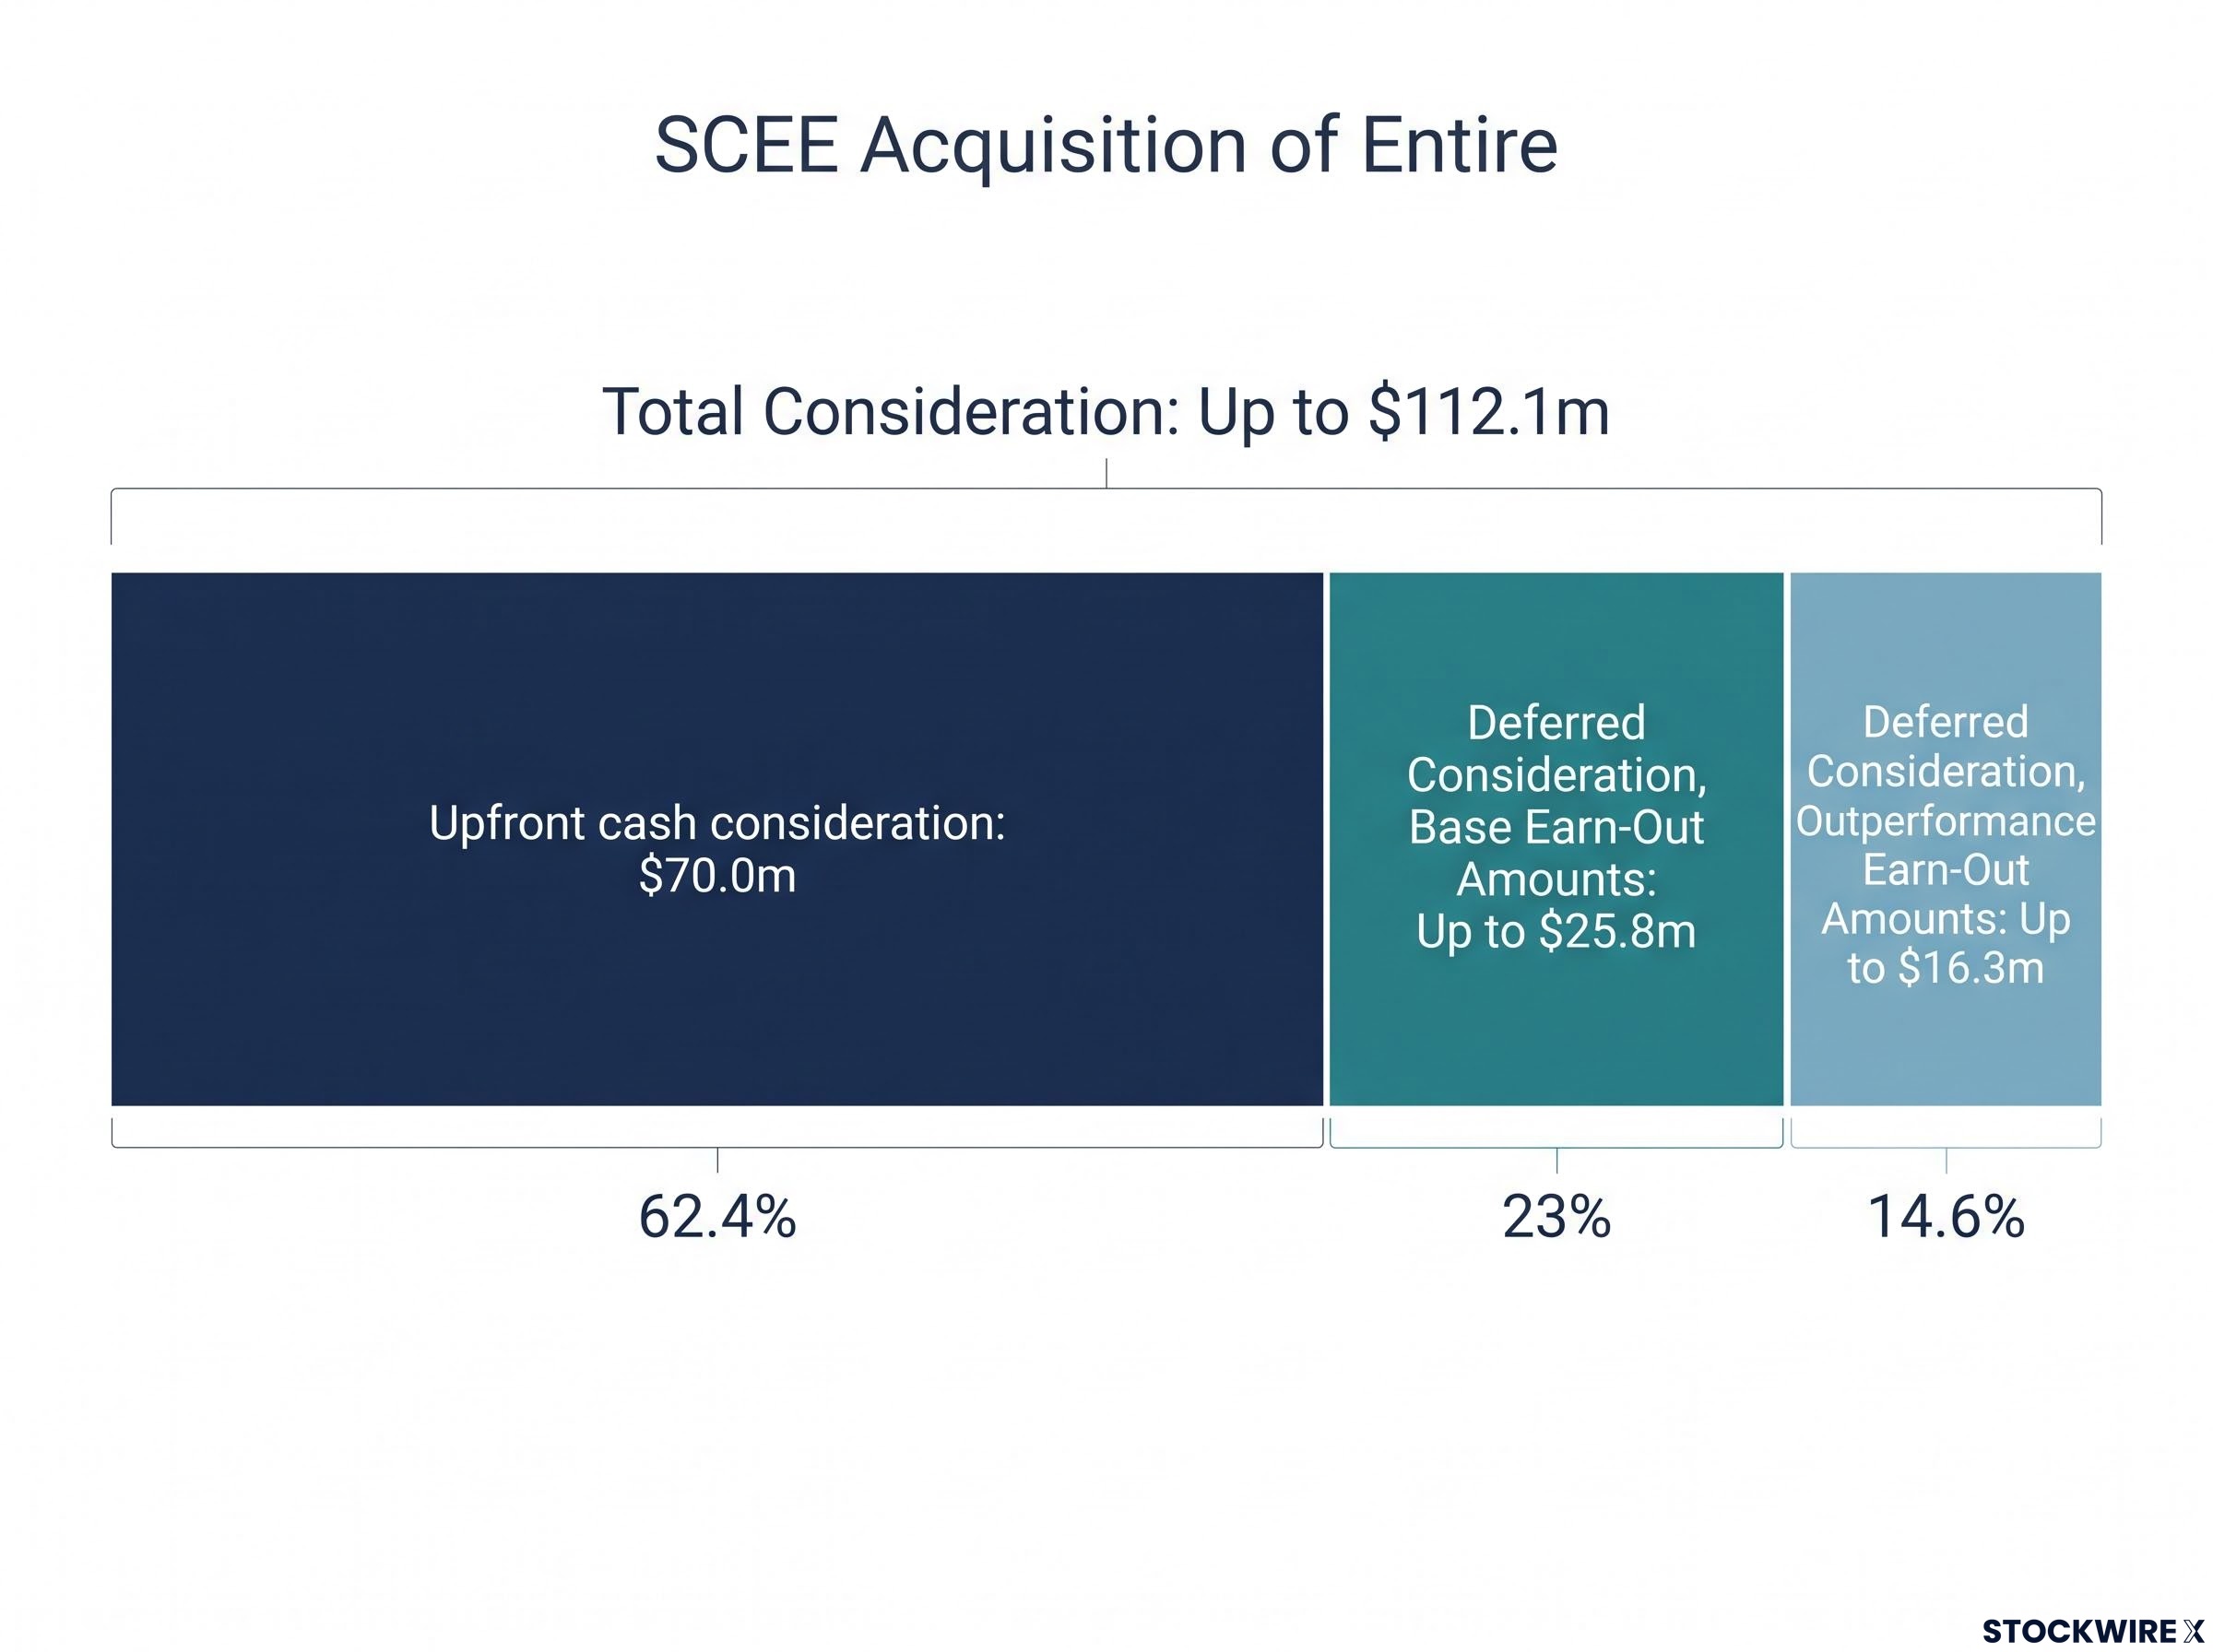
In its 12 October 2026 investor presentation, Southern Cross Electrical Engineering (ASX:SXE), referred to as SCEE, outlined a Share Purchase Agreement for the SCEE acquisition of Entire. The agreement covers 100% of Entire Operations Pty Ltd for total consideration of up to $112.1m on a cash-free debt-free basis.
Management detailed $70.0m cash payable on completion, to be funded through SCEE’s existing cash reserves. The transaction is expected to be immediately accretive, with EPS accretion of at least 18% on an FY27F pro forma basis.
SCEE’s FY27 EBITDA guidance was increased to at least $110m, assuming completion occurs on 1 November 2026. Anticipated completion on that date remains subject to customary closing conditions.
The upgrade to FY27 guidance builds on a record FY26 result, in which underlying EBITDA reached $77m and SCEE entered the new year with an order book of $810m.
For investors, the presentation positions the deal as a cash-funded addition of a new mechanical (HVAC) discipline. SCEE stated it will retain a strong balance sheet post-completion.
SCEE investor presentation
“The acquisition aligns with SCEE’s M&A strategy offering further geographic diversification, expansion into new and existing adjacent disciplines, and increased exposure to recurring services and maintenance works.”
When big ASX news breaks, our subscribers know first
Deal structure and earn-out terms
Consideration breakdown
The presentation’s appendix sets out the consideration in three parts. The deferred amounts are contingent on Entire meeting EBIT (earnings before interest and tax) targets, and are not guaranteed.
| Component | Amount | Condition |
|---|---|---|
| Upfront cash consideration | $70.0m | Payable on completion |
| Deferred Consideration, Base Earn-Out Amounts | Up to $25.8m | $8.6m each for FY27, FY28 and FY29, if Entire EBIT is equal to or greater than $17.0m |
| Deferred Consideration, Outperformance Earn-Out Amounts | Up to $16.3m | $3.3m for FY27 at EBIT of $21.4m; $5.1m for FY28 at $23.8m; $7.9m for FY29 at $27.5m; reduced pro rata down to nil at EBIT of $17.0m |
Valuation multiples
The consideration represents 5.5x FY26A EV/EBIT, assuming the sellers receive the maximum Base Earn-Out Amounts. It represents 4.1x FY29F EV/EBIT assuming the maximum Outperformance Earn-Out Amounts, implying EBIT of at least $27.5m in FY29F.
The earn-outs link part of the price to Entire’s performance. All existing employee executive shareholders are to remain with the business on long-term employment contracts extending beyond the earn-out period.
Completion is conditional on:
- ACCC waiver or approval
- No material adverse change in Entire
- Execution of employment contracts with the existing employee shareholders
- Release from Entire’s existing financial arrangements
Due diligence has been finalised. The agreement contains a standard set of warranties covered by warranty and indemnity insurance, subject to limited exclusions.
What Entire brings to SCEE
Entire at a glance
Entire is a Melbourne-based fire protection and mechanical (HVAC) contractor established in 1985. It offers integrated services supported by in-house fabrication.
Key figures cited in the presentation:
- Approximately $191m FY26 revenue
- Approximately $17.5m FY26 EBIT
- Approximately 490 employees across Victoria and Queensland
- Approximately 120 active clients
- $800m+ project pipeline
- Approximately 200 managed sites
Based on estimated segmentation, FY26A revenue by capability was Mechanical 55%, Fire 43% and Fabrication 2%. Recurring maintenance and minor works account for circa 35% of revenue, and Entire is expected to contribute an additional $60m+ on a pro forma basis in recurring maintenance, minor works and services revenue.
By sector, revenue was commercial 30%, data centres 25%, infrastructure 20%, health and aged care 15% and other 10%. By geography, Victoria contributed circa 90% and Queensland circa 10%.
Example projects include Snowy Hydro 2.0, North-East Link, NEXTDC PH1 and CDC Brooklyn BK1 & BK2.
Understanding fire protection and HVAC services
Fire protection covers the design, installation and maintenance of systems such as fire sprinklers, alarms, fire hydrants, hose reels, fire detection and gas suppression. HVAC stands for heating, ventilation and air-conditioning, and Entire’s core capabilities include air-conditioning, heating and energy management systems.
The presentation points to structural drivers for both. Strict regulatory and compliance requirements for fire protection systems drive long-term demand for services.
For HVAC, building owners are increasingly focused on performance from both a cost efficiency and environmental regulation perspective, with upgrades and redesign a key part. Because systems need ongoing testing and maintenance, both disciplines support recurring service work, which is relevant to sectors such as data centres, health care and infrastructure that Entire services.
Combined group profile and growth pathway
Pro forma shift
The presentation compared SCEE’s FY26 standalone revenue mix with the pro forma combined group, showing a broader capability and geographic spread.
| Metric | SCEE FY26 standalone | Pro forma combined |
|---|---|---|
| Electrical | 59% | 47% |
| Fire | 18% | 24% |
| Mechanical | Nil | 11% |
| Manufacturing | 13% | 10% |
| Security & Comms | 10% | 8% |
| NSW & ACT | 50% | 39% |
| VIC, SA & NT | 9% | 26% |
Pro forma combined FY27F EBITDA is expected to exceed $120m. SCEE is forecasting Entire to contribute $10m to FY27 EBITDA, assuming completion occurs on 1 November 2026.
Cross-selling and national fire platform
The presentation listed several combined opportunities:
- Cross-selling across the combined client base, offering complementary electrical, fire and mechanical (HVAC) capabilities
- Pursuit of larger, multi-disciplinary project scopes through a broader service offering
- Leveraging Entire’s established Victorian presence to support opportunities for other SCEE businesses
- Deepening relationships with data centre customers by providing a broader range of services
Entire is also positioned to further SCEE’s ambition to create a national fire services offering, alongside its existing NSW and Queensland presence. SCEE’s acquisition record includes Datatel (2016), Heyday (2017), the Trivantage Group (2020), the MDE Group (2024) and Force Fire (2025).
SCEE stated it will retain a strong balance sheet post-completion, providing flexibility for continued growth.
Stay Ahead on Industrials News Before the Market Moves
Join 20,000+ investors getting FREE breaking ASX news delivered to their inbox within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to receive real-time alerts the moment market-moving news breaks.