

Q1 FY27 highlights: Metal Powder Works moves copper from trials to a two-year contract
In its November 2026 results presentation covering Q1 FY27 (July to September 2026), Metal Powder Works (ASX: MPW) outlined how copper moved from trials to a long-term supply contract. The headline item was a two-year long-term agreement (LTA) with Embassy Powdered Metals worth ~A$855k, described as MPW’s first multi-year contract, with supply beginning January 2027.
Management reported 23 orders in the quarter, made up of 16 from repeat customers and 7 first deliveries. Backlog reached ~A$1.3m, up 630% on the June quarter, and more than 80% of revenue came from production powder sales, compared with 48% in the prior corresponding period.
The installed capacity target of ~800 t a year was brought forward to 1H CY27 from CY2028.
All figures below are in Australian dollars unless otherwise stated.
| Metric | Q1 FY27 |
|---|---|
| Revenue | $200K |
| Backlog orders | $1.3m |
| Orders received in the quarter | 23 |
| Cash at 30 September 2026 | $6.9m |
Operational items highlighted in the presentation included:
- NextGen #1 sustaining 100 t a year at over 95% saleable yield
- Dr Ahmed El Desouky appointed Chief Operating Officer
- Annual operating spend cut by ~A$0.4m
Revenue quality and visibility improved over the quarter, although quarterly revenue of $200K remains modest.
When big ASX news breaks, our subscribers know first
Commercial momentum and customer qualification across three markets
Pipeline, backlog and customer growth
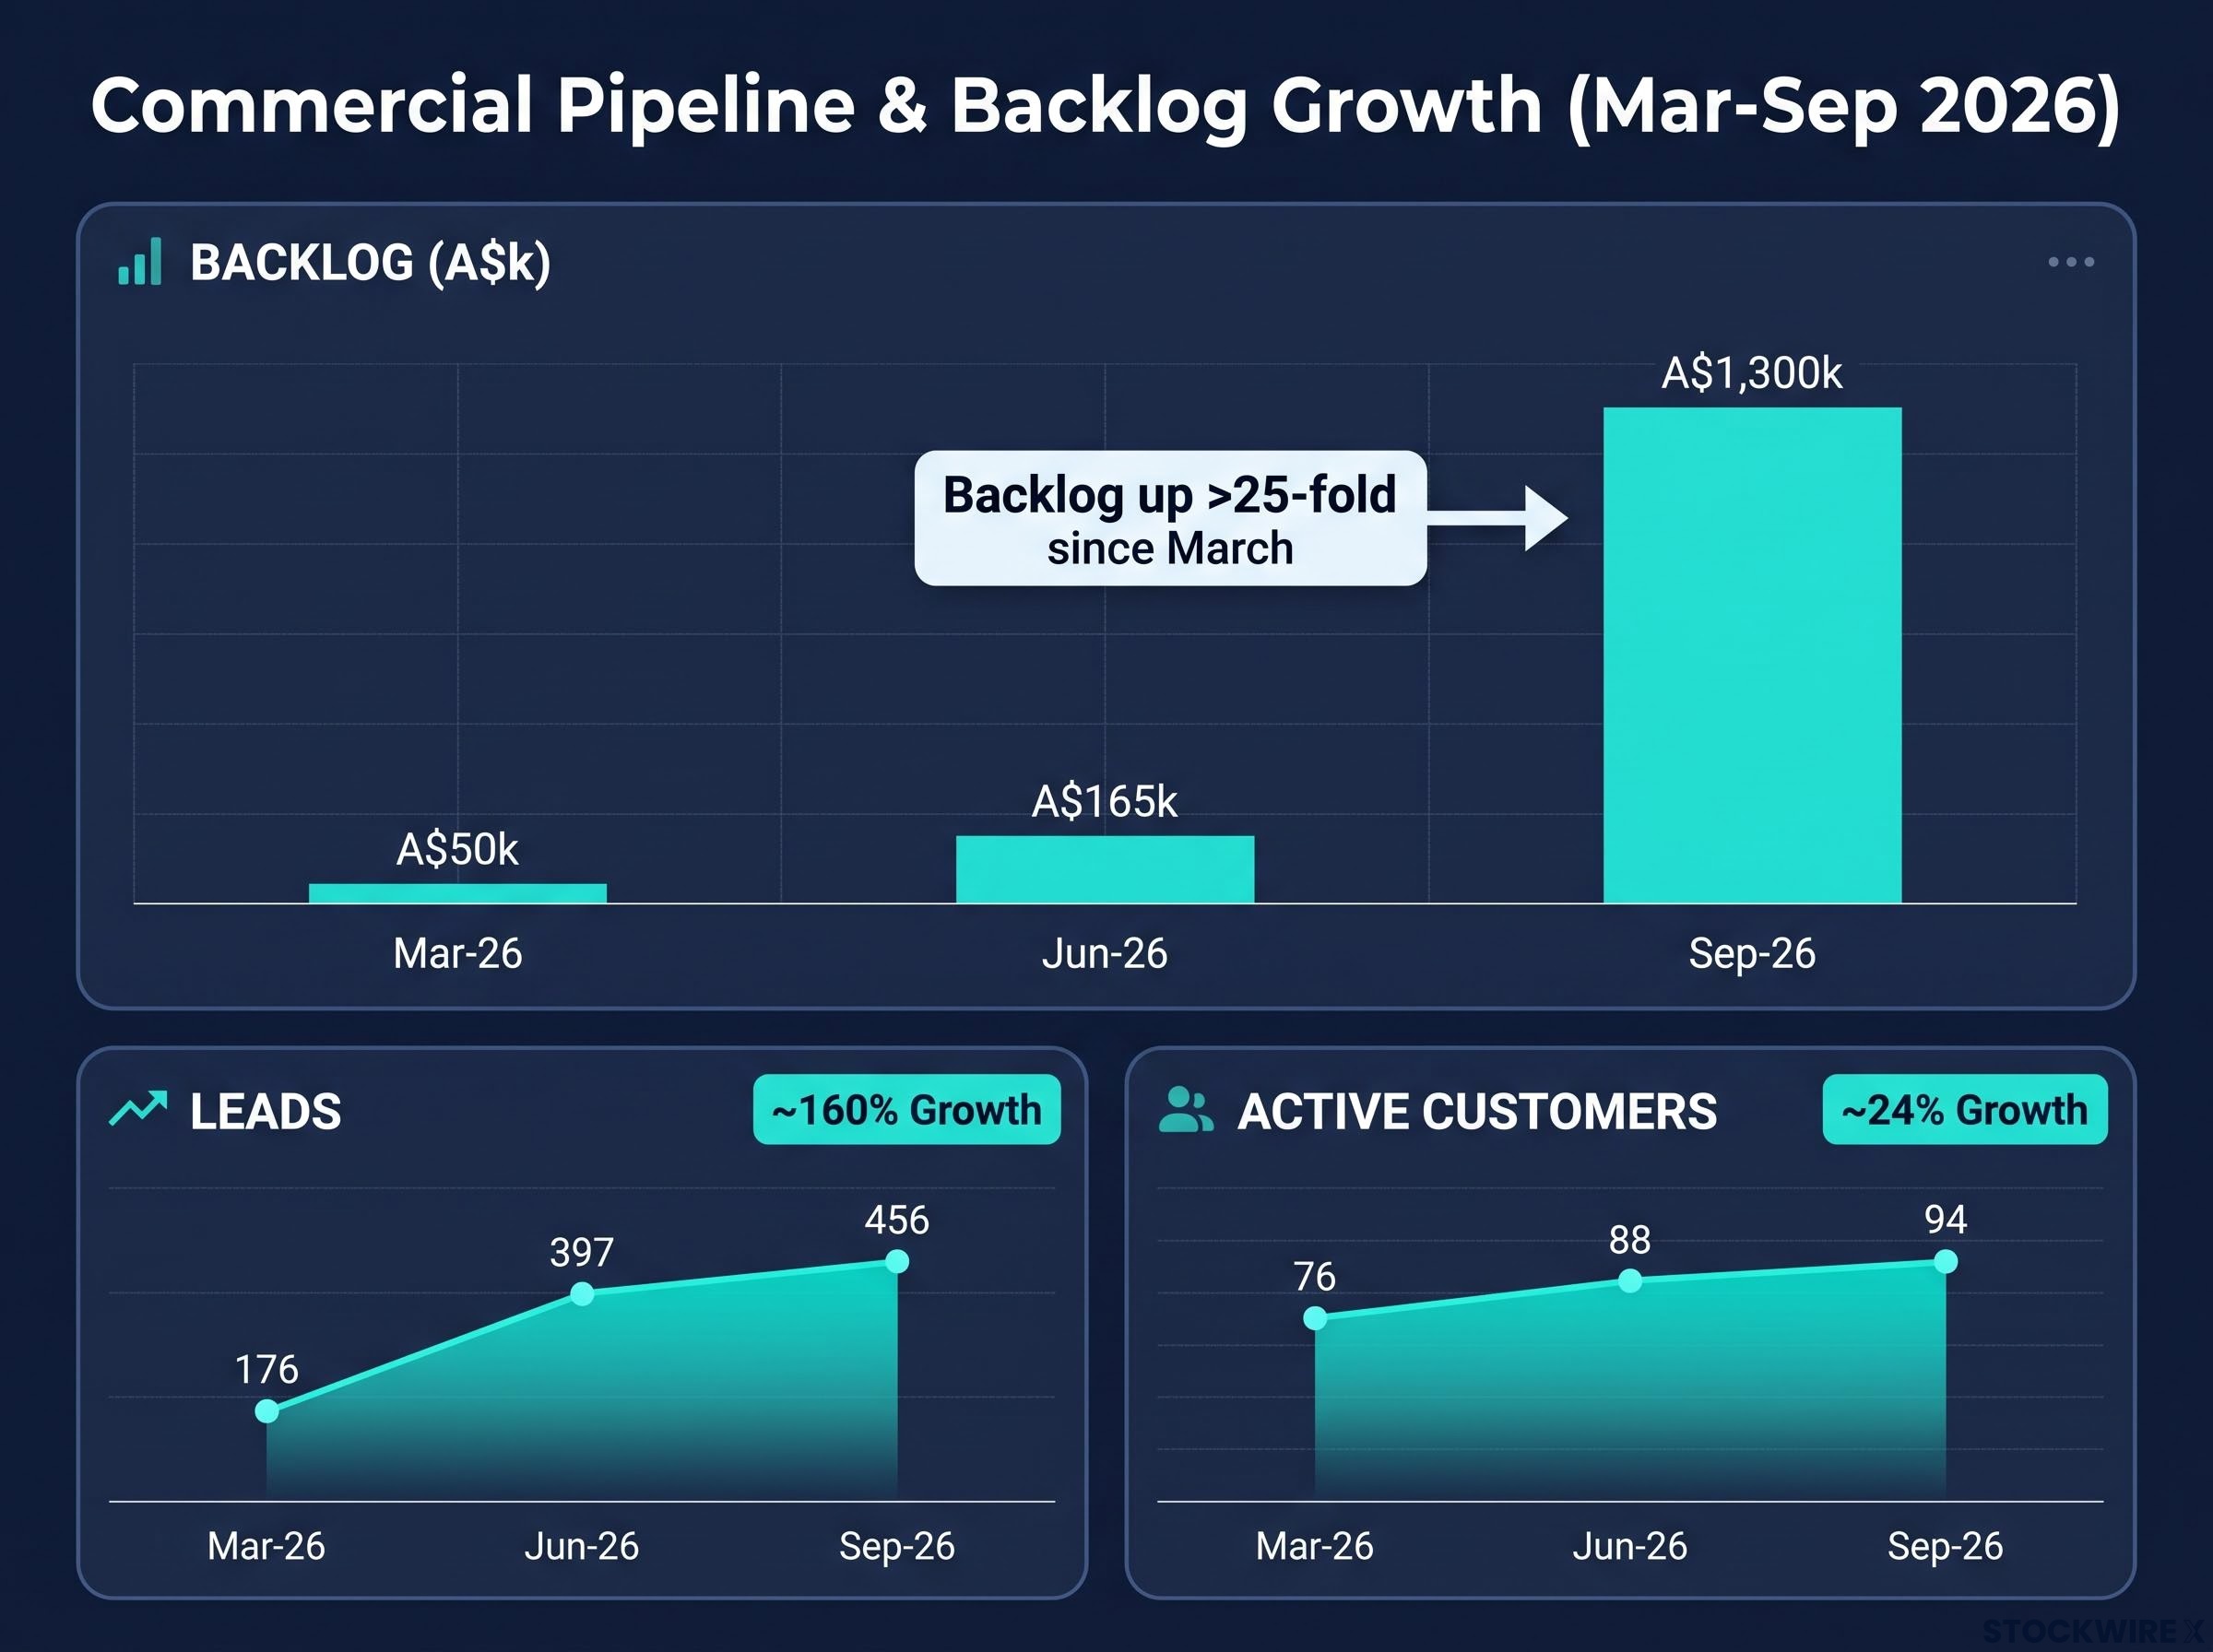
The presentation tracked leads, active customers and backlog across three periods, credited to a new sales team focused on customer retention and converting new accounts into revenue.
| Month | Leads | Active customers | Backlog (A$k) |
|---|---|---|---|
| Mar-26 | 176 | 76 | 50 |
| Jun-26 | 397 | 88 | 165 |
| Sep-26 | 456 | 94 | 1,300 |
Management summarised that since March, leads rose ~160%, active customers rose ~24% and backlog rose more than 25-fold. The quarter also included 59 new lead companies.
Qualification activity by market
The 23 orders spanned three markets:
- Powder metallurgy: 10 orders, with 8 for testing and qualification and 2 for production
- Cold spray: 7 orders
- Additive manufacturing: 6 orders, covering laser powder bed fusion (LPBF) testing and qualification
In defence, Al6061 powder was qualified for cold spray by UDRI through the US Army Research Laboratory, and a National Stock Number application has been lodged. A DirectPowder unit was also used by the US Navy at RIMPAC aboard CSS Asterix.
In copper, sales progressed from a test agreement (Jun-26) to repeat orders (Jul-26) to a supply agreement within 4 months. Management described Embassy as the template for conversations with similar press-and-sinter customers.
The Embassy supply agreement was announced in September 2026 and sits in a copper infiltration sub-segment, separate from MPW’s existing add-mix copper business, which points to repeatable demand across independent revenue channels.
How DirectPowder works and why the copper market opportunity matters
Bar in, powder out
Traditional atomisers melt metal and fix particle shape, so each plant serves one market. MPW’s patented DirectPowder process instead cuts powder directly from bar, with no furnace or atomising.
The presentation cited saleable yield of over 95% from standard bar. Particle size and shape are programmed, so one machine can switch between press-and-sinter and additive grades. MPW’s life cycle assessment (LCA) shows 90% less CO2 than water atomisation.
| Process | Press and sinter | Additive | Both from one plant | No melting |
|---|---|---|---|---|
| MPW NextGen | Yes | Yes | Yes | Yes |
| Water atomisation | Yes | Limited | No | No |
| Gas atomisation | Uneconomic | Yes | No | No |
| Plasma atomisation | Uneconomic | Yes | No | No |
| Electrolytic (copper) | Yes | No | No | Yes |
“Uneconomic” means technically possible but not at press-and-sinter prices. Serving several markets from one plant is the core of the investment case.
North American copper powder opportunity
The presentation sized the North American press-and-sinter copper powder market:
- ~11,000 t used a year (range 9,000 to 13,000 t)
- ~8,300 t made domestically, mostly by one supplier
- ~2,700 t (~25%) imported, mainly from Germany and the UK
- 50% Section 232 tariff on imports since April 2026
MPW produces in Pittsburgh, inside the US tariff wall. Its stated target is to take share from imports and the dominant domestic supplier.
Quantified pipeline and what happens next for MPW
Pipeline versus capacity
MPW quantified a copper pipeline of ~1,600 t a year and an alloy pipeline of ~163 t a year. Combined demand of ~1,760 t is over 2x the ~800 t capacity targeted for 1H CY27.
The capacity expansion plan was first brought forward in August 2026 and carries a total capital cost of about US$2.0 million, which management expects to fund from existing cash without an equity raise.
The presentation stated that quantified demand is not contracted and is not a forecast of sales, with conversion dependent on qualification, terms and capacity.
Press-and-sinter copper is expected to deliver volume sales, while additive manufacturing delivers the highest value sales.
Stated next steps
Management’s outlook listed the following:
- Embassy LTA supply begins in January 2027, starting contracted copper revenue.
- Installed capacity of ~800 t a year is targeted by 1H CY27, using the first tranche of four NextGen machines, with long-lead hardware for the second tranche of four.
- Pipeline conversion continues, with qualification cycles under way with several key press-and-sinter customers, and cold spray and additive test programs moving toward production.
- The National Stock Number for Al6061 cold spray powder is in progress.
- Delivering contracted revenue includes the RIMPAC deployment and qualifications under way with several customers.
Don’t Miss the Next Industrials Breakout
Join 20,000+ investors getting FREE breaking ASX news within minutes of release, complete with in-depth analysis and the full announcement. Click the “Free Alerts” button at Big News Blast to receive manufacturing and industrials updates the moment market-moving news breaks, before the wider market reacts.