

Record FY26 UNPATA of $107.9m highlighted at MMS 2026 AGM
In its 2026 AGM presentation on 23 October 2026, McMillan Shakespeare (ASX: MMS) outlined FY26 results led by record UNPATA of $107.9M (↑13.8%). Chair Helen Kurincic and CEO and Managing Director Rob De Luca presented to shareholders.
All financial and metric information is from Continuing operations unless otherwise stated, results are no longer Normalised, and variances are versus the prior comparative period.
Management highlighted a fully-franked dividend of $1.32 per share and a dividend yield of 6.6%, based on FY26 declared dividends per share and the 30 day VWAP share price to 21 August 2026. UNPATA growth of 13.8% compared with revenue growth of 6.8%, indicating earnings are growing faster than revenue.
The gap between earnings and revenue growth reflects operating leverage, with expenses rising only 2.8% against 6.8% revenue growth in the FY26 result, which lifted margins and returns on capital across the group.
FY26 results snapshot
The presentation detailed the following FY26 metrics.
| Metric | FY26 | Variance |
|---|---|---|
| Revenue | $602.1M | ↑6.8% |
| EBITDA | $180.7M | ↑14.1% |
| UNPATA | $107.9M | ↑13.8% |
| Statutory NPAT | $106.7M | ↑11.4% |
| Underlying EPS | $1.55 per share | ↑13.8% |
| ROCE | 62.1% | ↑83bps |
Returns and ESG
The company highlighted an MSCI ESG ‘AAA’ rating, upgraded from ‘AA’ in March 2026.
The Chair address also covered a sustainability strategy update and board succession. The presentation did not disclose further detail on either topic.
When big ASX news breaks, our subscribers know first
Strategy execution lifts operating margin by 250bps
Management said its strategy investments are delivering superior customer experiences, enhanced distribution and an improved operating margin, up 250bps.
Novated leasing and salary packaging are employee benefit arrangements administered by MMS, with novated leases covering vehicle costs. The presentation referred to certainty on EV FBT exemption and a shifting vehicle preference towards EVs in novated and fleet, both listed as supports for growth.
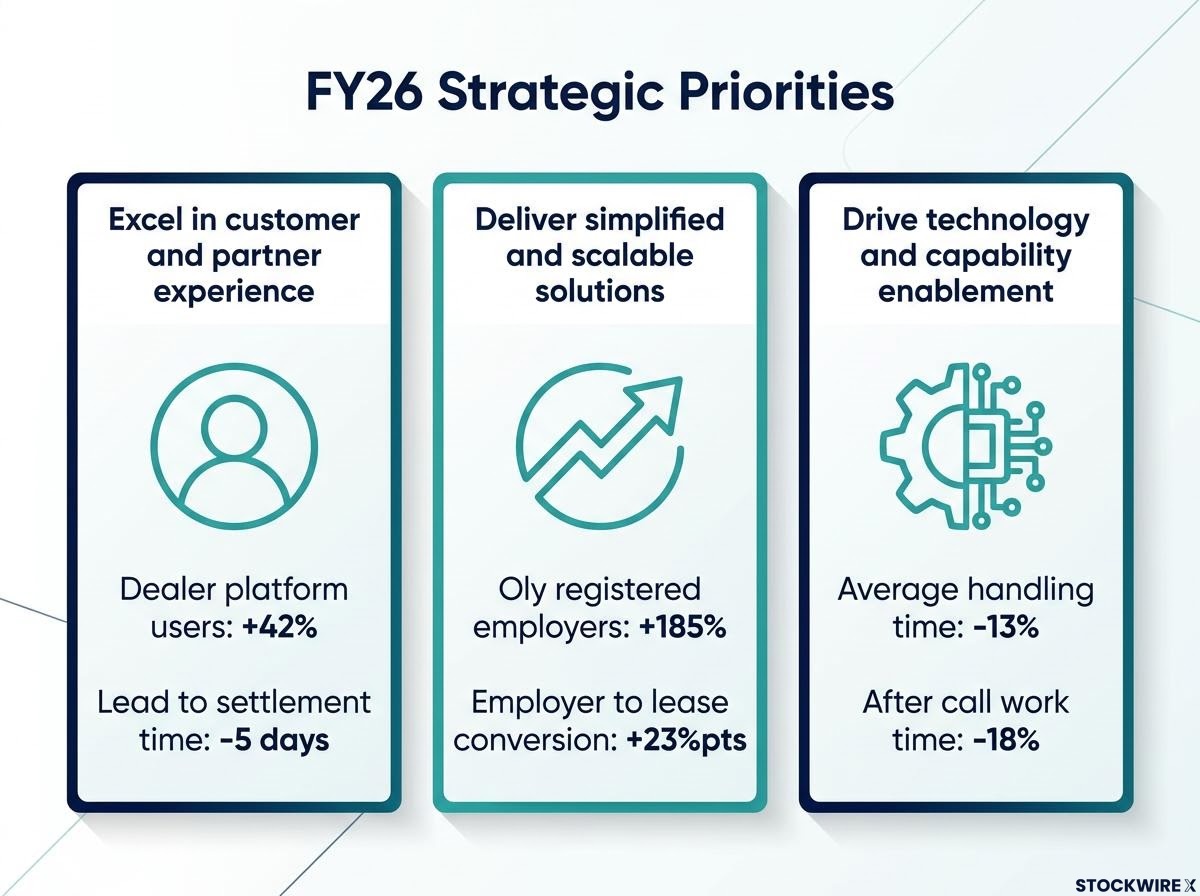
The company outlined three strategic priorities:
- Excel in customer and partner experience: users of the MMS dealer platform rose 42%, while lead to settlement time fell by approximately 5 days (Q4FY26 vs Q4FY25).
- Deliver simplified and scalable solutions: Oly registered employers rose 185% following the NAB partnership, and employer to lease conversion rose 23%pts (Jun-26 vs Jun-25).
- Drive technology and capability enablement: average handling time fell 13% and average after call work time fell 18%, following AI and data capability advances in GRS.
Management indicated productivity gains are expected to support selective reinvestment in broadening sales capability and enhancing customer value propositions.
Divisional scale
The FY26 business overview showed the following by division:
- Group Remuneration Services (GRS): 402k salary packages (↑7.1%) and 90k novated leases (↑13.5%)
- Asset Management Services (AMS): 16k fleet units (↑3.3%)
- Plan and Support Services (PSS): 44k customers (↑3.0%)
GRS recorded an NPS of +50, with 94% of claims digitally processed and a digital app rating of 4.6★.
Q1FY27 trading update and FY27 outlook
The Q1FY27 trading update was presented at the AGM, with all percentage movements versus the prior comparative period unless stated otherwise. Management described growth across all key customer numbers.
| Metric | Q1FY27 | Variance |
|---|---|---|
| GRS Salary packages | 409k | ↑6.8% |
| GRS Novated leases | 95k | ↑17.5% |
| PSS Customers | 44.1k | ↑2.7% |
| AMS Fleet units | 15.5k | ↑1.7% |
On demand, the presentation noted:
- GRS novated sales rose 14%, with 75% of new novated sales BEV.
- AMS funded EV units were 17%, up 13.6%pts.
Some measures moved lower. GRS novated yield fell 4% (flat versus Q4FY26), and AMS vehicle remarketing profits fell 15%.
FY27 outlook
Management stated the outlook is consistent with commentary provided with the FY26 Results Presentation. It described a supportive environment for growth, citing Q1FY27 novated lease sales momentum (up 14%), certainty on EV FBT exemption, and demand for salary packaging amid continued cost of living and inflationary pressures.
Remarketing profits are expected to reflect slower asset replacement cycles, elevated demand for EVs and softer demand for ICE used vehicles. PSS was described as the second largest and well positioned Plan Management provider, and it continues to engage on emerging NDIS reforms.
The presentation closed on ongoing execution of the three strategic priorities. No forecasts or guidance figures were provided.
Stay Ahead on ASX Consumer and Finance News
Get FREE breaking ASX news delivered to your inbox within minutes of release, with in-depth analysis already done. Join 20,000+ investors using Big News Blast to stay ahead of the market on Tech, Healthcare, Finance and Consumer stocks. Click the “Free Alerts” button to start receiving alerts the moment news breaks.